

The Yuh&Me joint account at a glance
| Name | Yuh&Me joint account |
| Provider | Yuh, a brand of Swissquote Bank Ltd (FINMA-supervised) |
| Account fee | CHF 0 per month |
| Cards | up to 4 Mastercard Debit (2 physical, 2 virtual), free |
| TWINT | Own TWINT app |
| CH IBAN | own Swiss IBAN for the joint account |
| eBill | |
| Max. number of account holders | 2 |
| Shared address | not required |
| Minimum age | 18 (both people) |
| Exchange rate markup | 0.95 % on the interbank rate |
| Interest on balance | 0 % |
| Investing together | not possible |
| Opening process | fully digital in the Yuh app |
| Deposit insurance | Cash deposits protected up to CHF 100'000 in the event of bankruptcy. |
| Verified on | 19.08.2026 |
What is the Yuh&Me joint account?
Yuh&Me is a fully fledged joint account for a maximum of two people with its own Swiss IBAN, held with Swissquote Bank Ltd. It is designed for everything you share anyway: the standing order for the flat, the internet subscription, shared streaming subscriptions, the weekly shop, eating out, right through to holiday money. It does not replace your personal Yuh accounts; the joint account is added as a third account.
Yuh has integrated the joint account sensibly into the existing Yuh app: its own view, its own cards, its own savings projects, its own notifications for both of you.
One confusing detail: “Yuh&Me” is a marketing name. It does not appear anywhere in the app, where the product is called “joint account”.
The joint account comparison Switzerland shows how the Yuh joint account measures up against the other Swiss providers.
How does Yuh&Me work day to day?
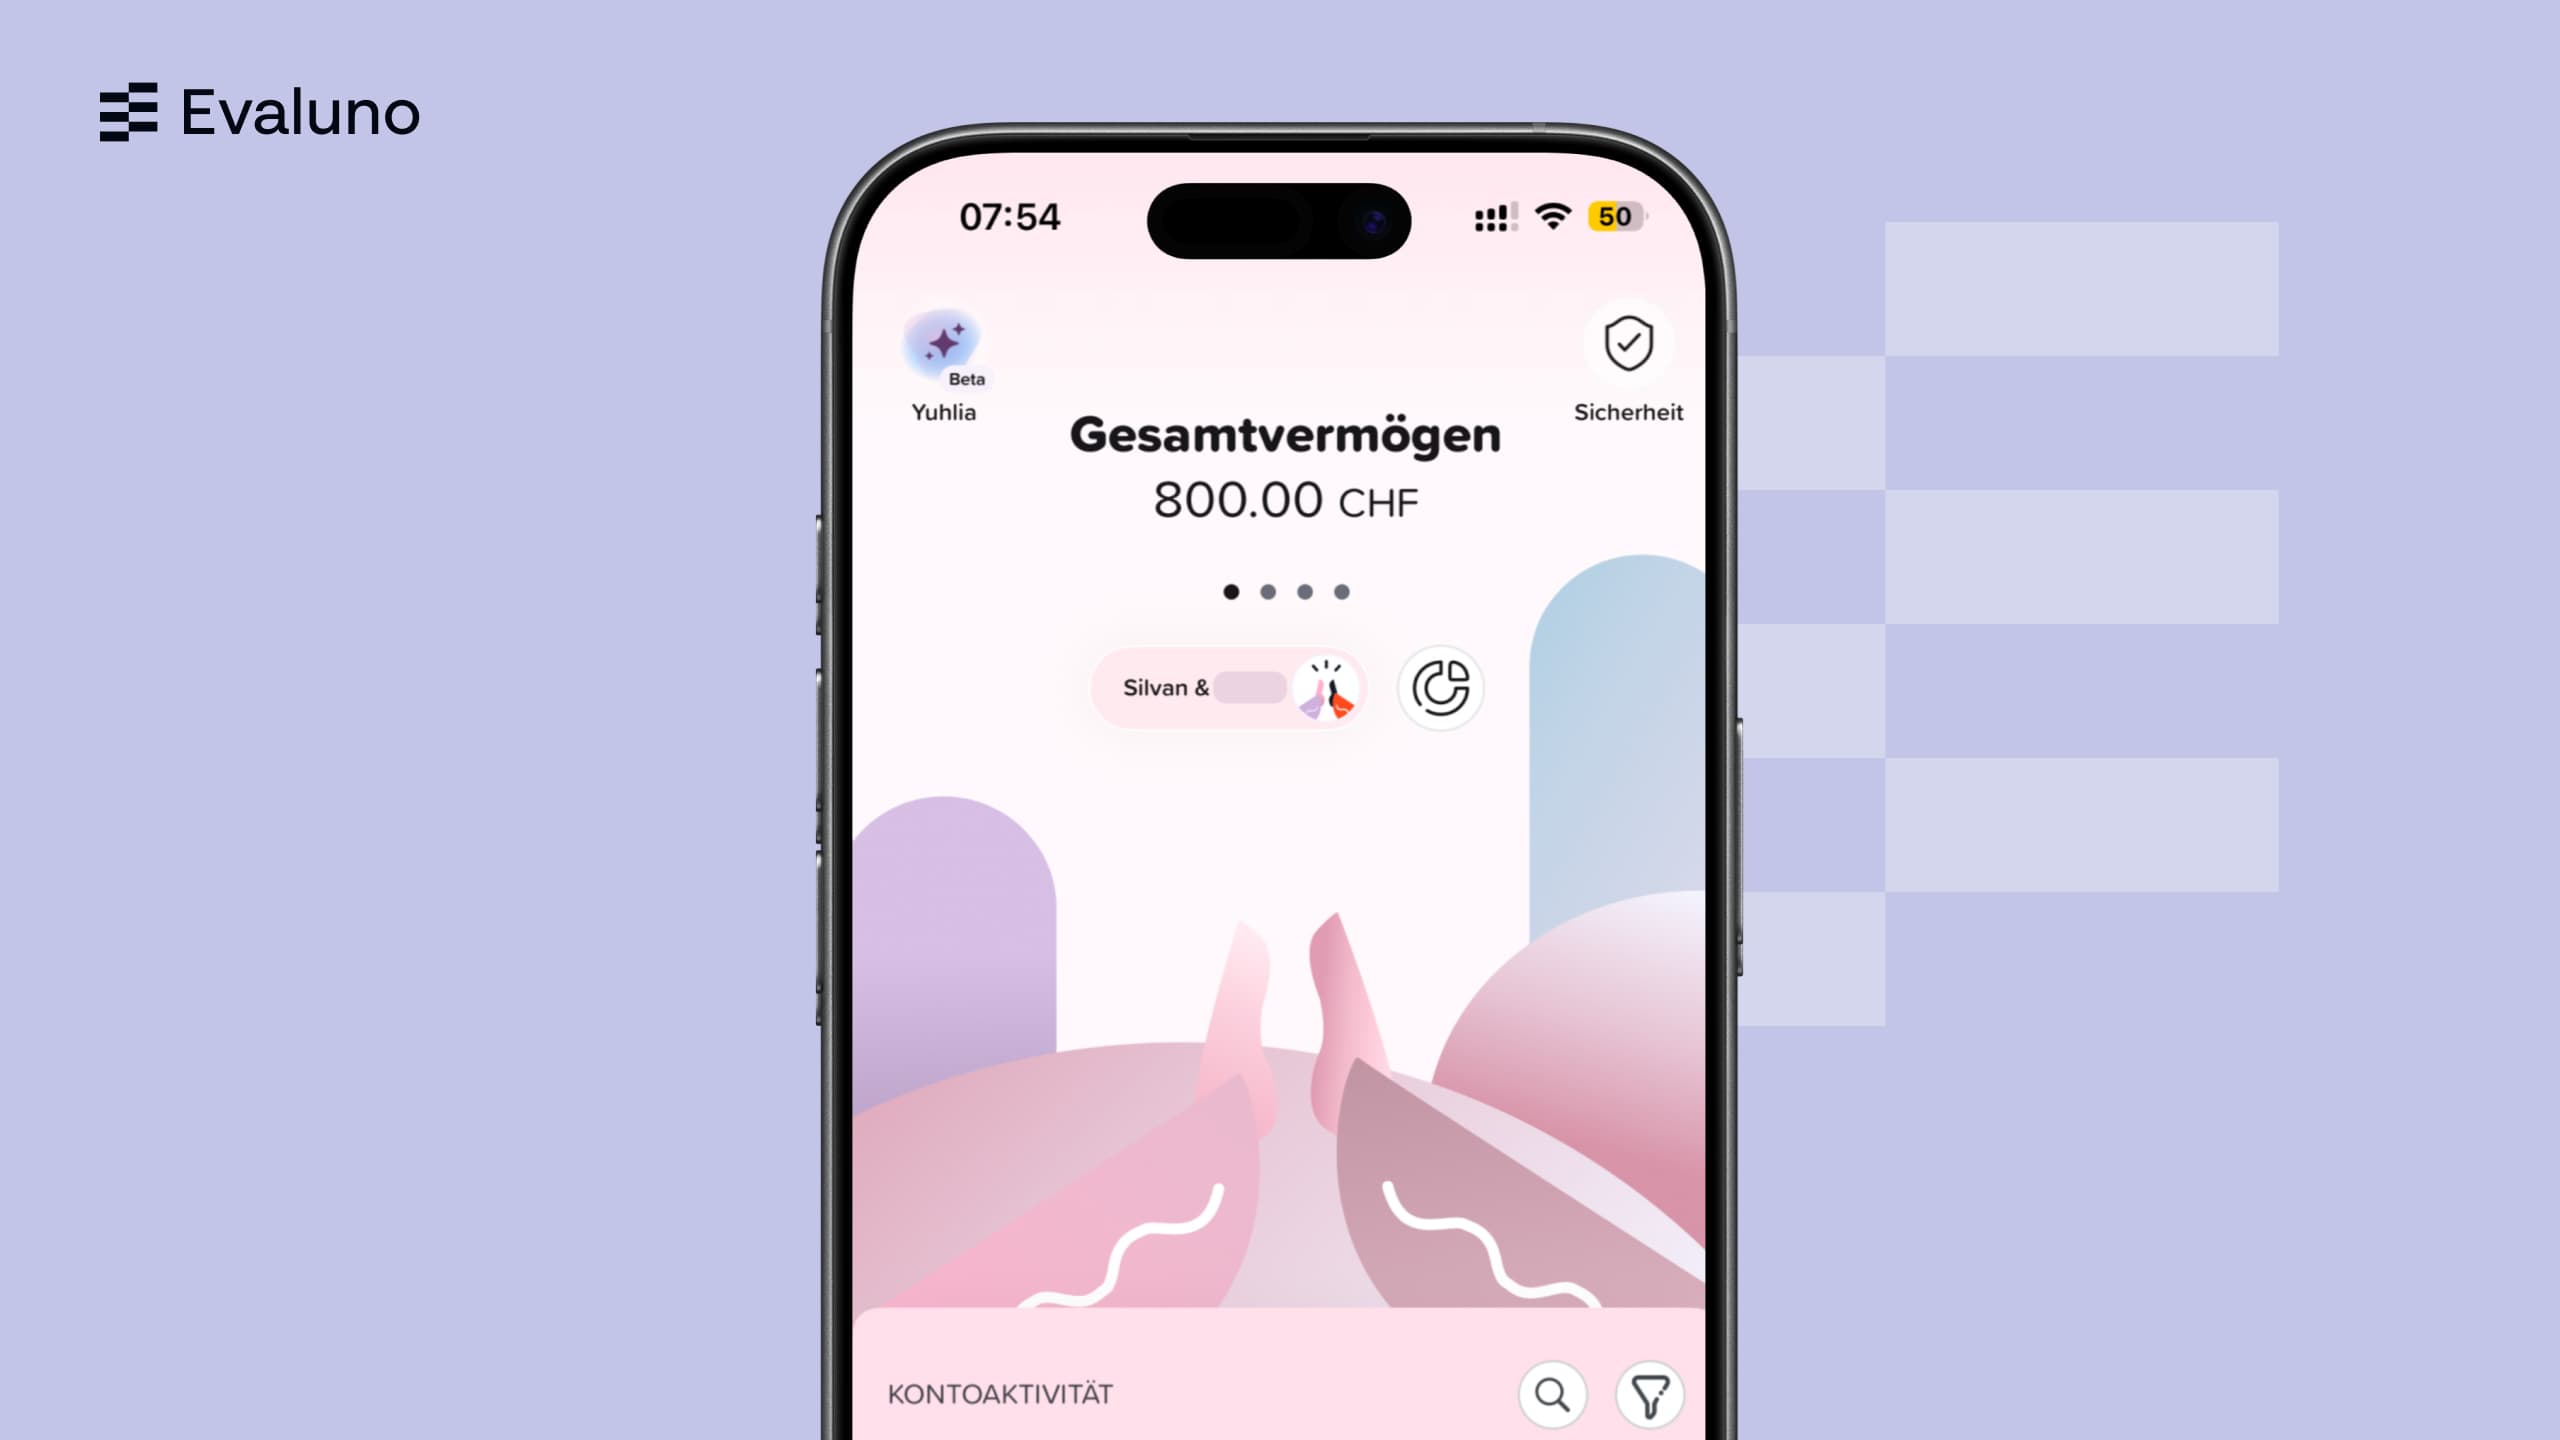
Day to day, Yuh&Me runs through the same Yuh app as your personal Yuh account. A tap on the account name switches between private and shared account. Whatever you do in the shared area only affects the joint account. What is in your private account stays private. You need to be aware of this, because on the shared account both of you see every transaction.
For most couples and two-person flatshares the typical set-up looks like this: both set up a monthly standing order from their personal Yuh account or a Swiss bank account to the Yuh joint account. Rent by standing order, the weekly shop, the internet subscription and other expenses are then paid from the shared balance. How you split the contributions is up to you: equally or weighted by income.
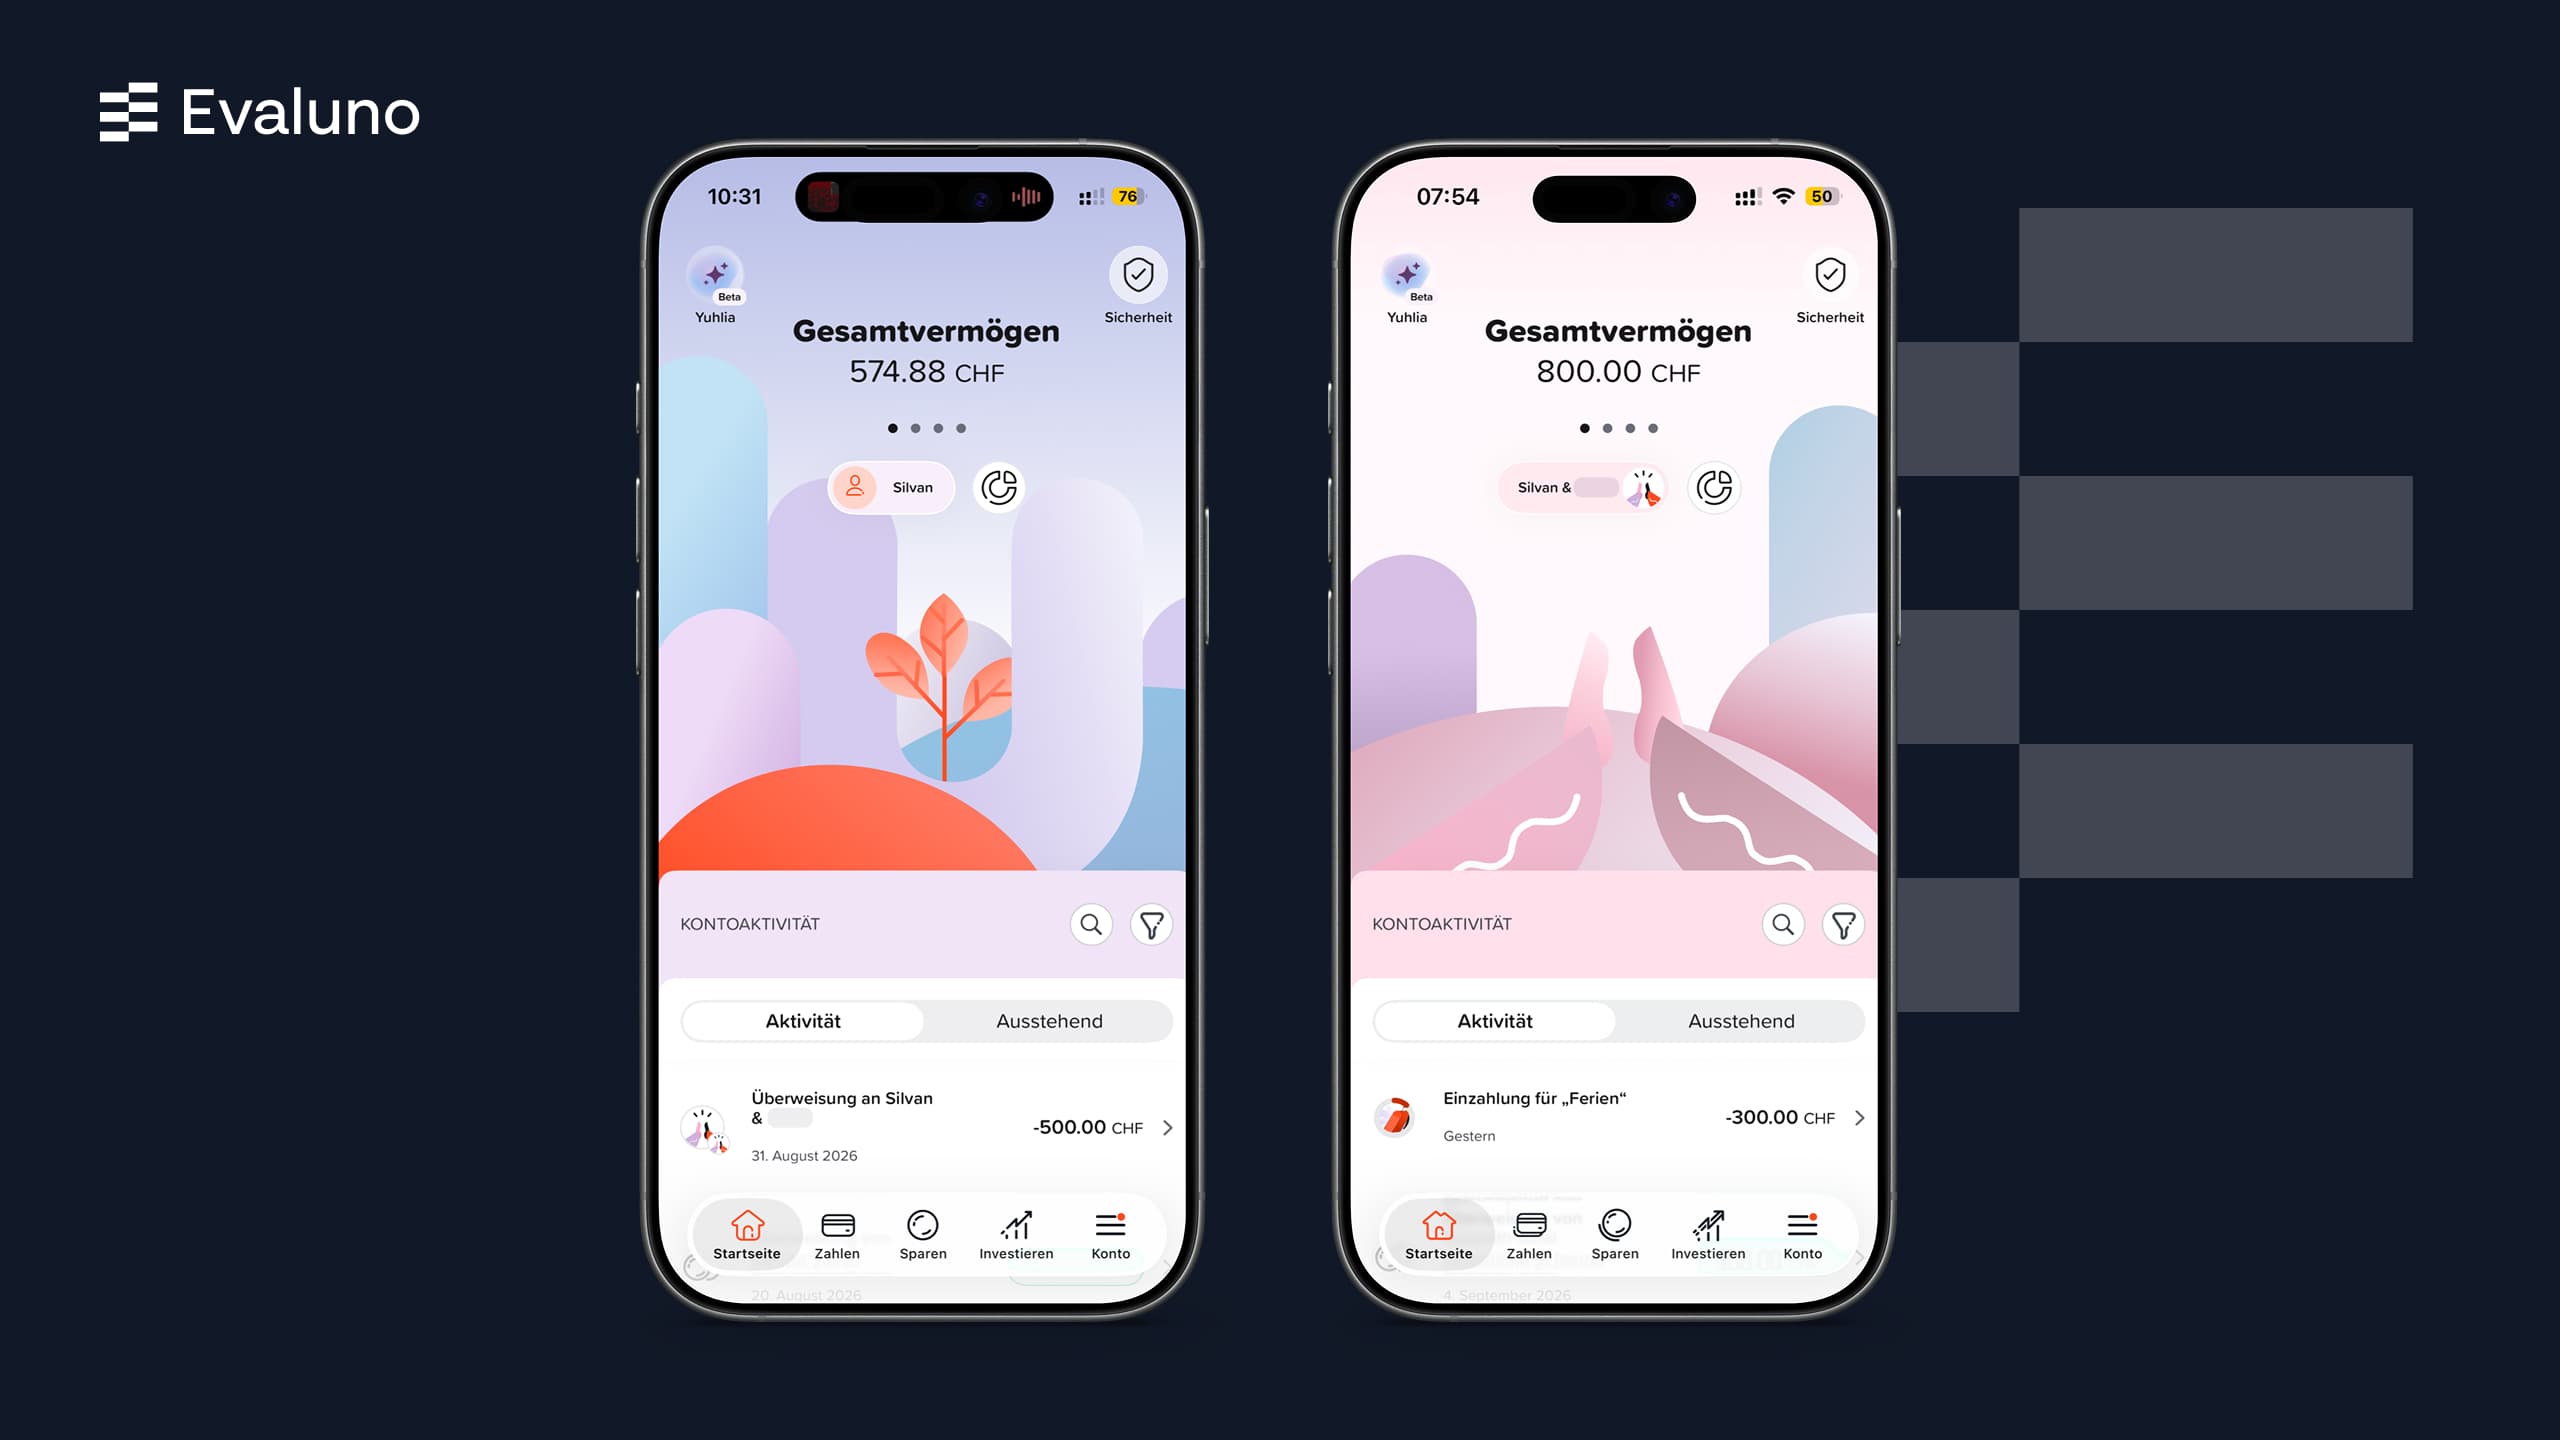
On the joint account, both of you see every card payment, every transfer and every savings milestone, including a push notification on both phones.
Important to understand: Yuh&Me is a so-called “either-or” account (individual signing authority). Both people can pay, withdraw and transfer on their own without asking the other. For a household account, that is the only workable logic.
What are the key features of the Yuh joint account?
The five core features of Yuh&Me: its own Swiss IBAN, up to four free Mastercards, TWINT directly from the shared account, eBill and unlimited shared savings projects. On top of that come multi-currency accounts and insurance included.
Cards: four Mastercards, two physical and two virtual
Both account holders receive a virtual Mastercard immediately after opening and can each order a physical one (no shipping costs). All four cards are issued free of charge and are linked directly to the joint account.
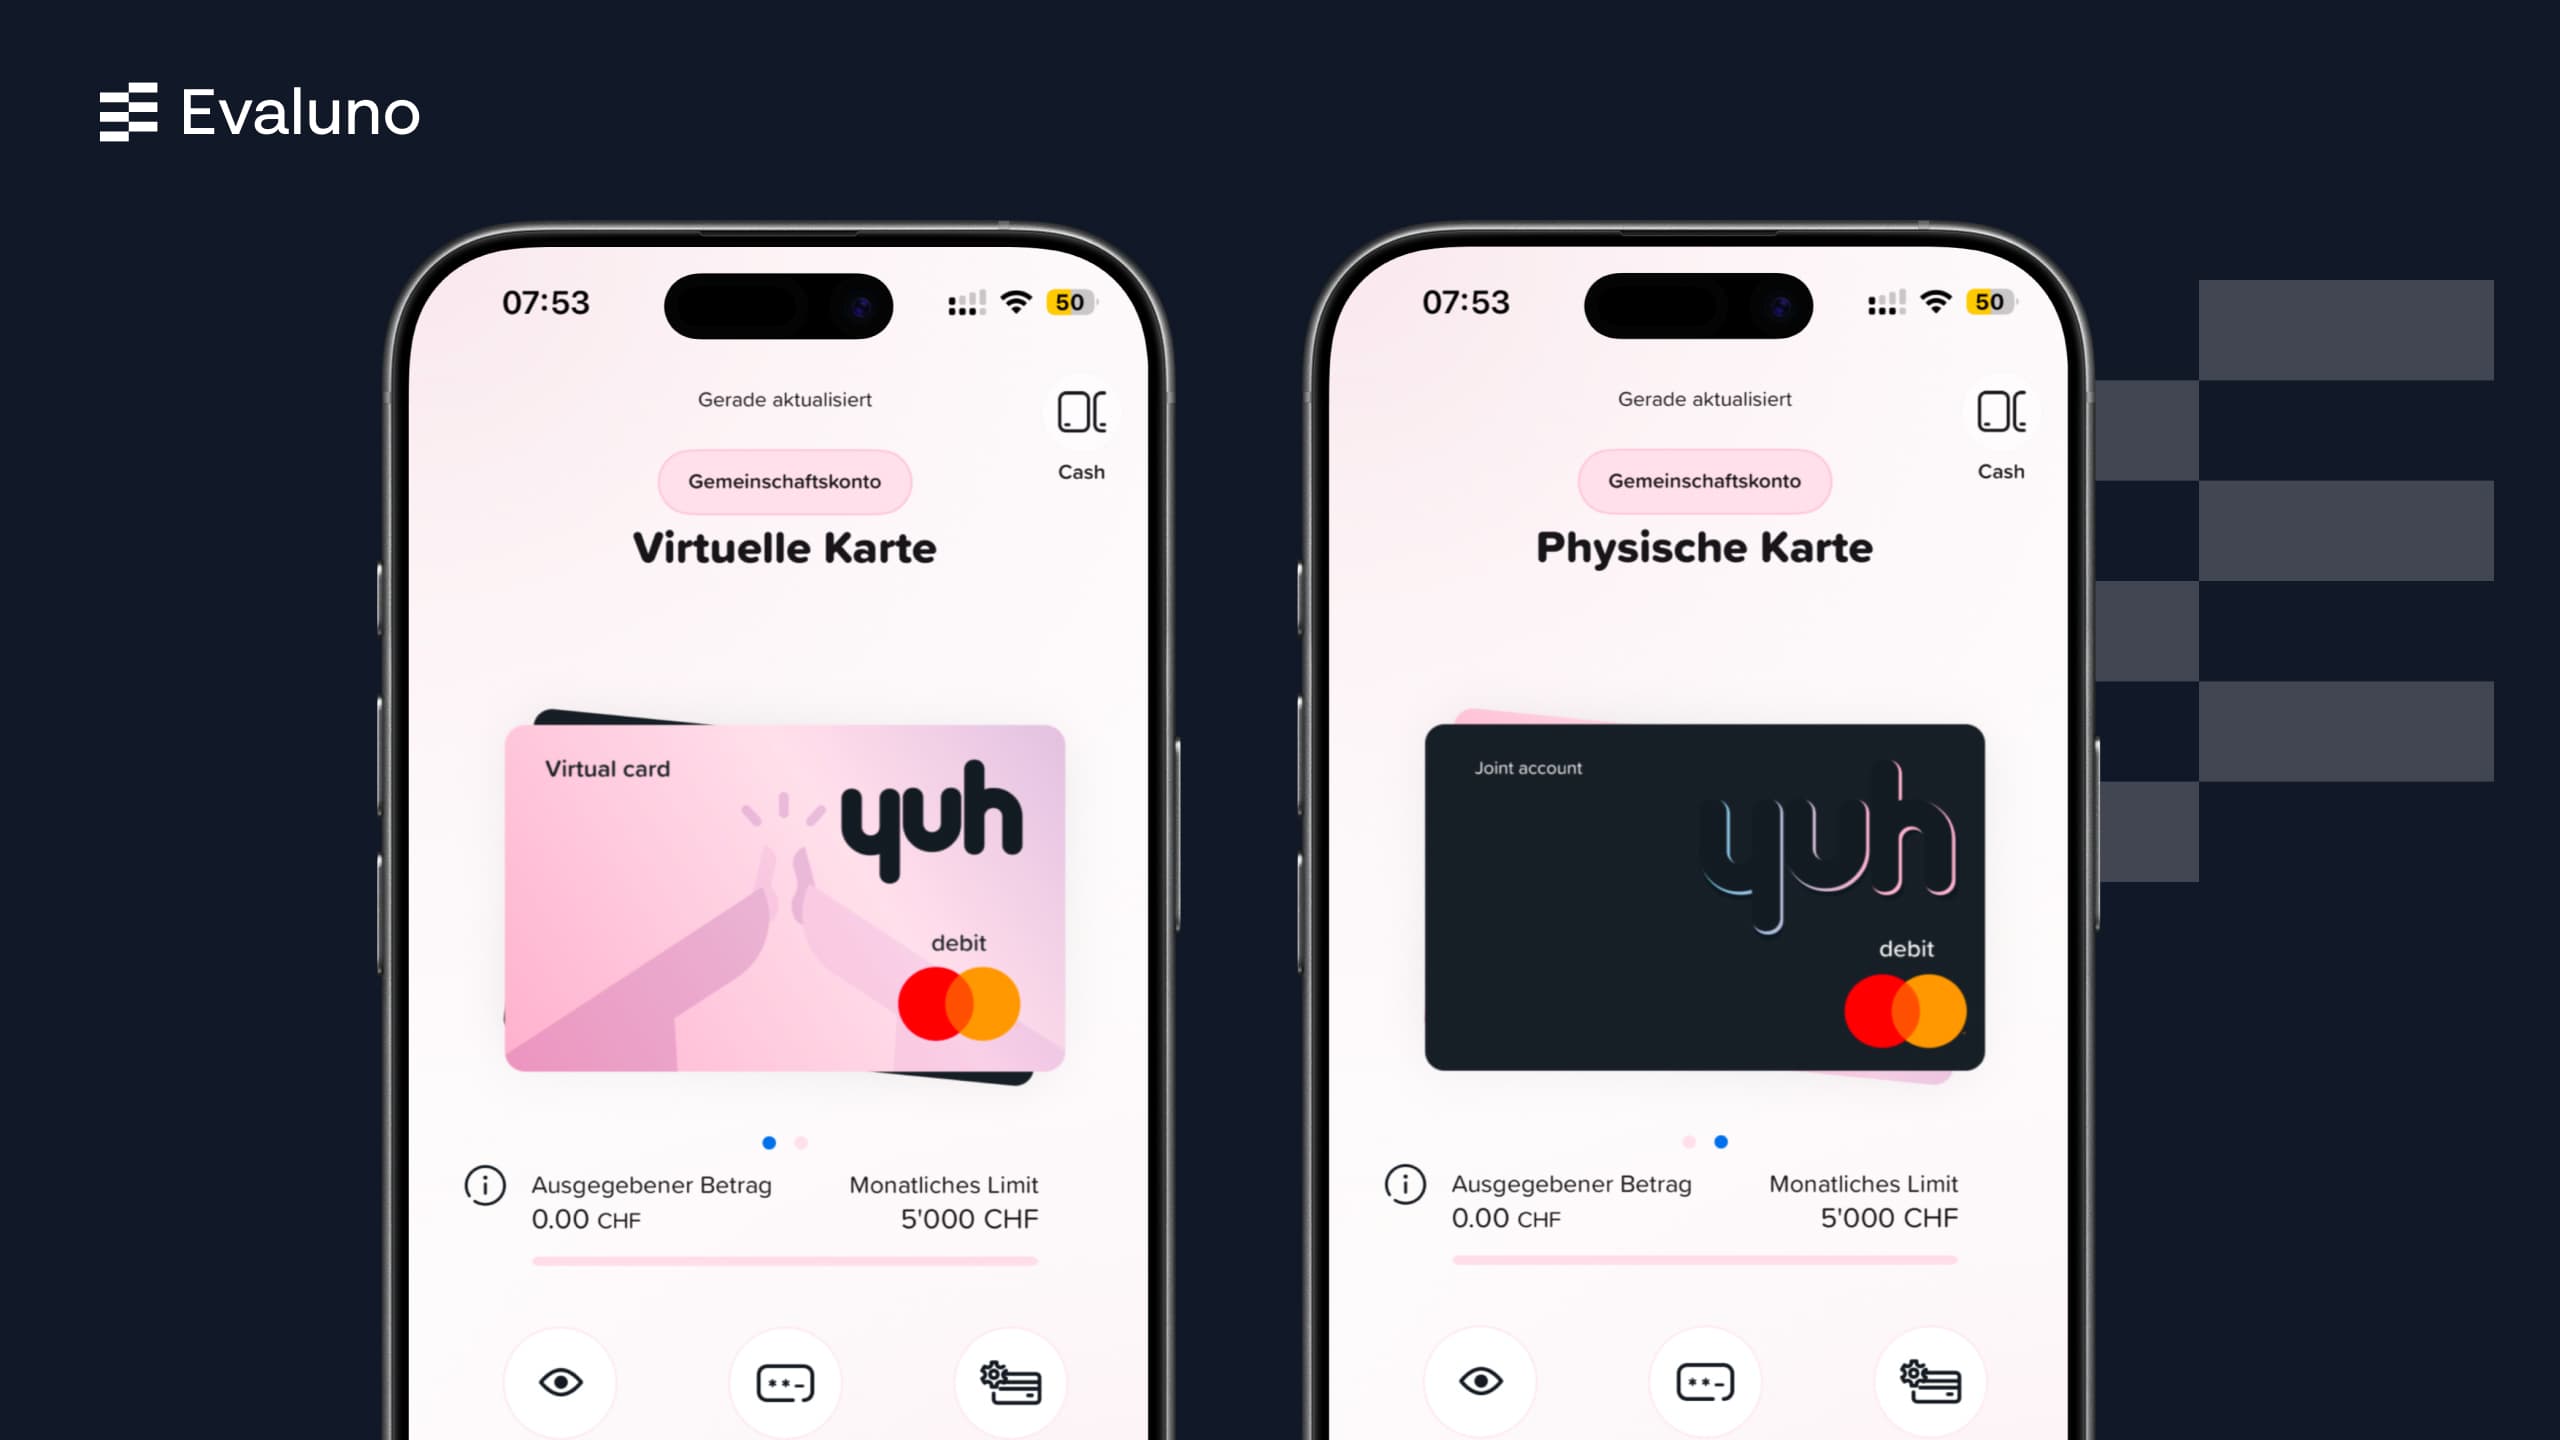
A look at the other providers shows how unusual that is: Migros Bank charges CHF 30 per year for the second card, Raiffeisen CHF 30 to 40, neon duo a one-off CHF 10 per card. Yuh charges nothing, and on top of that you each get a virtual card for use with your smartphone or computer (e.g. Apple Pay, Google Pay).
A warning from our own use: the joint account card looks confusingly similar to the private Yuh card. The cards differ only by a small imprint. Anyone carrying both in their wallet will sooner or later pay for a private coffee from the shared account.
TWINT: directly from the joint account
With Yuh&Me, TWINT works fully and directly from the shared account, not via a prepaid top-up. In the settings of the Yuh TWINT app you define which account is debited by default. You can select the account for payments in shops as well as for online payments and for sending money to other people. That way you choose flexibly whether a transfer runs through your own or the shared account.
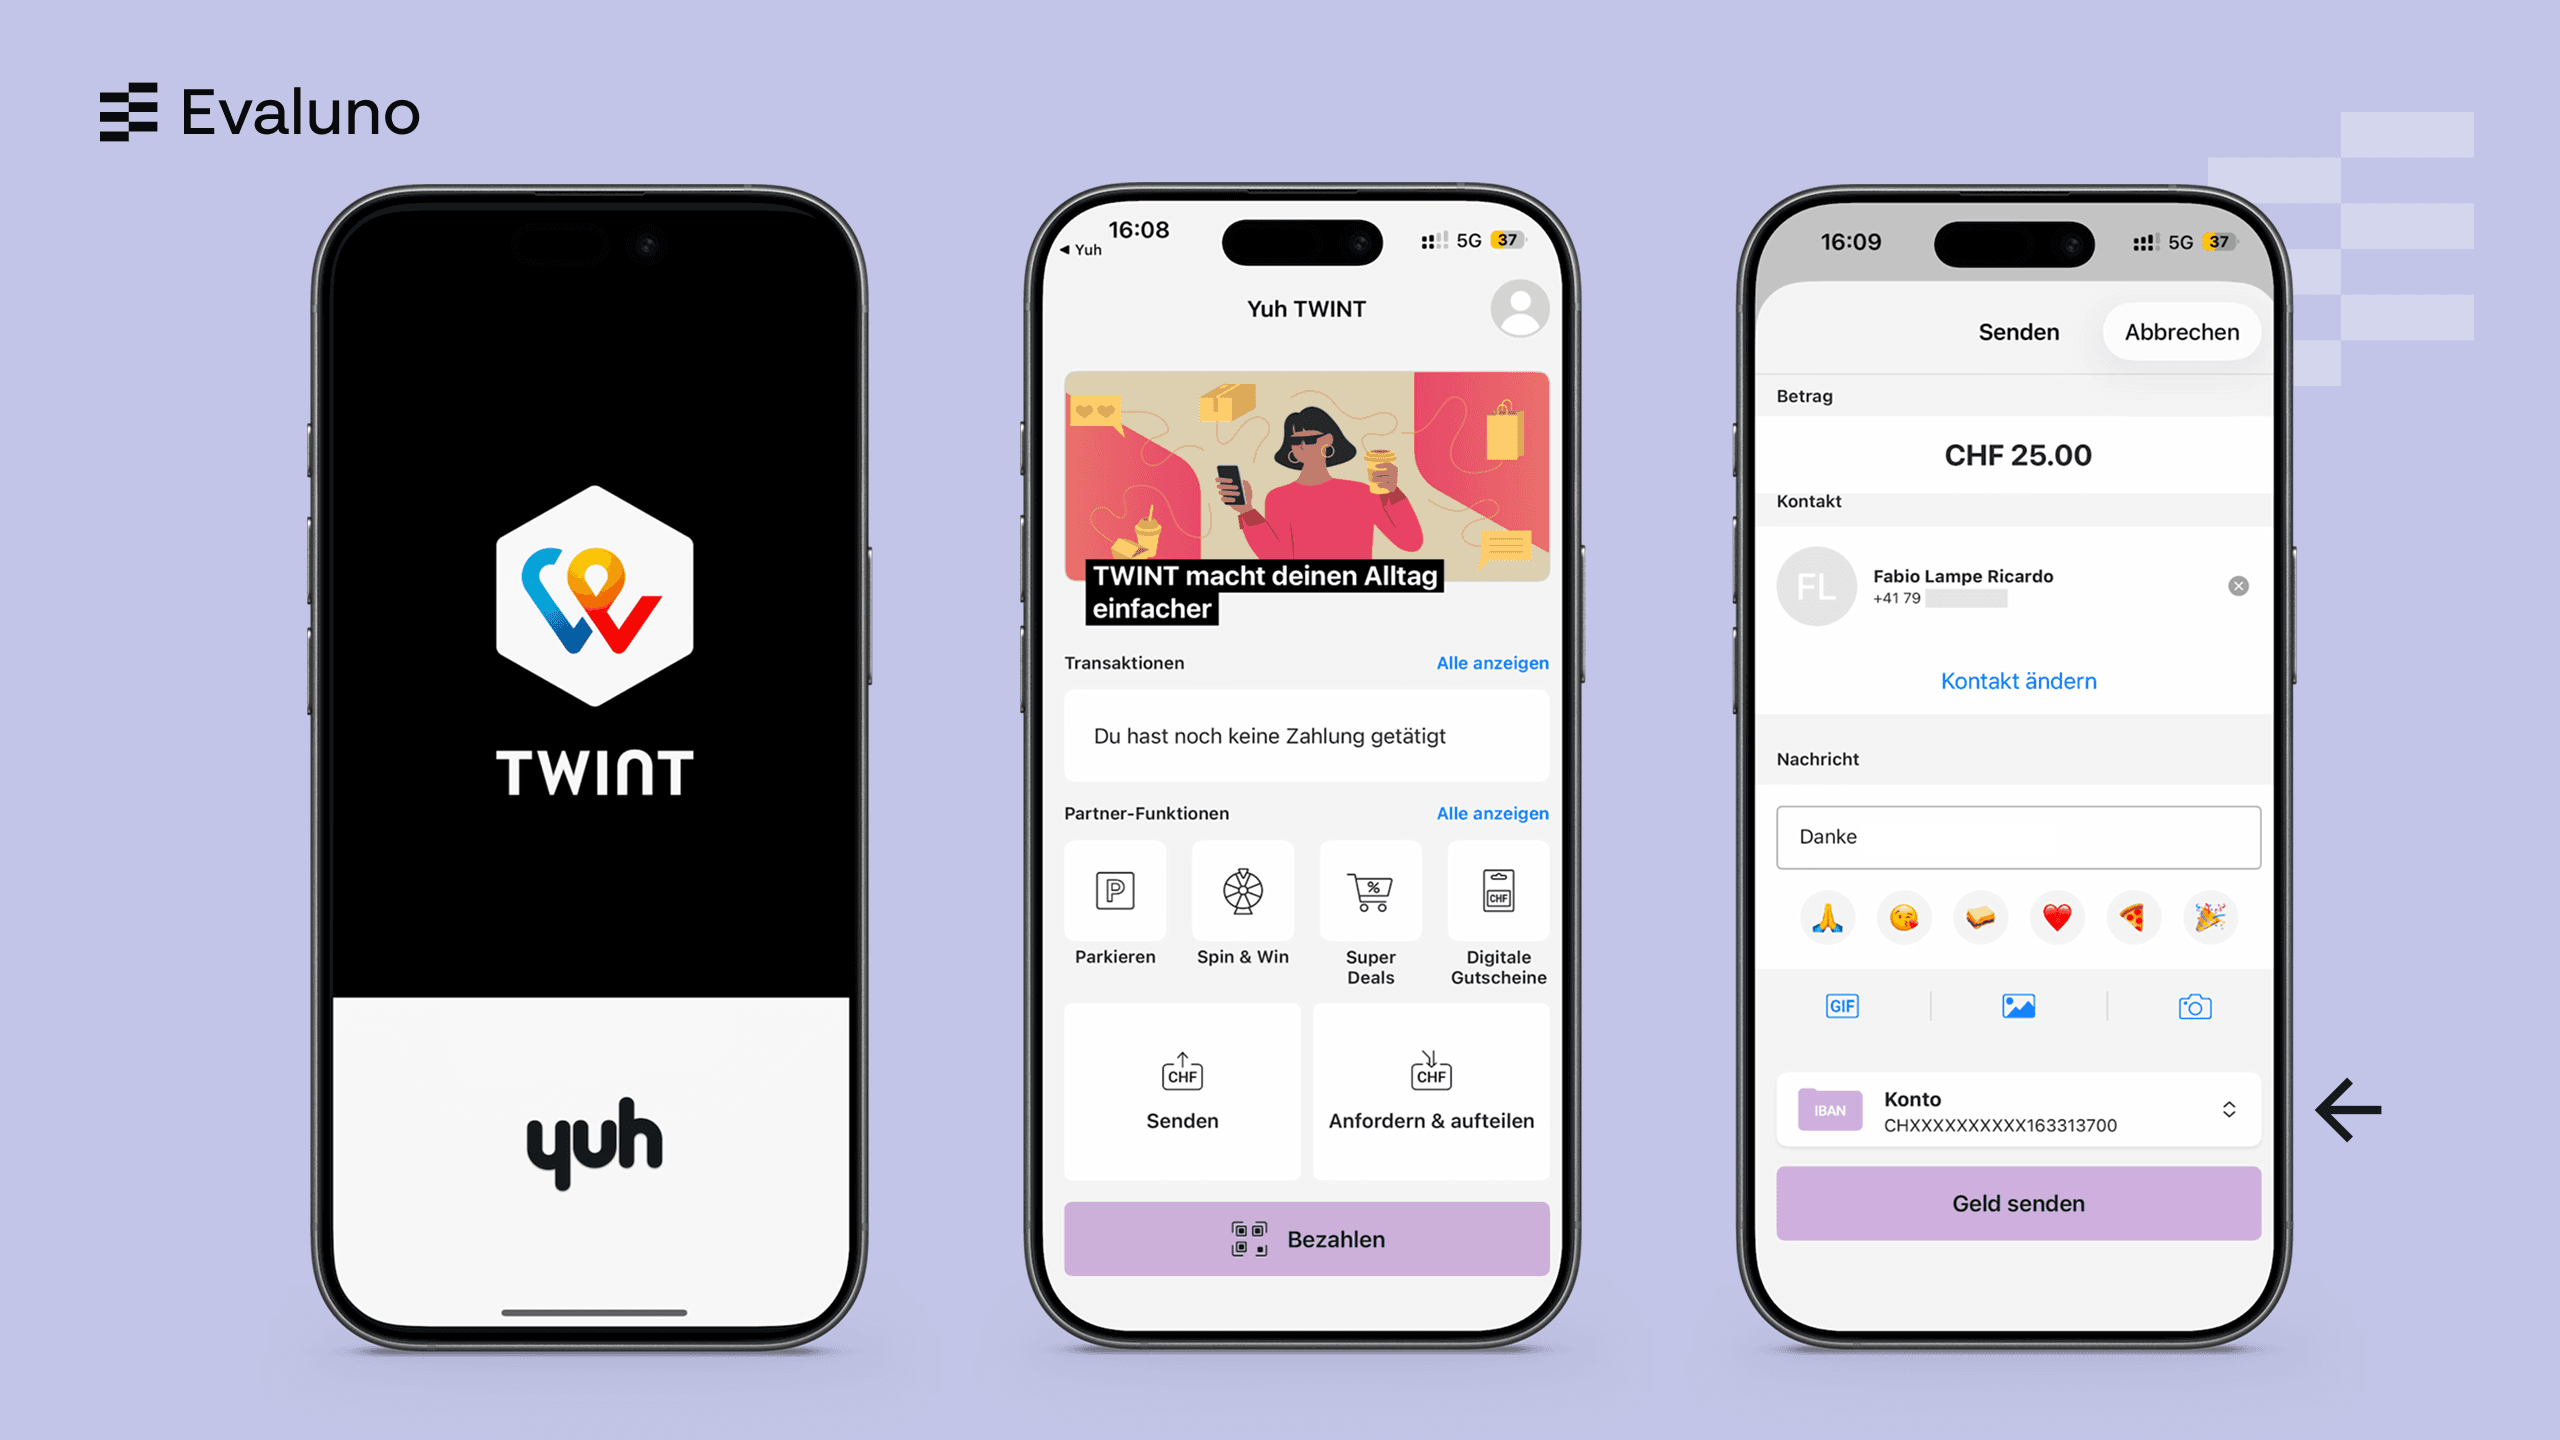
Why this matters: in Switzerland, a considerable share of small shared expenses goes through TWINT. The online marketplace, the flea market, the club kitty, paying friends back. Unlike with the other providers, with Yuh you have a perfect solution for TWINT payments like these.
eBill: pay shared bills the easy way
Insurance, Serafe, the internet subscription: almost all regular bills can be paid by eBill directly from the joint account.
That does away with the tedious ritual of one person paying the bill from their private account and then having to claim half of it back. A use case that shows how this back and forth disappears with a joint account.
Shared savings projects: holidays, furniture, car, wedding, flat party
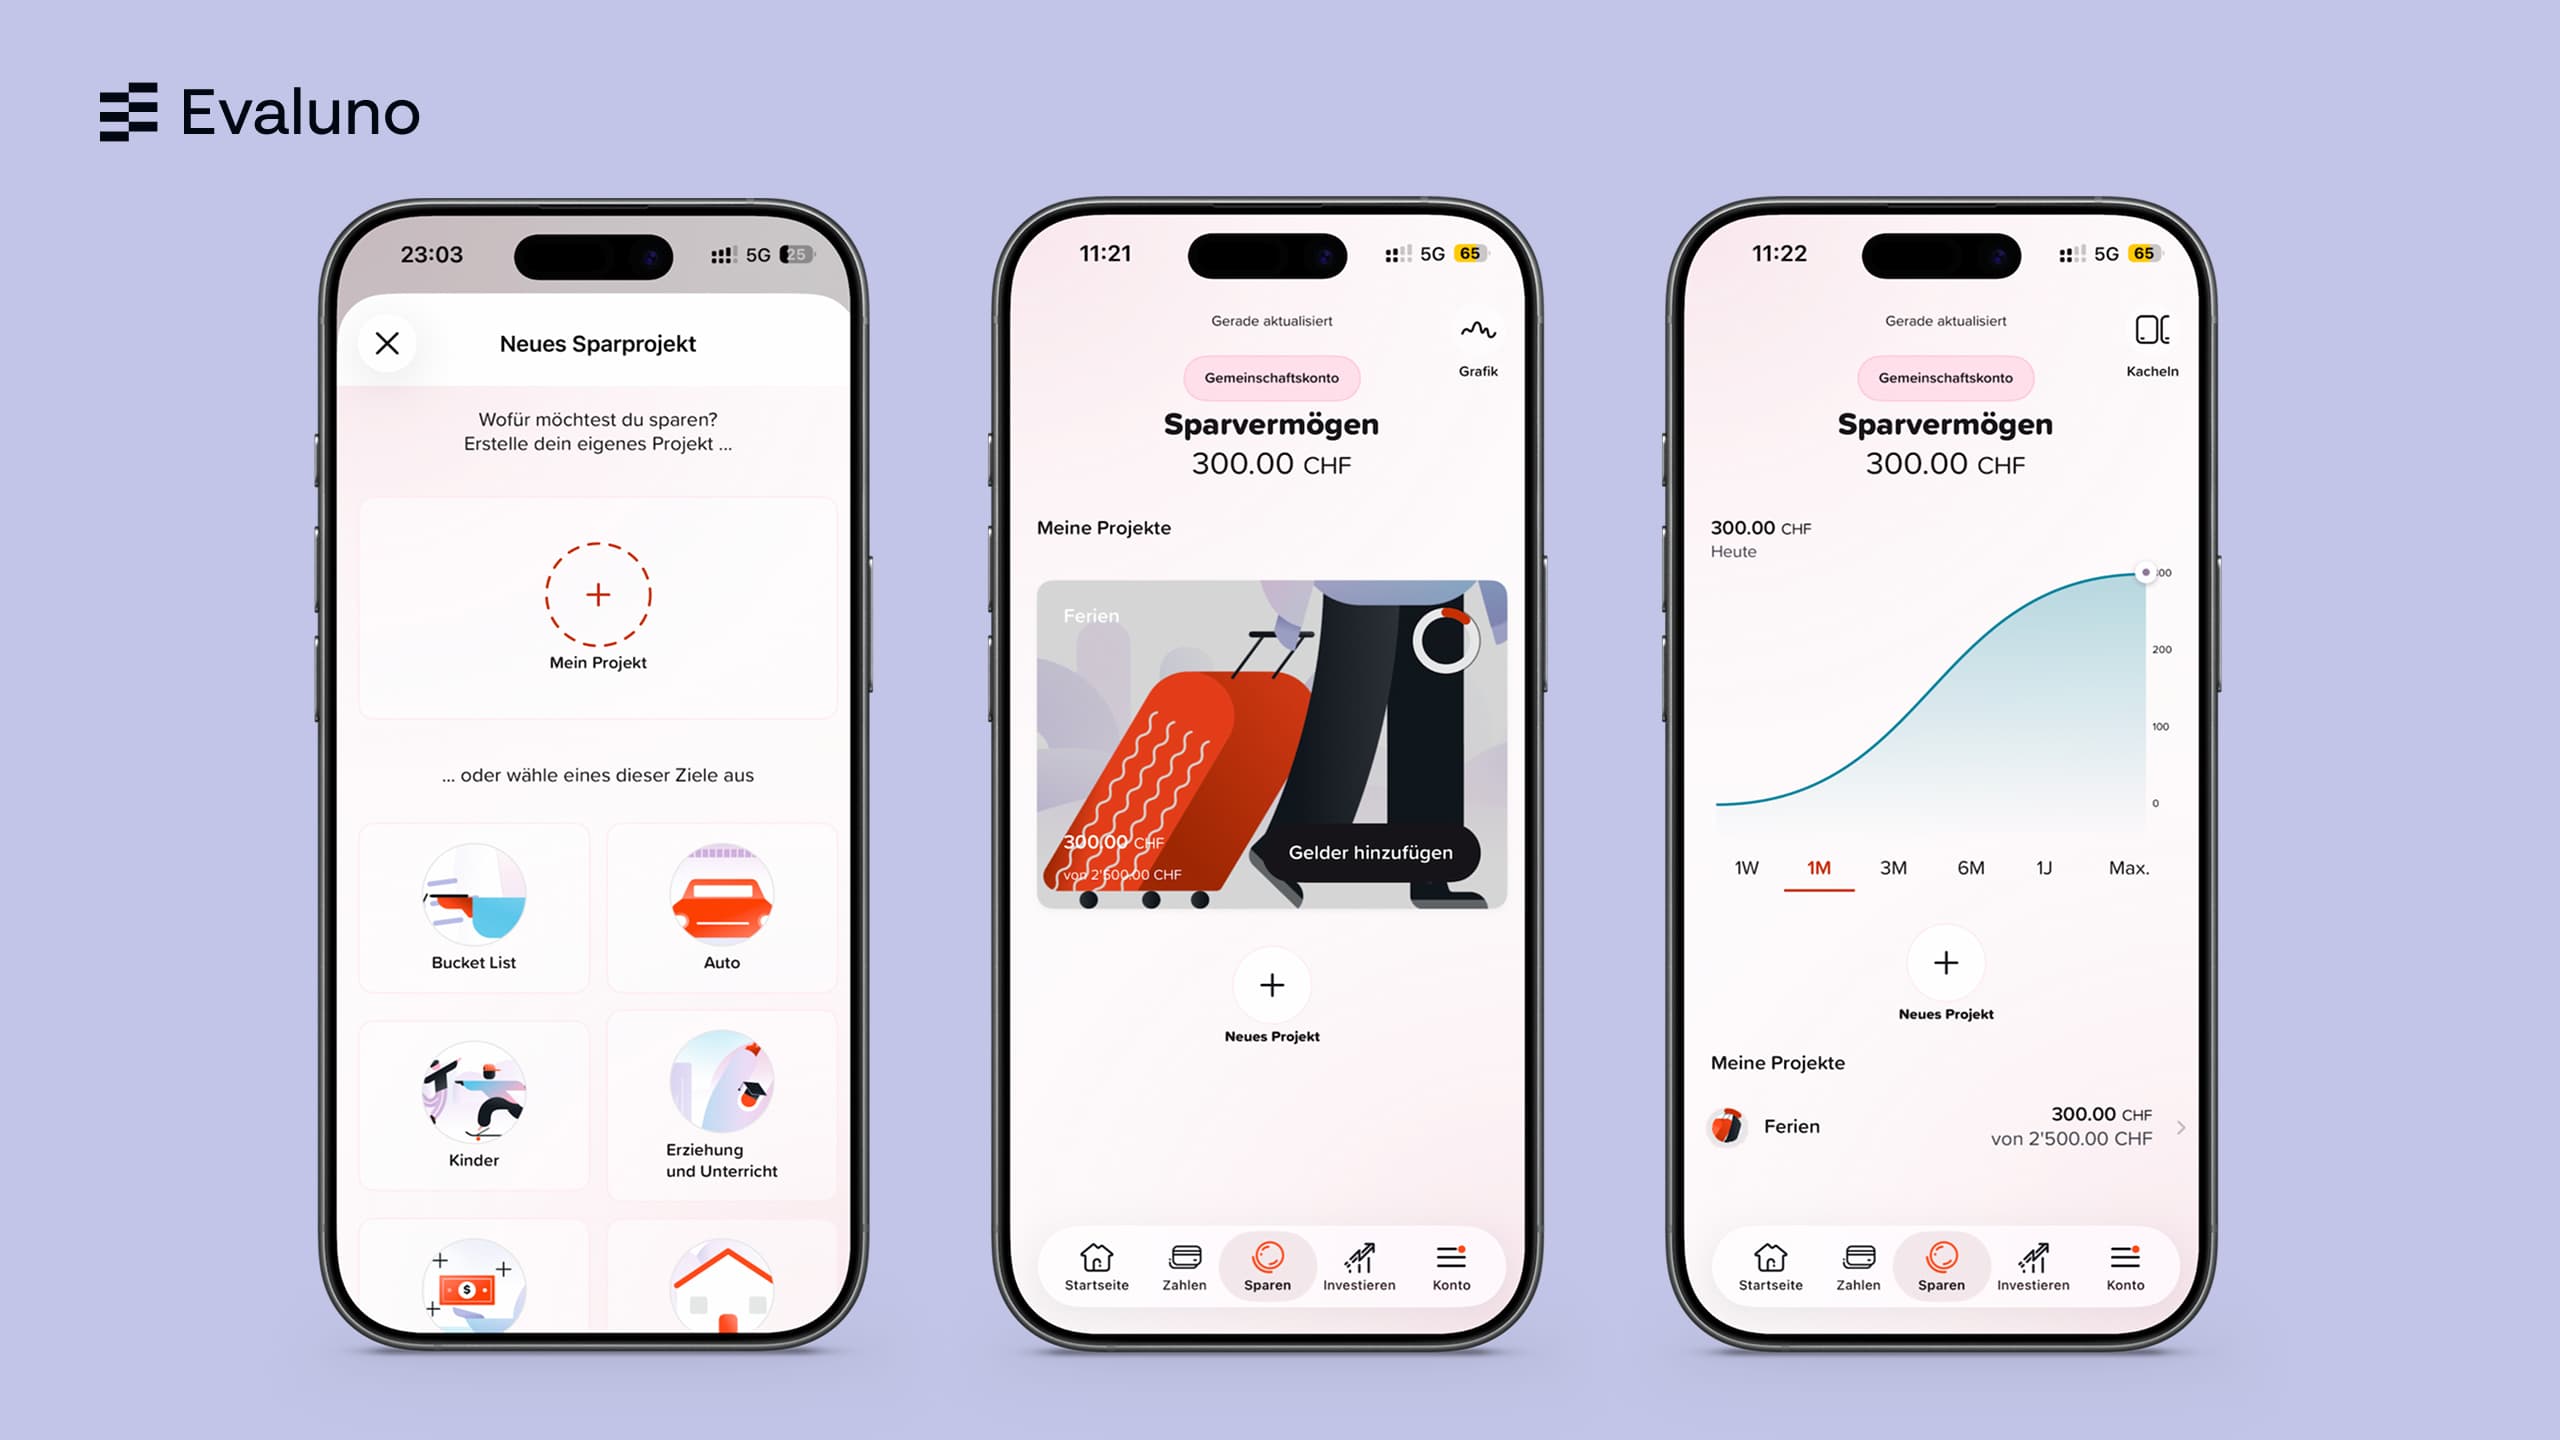
With the Yuh joint account you can set up an unlimited number of shared savings goals free of charge. The best part: both of you see the progress in real time. Whether for the wedding, the move, the sofa or the next big holiday, a useful and motivating way to work towards the next savings goal.
Multi-currency: several currencies in one account
Yuh&Me is multi-currency capable: francs, euros, dollars and other currencies sit side by side in the same account. For everyday life in Switzerland you can ignore this; in the vast majority of cases rent, shopping and eBill payments run in francs. It becomes useful if you do not want to be exposed to exchange rate fluctuations, e.g. for holiday money or for larger purchases in online shops. Important: exchanging currency costs 0.95 % on the interbank rate.
Investing together is not possible (yet)
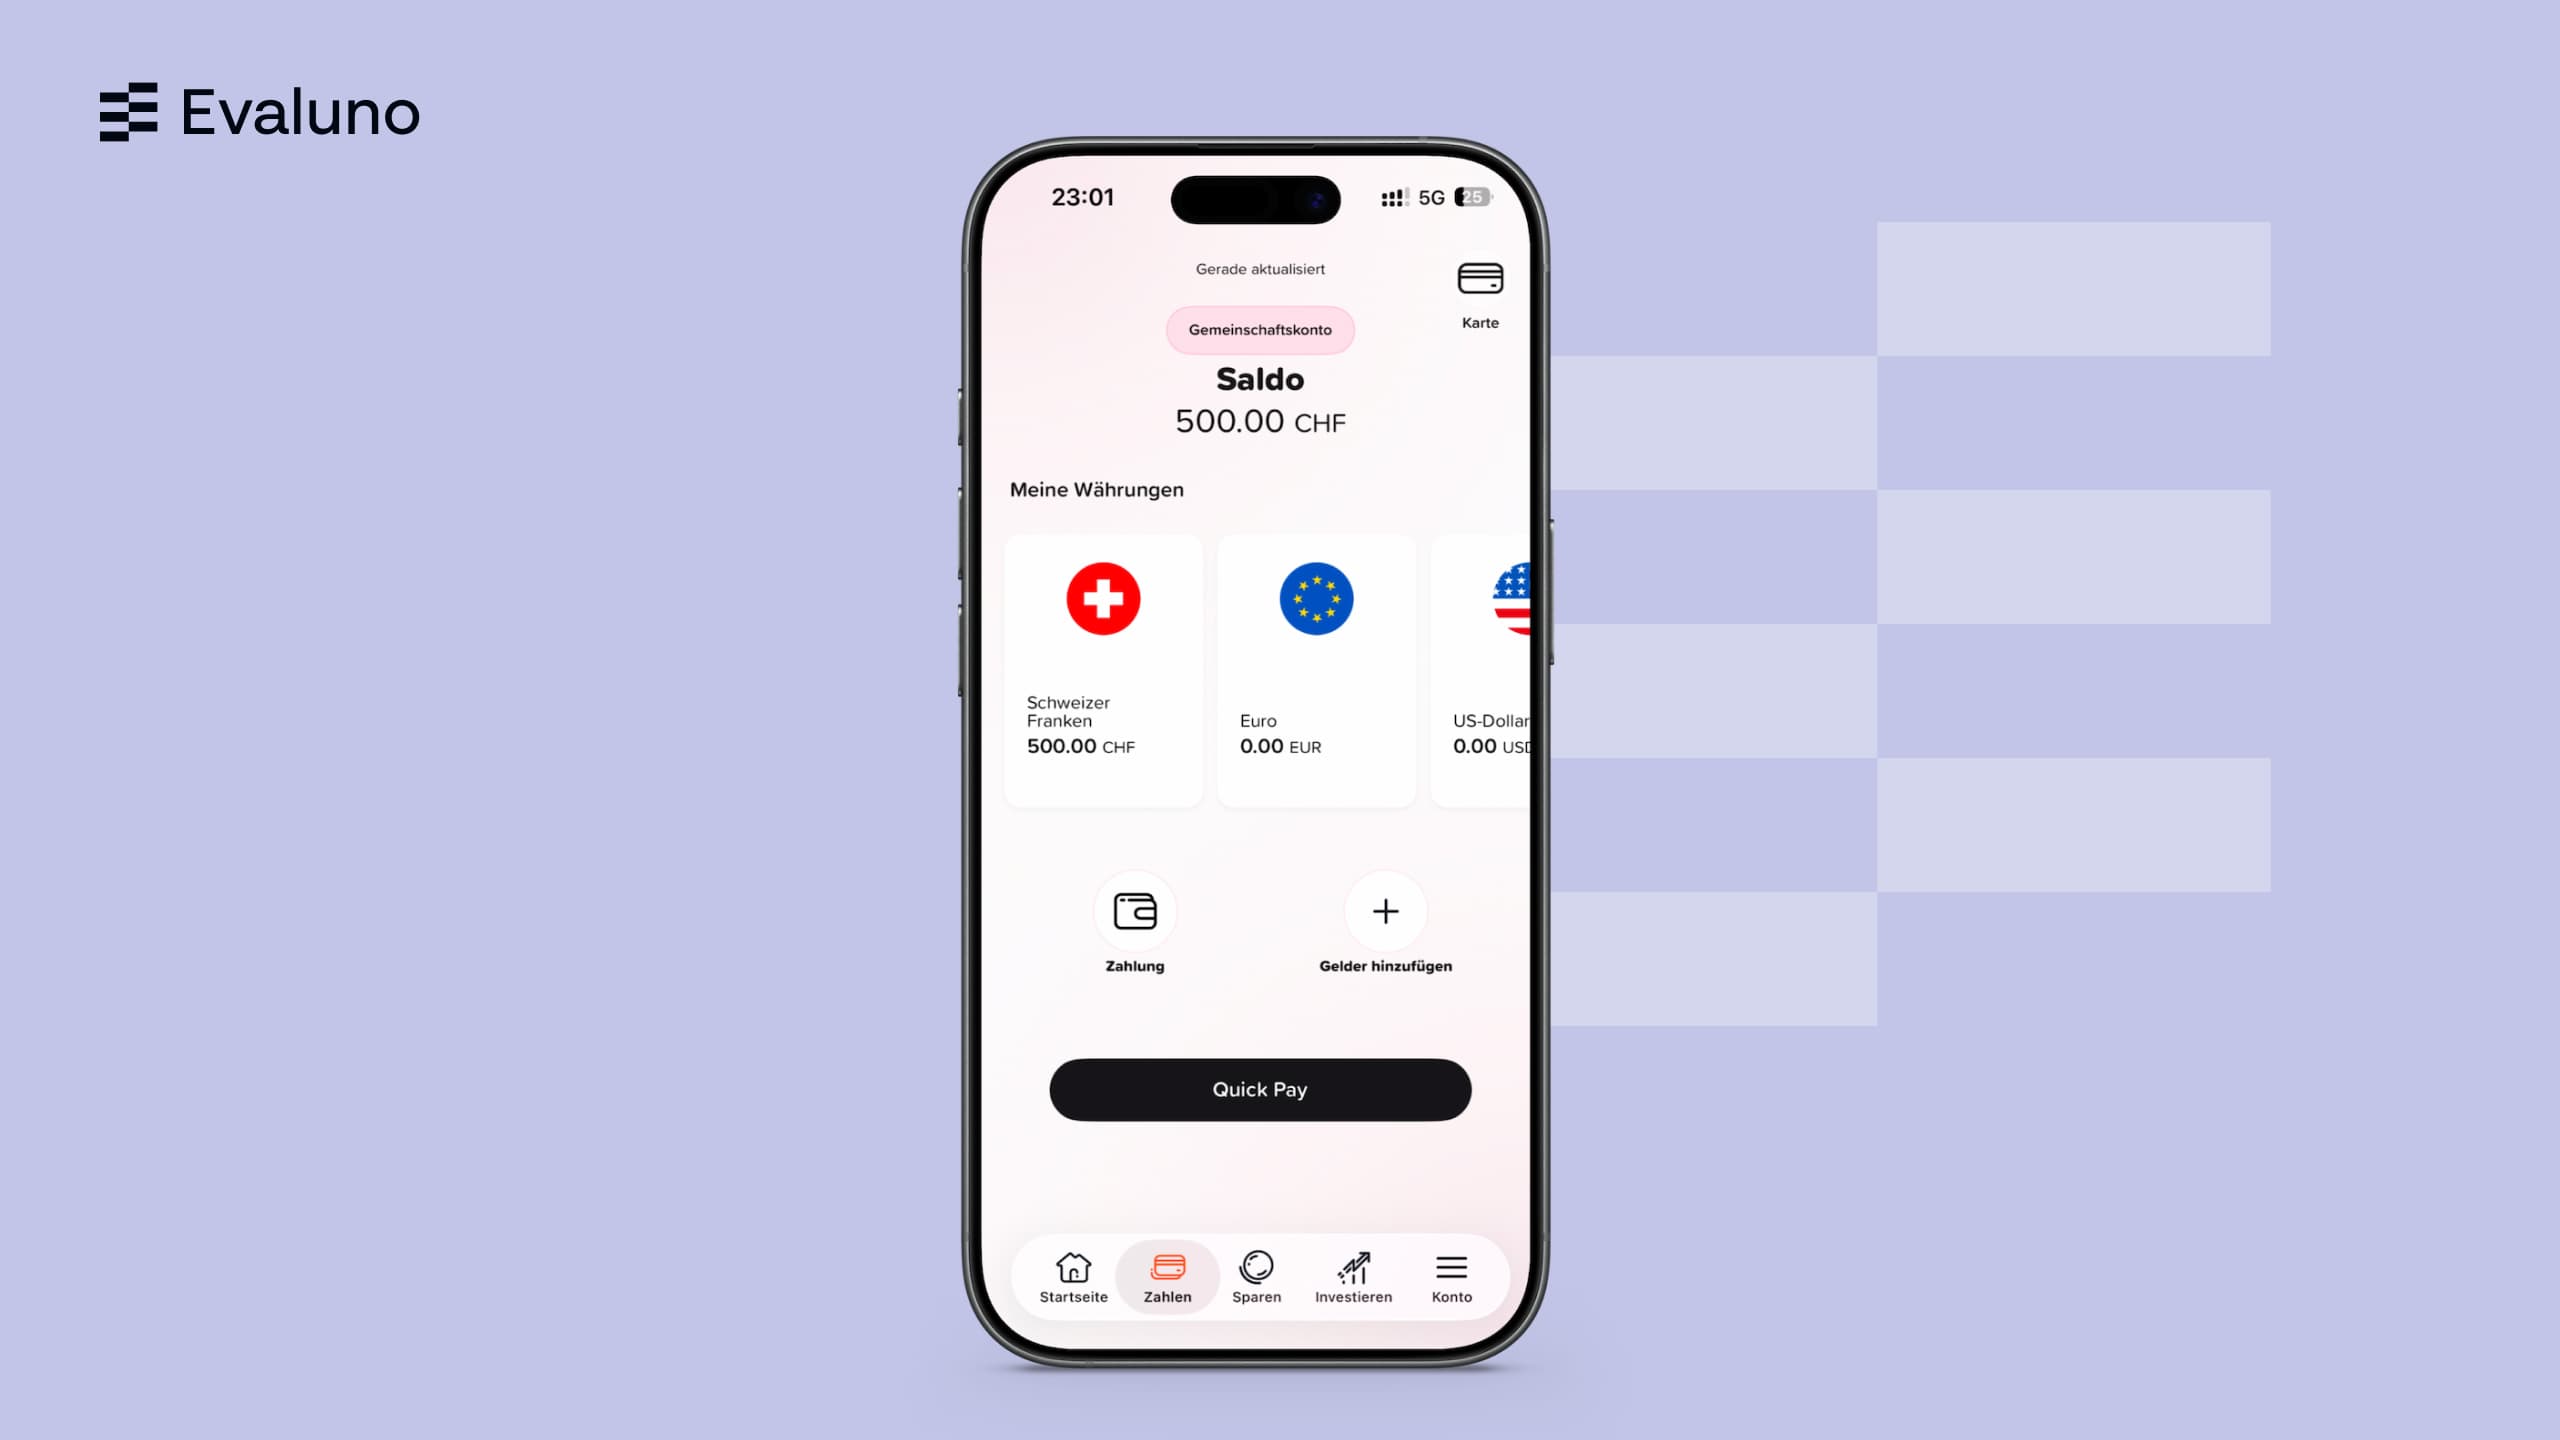
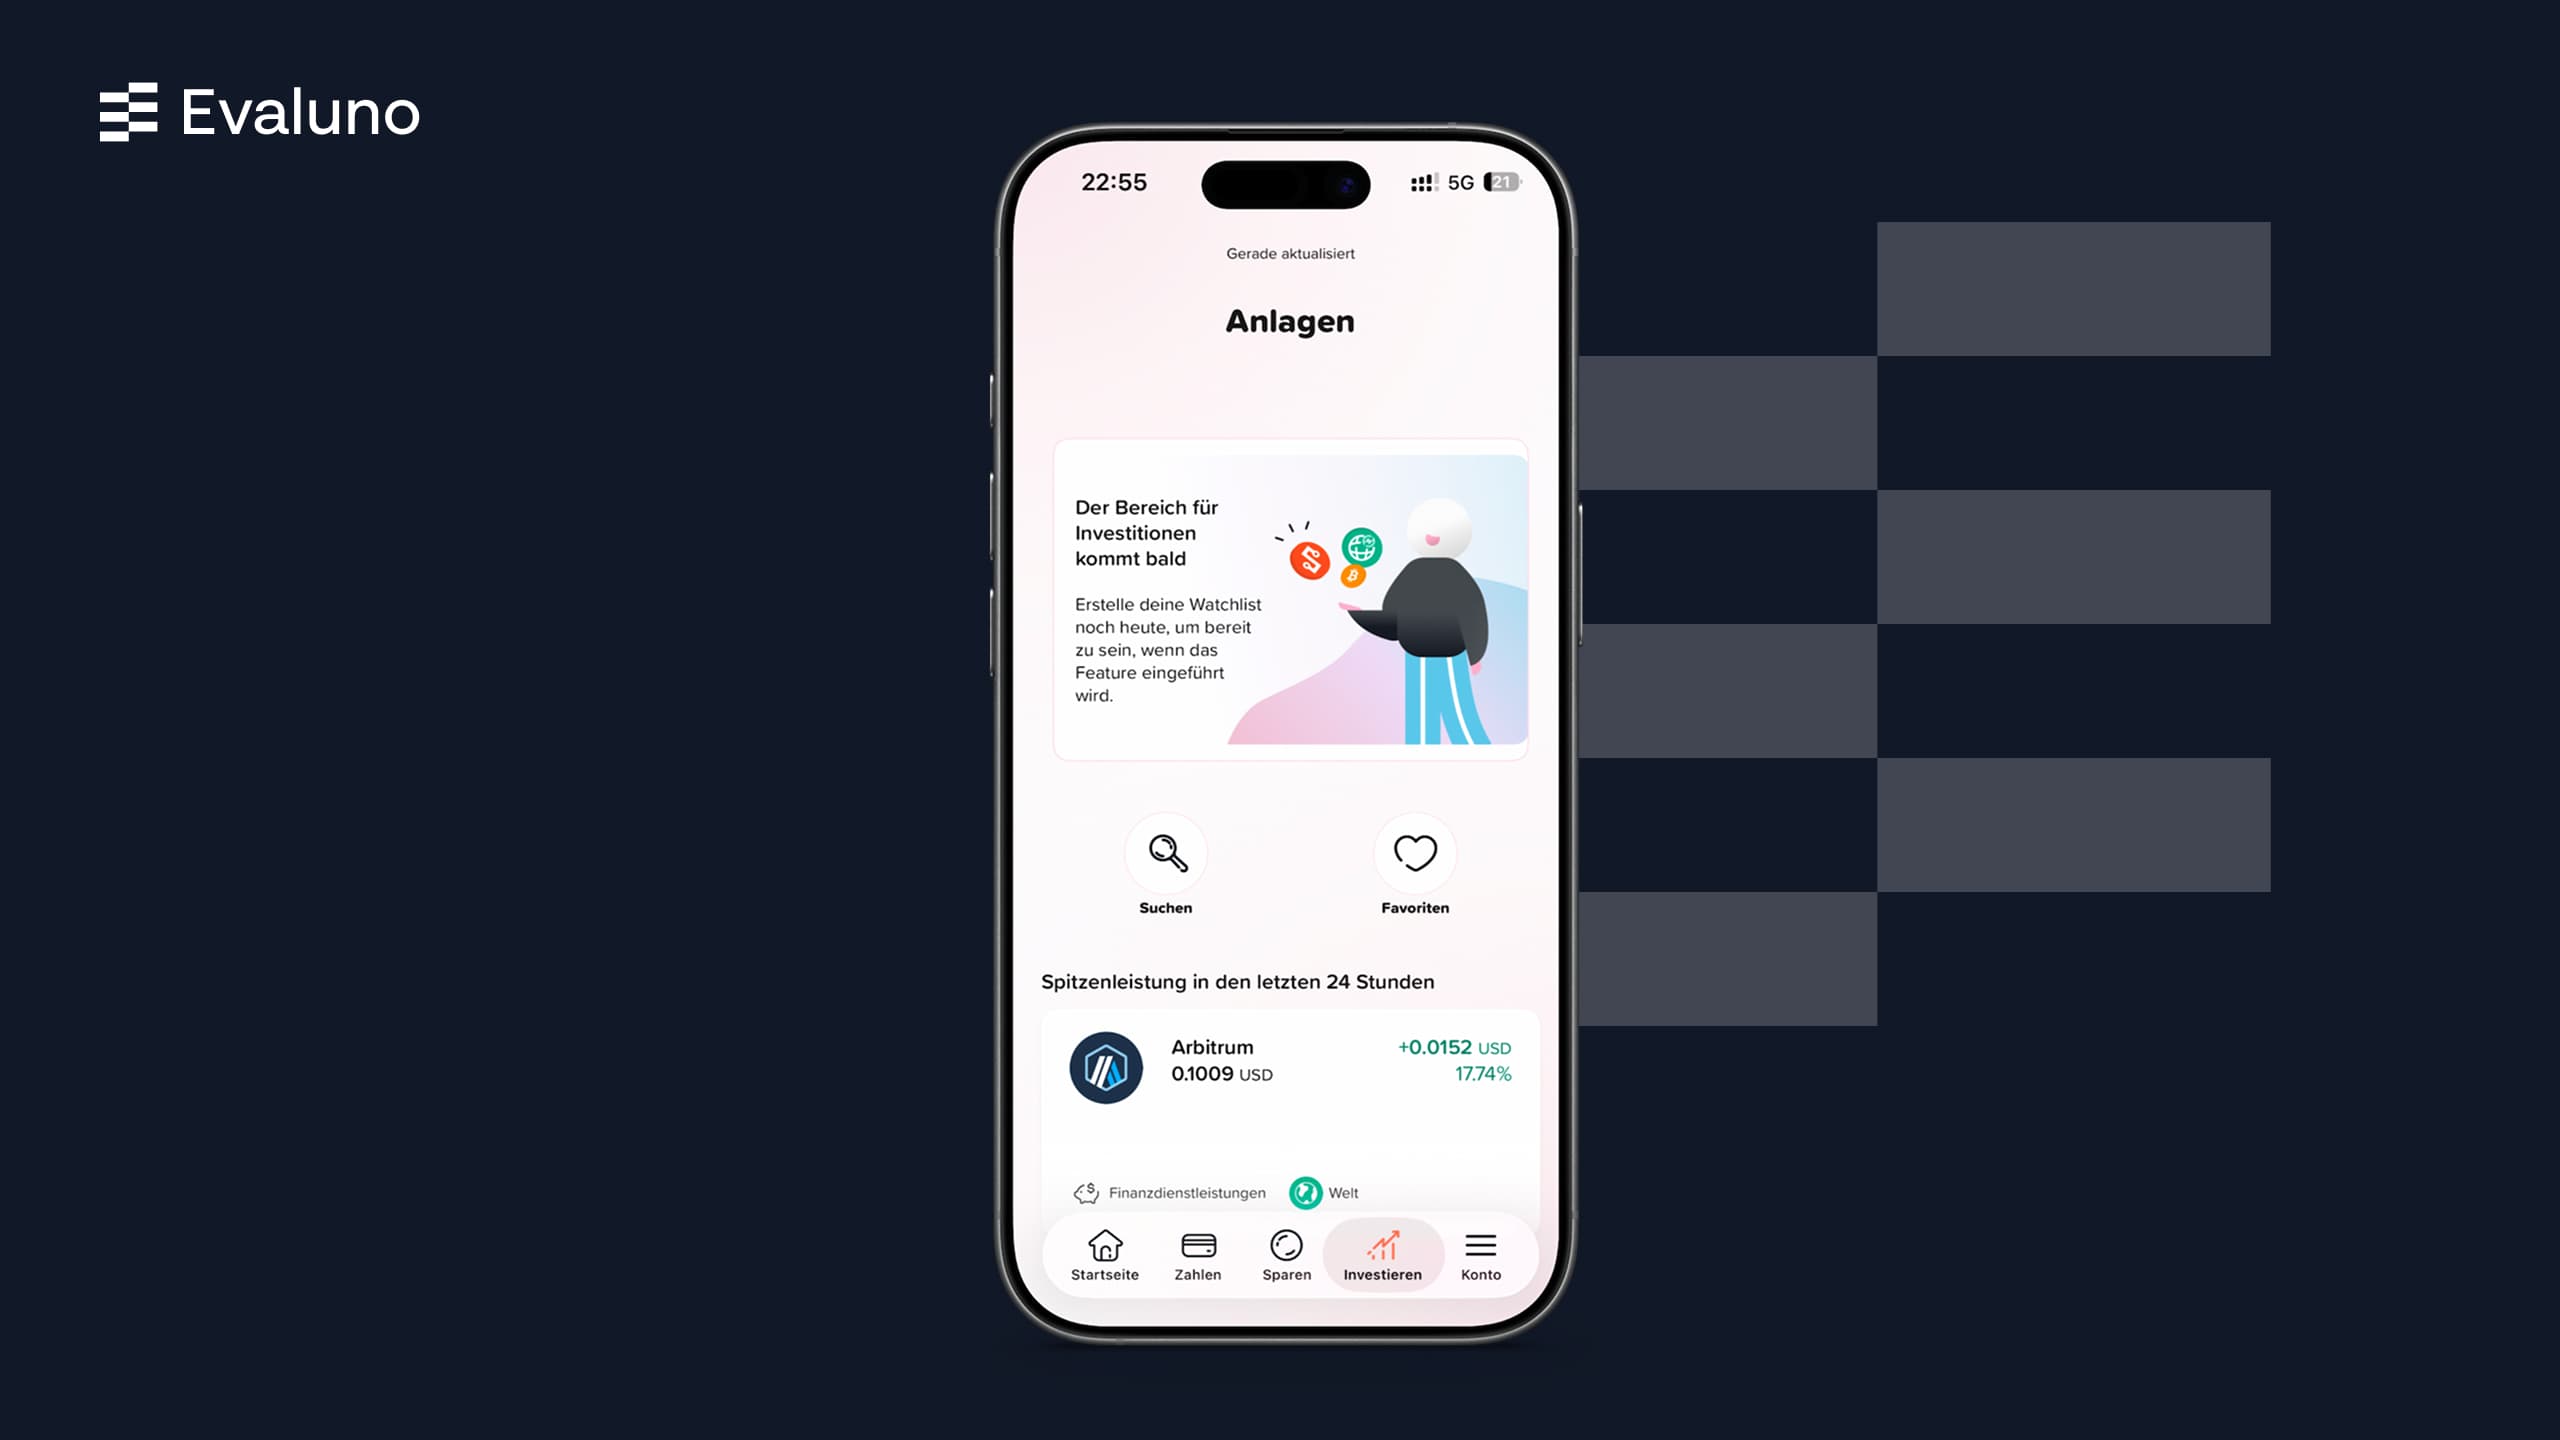
Yuh’s investment area is locked for the joint account. Investing currently only works via the personal accounts. In the app, Yuh says “The Investments section is coming soon” and mentions that you can already create watchlists so you are ready when the feature is rolled out.
How do you open the Yuh joint account? Step by step
The whole opening process takes place in the app.
- Both of you first open a personal Yuh account: download the app and verify your identity via video or online identification. Anyone who already has a Yuh account skips this step.
By the way: the Yuh promo code applies to the personal account, and since both of you need one, it can be entered when opening both accounts. - One person starts the opening in the “Account” section and answers questions about the relationship and intended use. The second person can then be invited.
- The second person receives an invitation and accepts it in their own app.
- Both sign the contract digitally.
- Yuh checks the details and opens the account. The joint account then appears in both apps next to the personal account. In the case of the Evaluno editor, opening took three days.
You can follow the progress directly in the Yuh app under “Settings”, in the “Joint account” menu item.
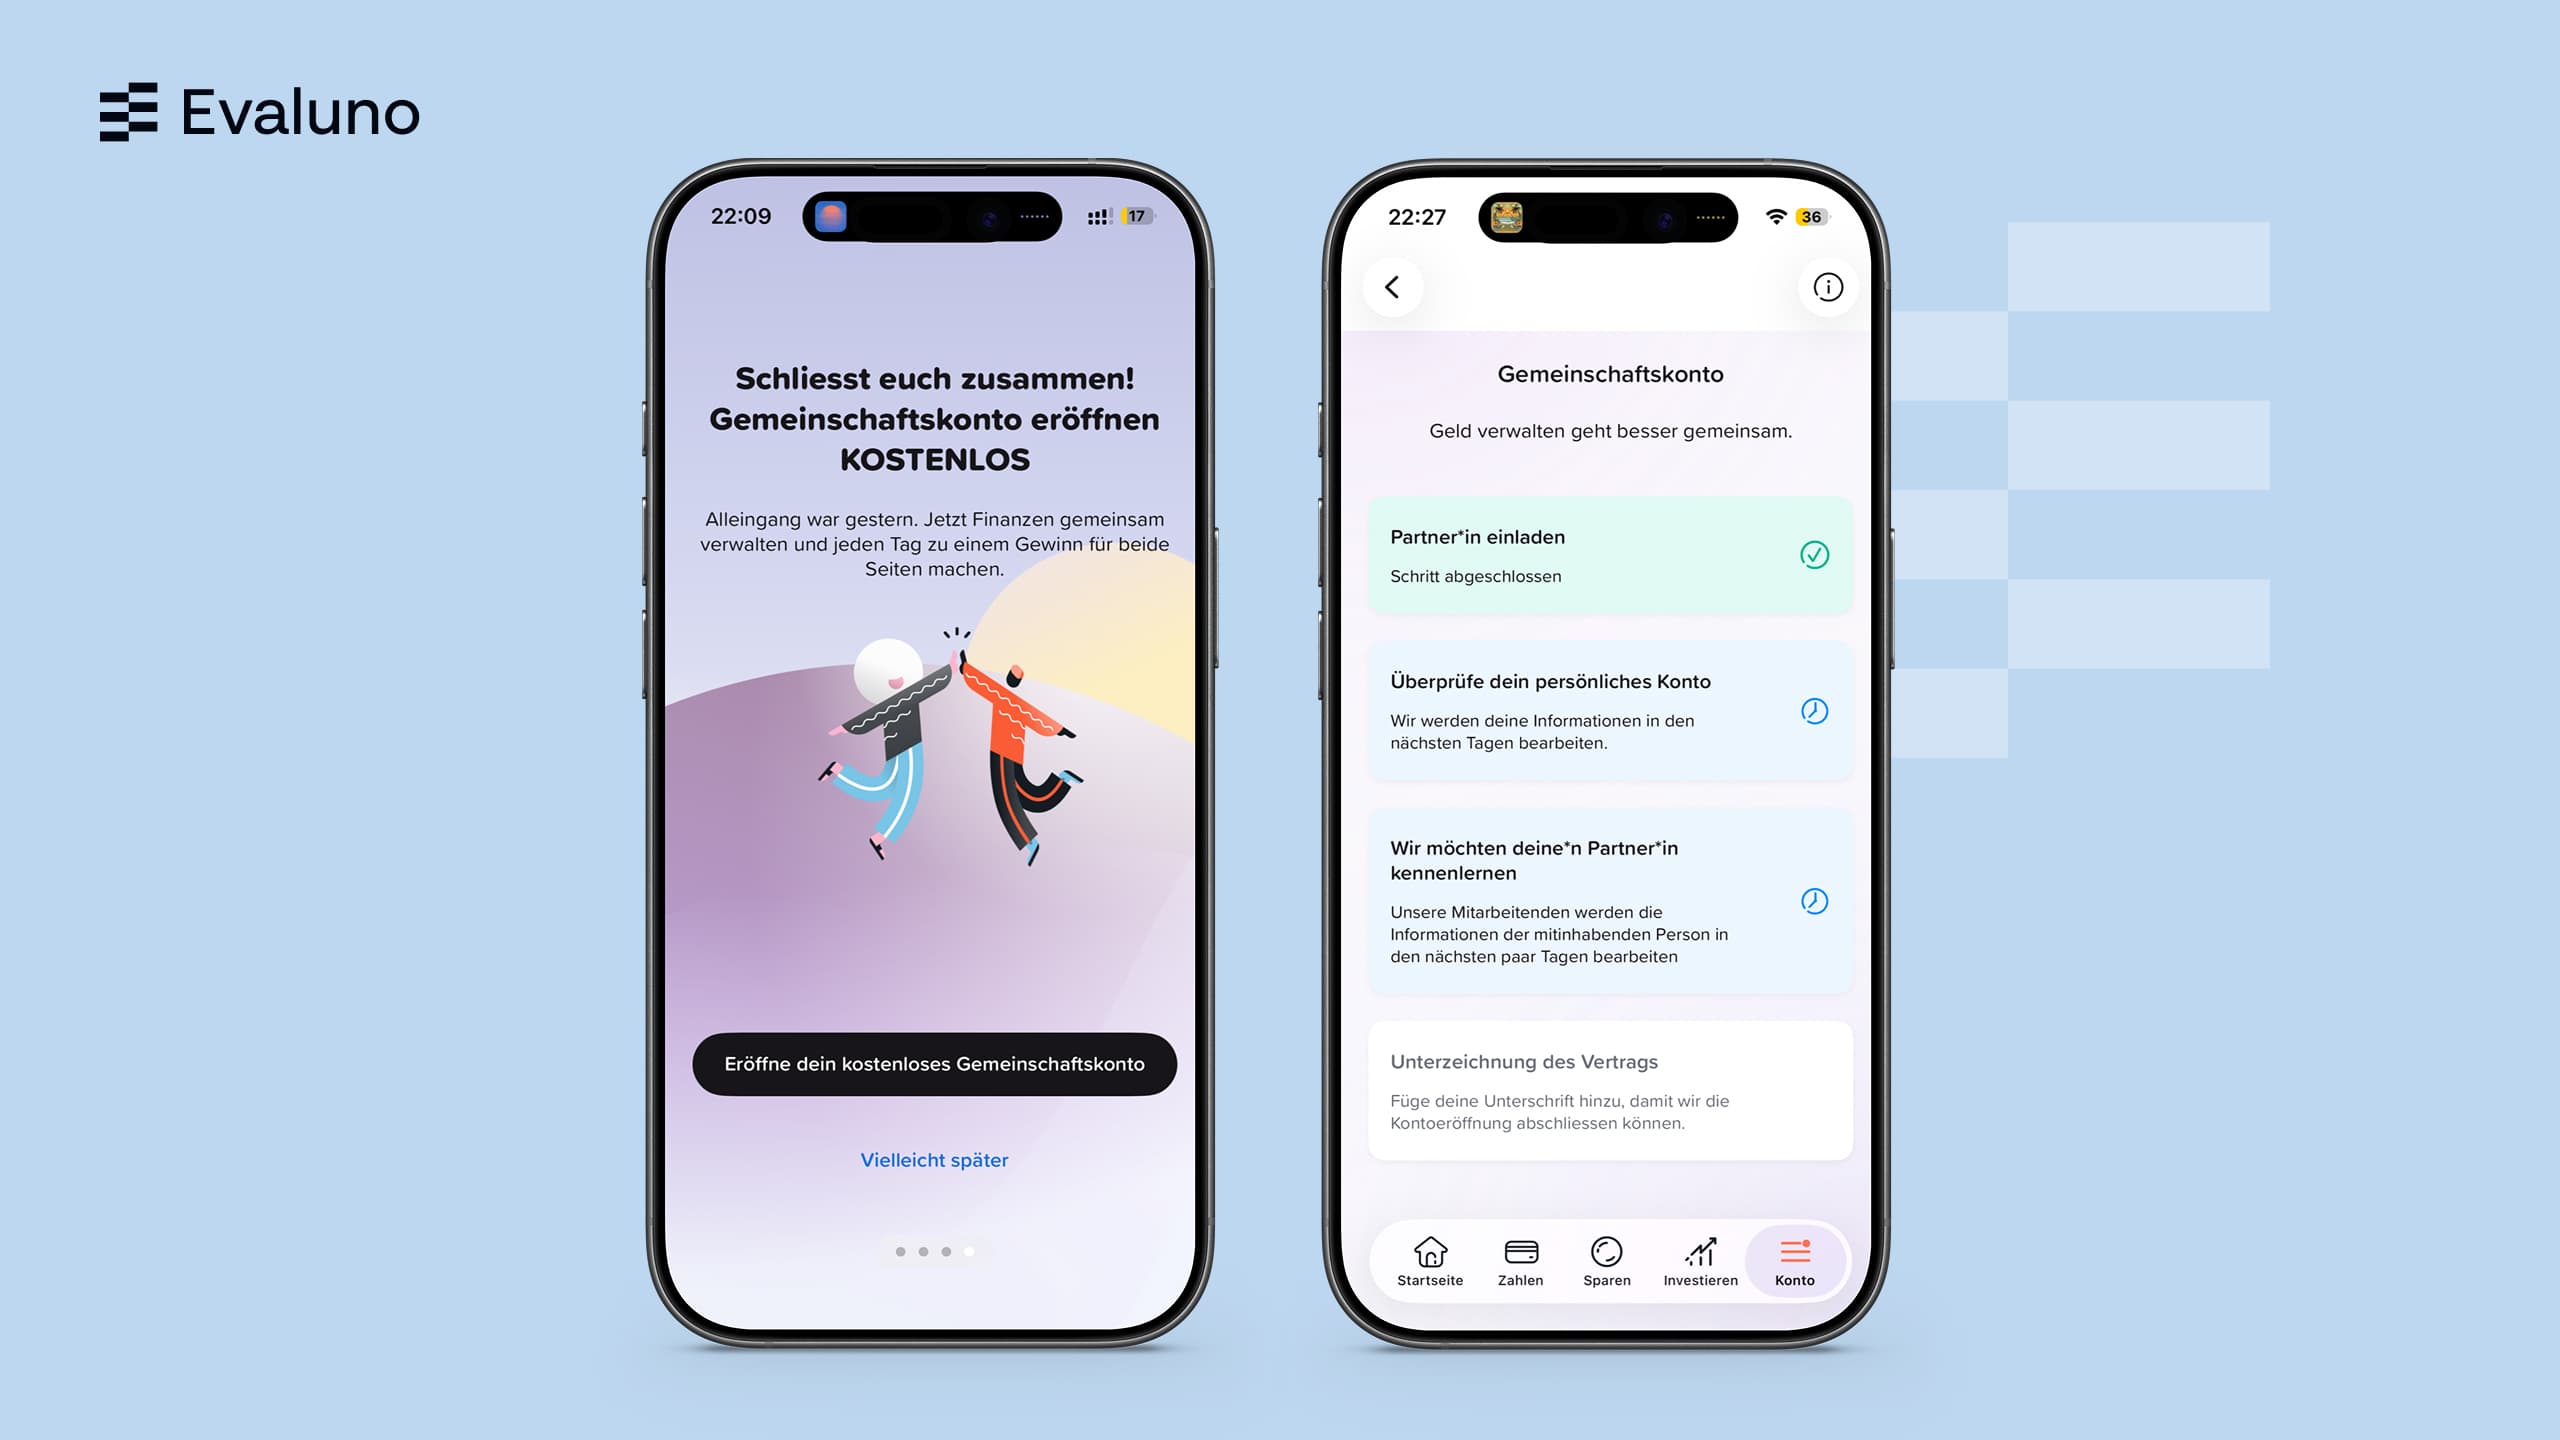
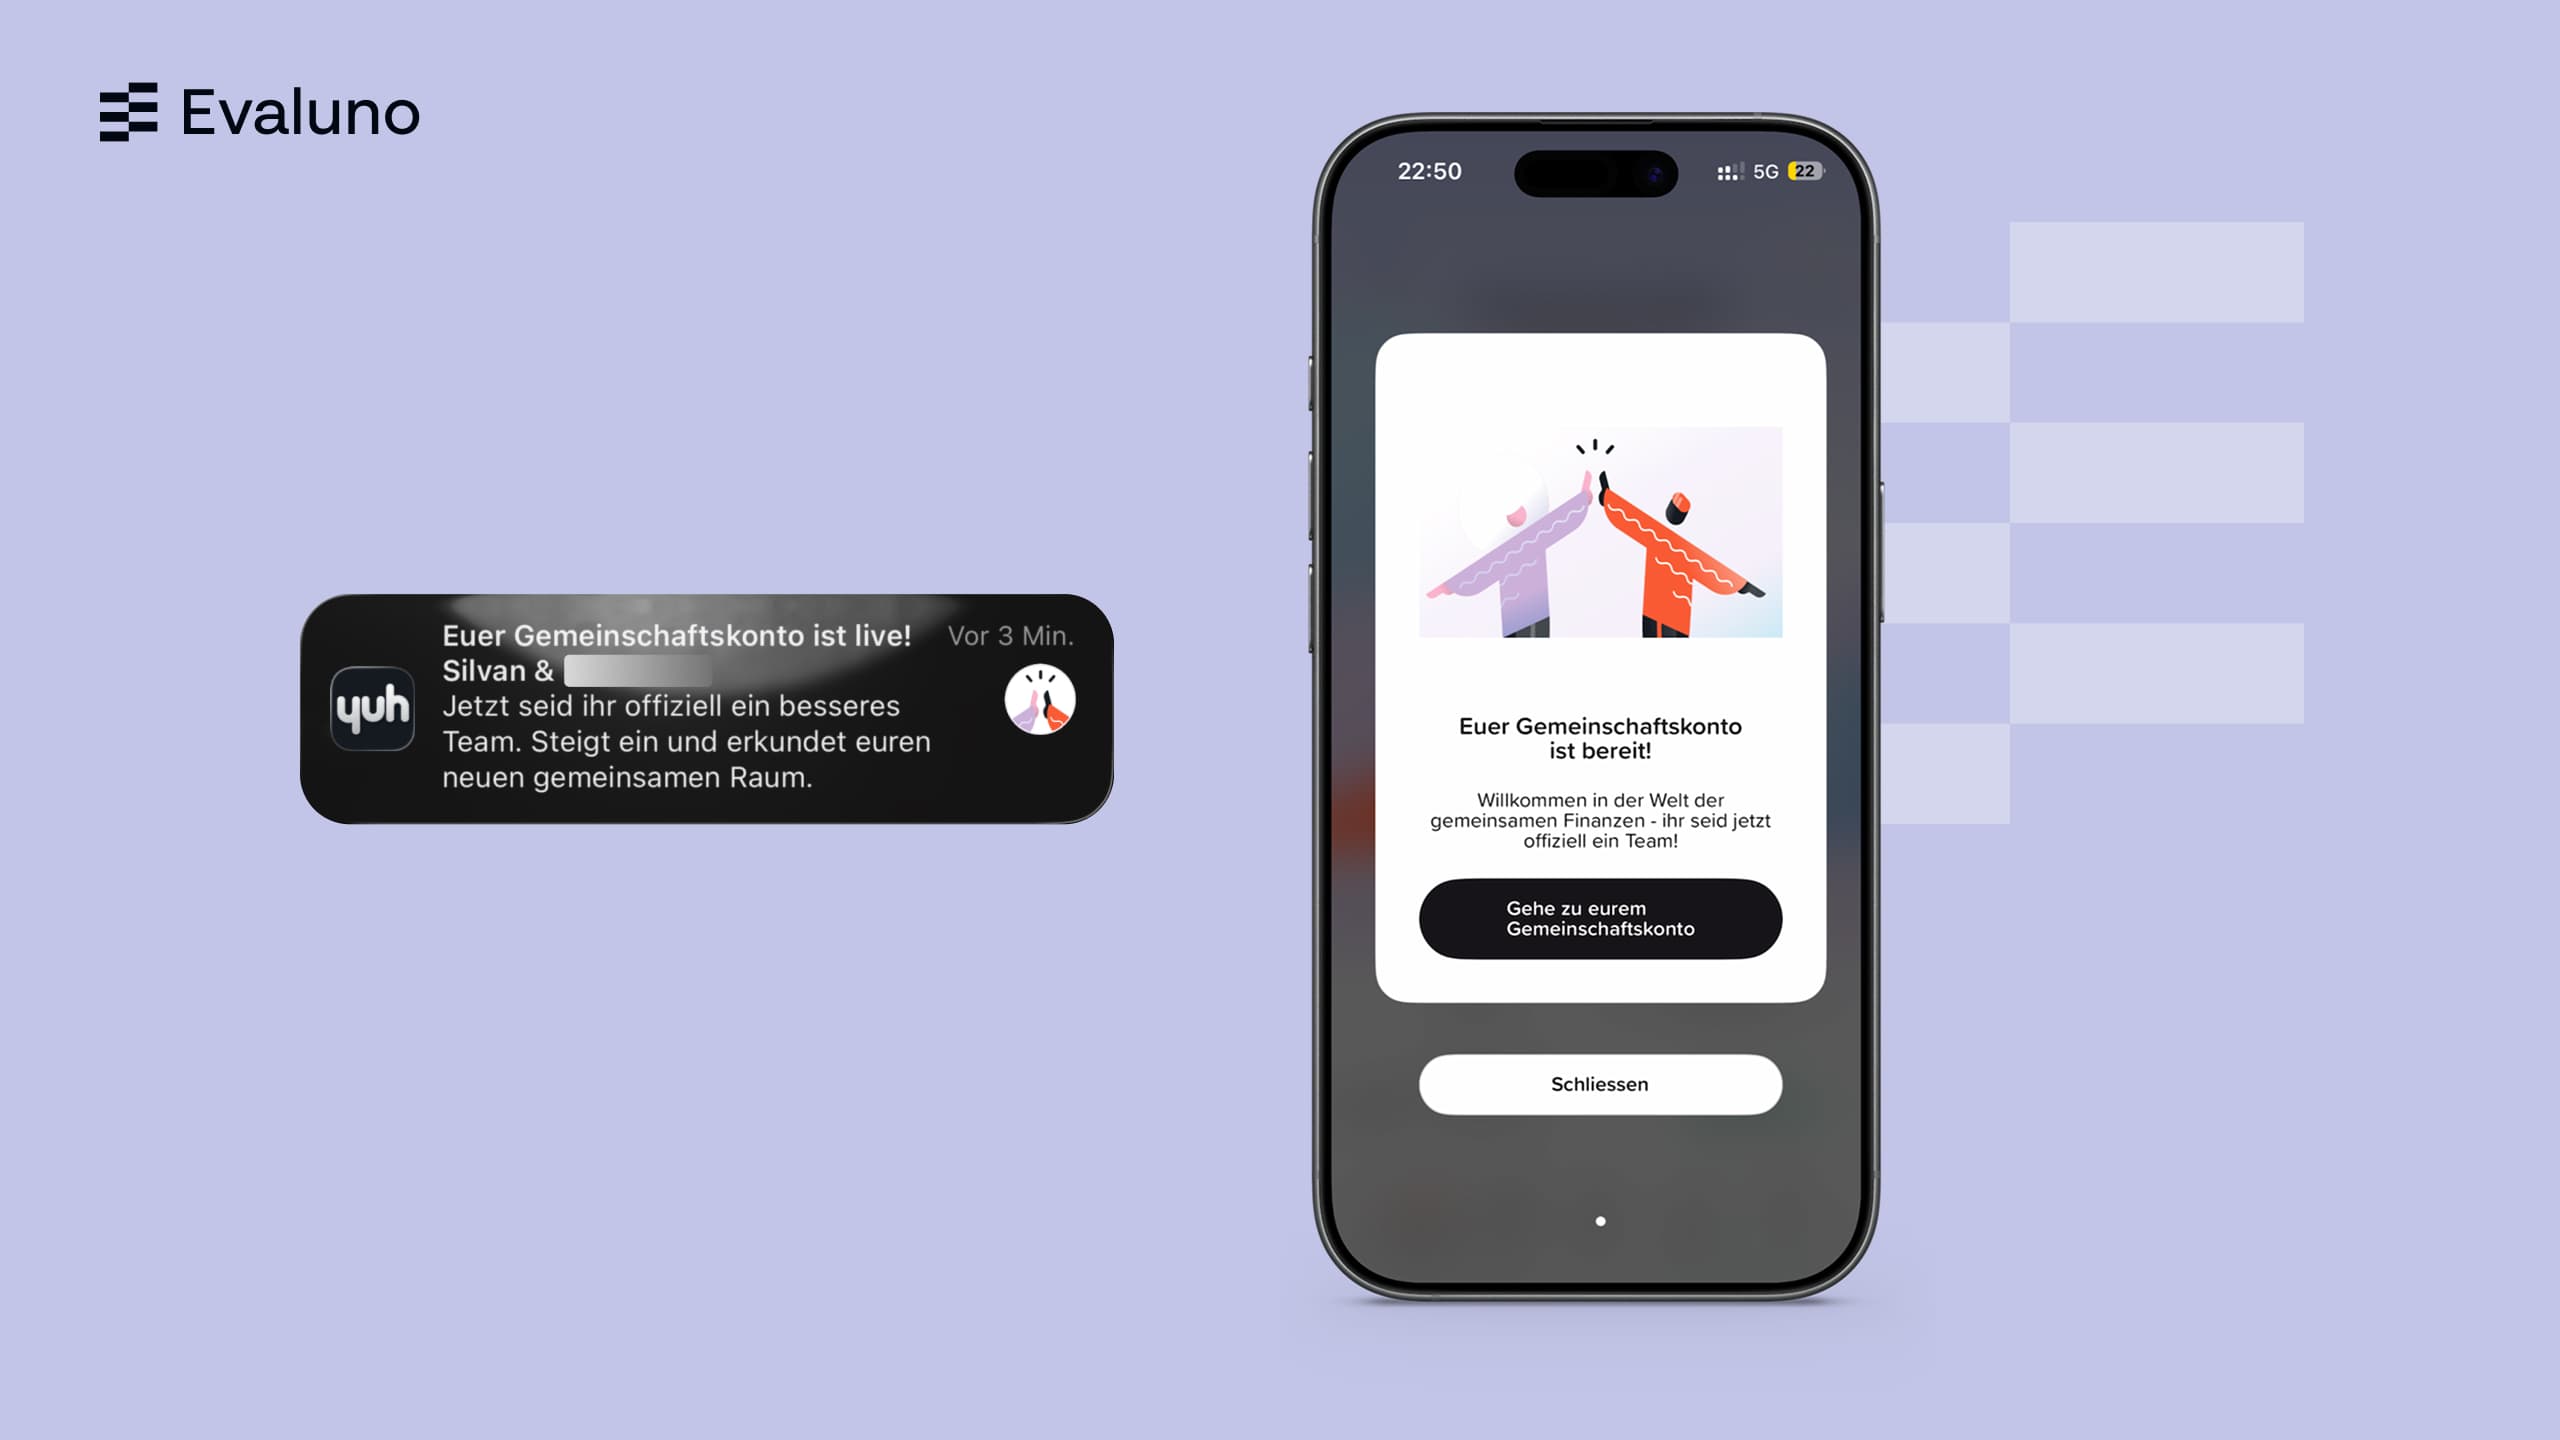
As soon as the account has been opened, you receive a push notification and an email. Straight after that, both of you have a virtual Mastercard that works immediately with Apple Pay, Google Pay or Samsung Pay. Each person orders their physical card separately in the app, if needed.
What does the Yuh joint account cost?
Account management for the Yuh joint account is free with no further conditions. The two personal Yuh accounts you need as a prerequisite are free as well.
Certain services do incur costs, though. You will find the details of the costs for the Yuh joint account in the price overview.
Fees for the Yuh joint account
| Service | Cost |
|---|---|
| Account fee joint account | CHF 0 |
| Account fee personal accounts | CHF 0 |
| Debit card fees | CHF 0 |
| Transfers within Switzerland | CHF 0 |
| Cash withdrawal in Switzerland | 1 per week free, then CHF 1.90 |
| Cash withdrawal abroad | CHF 4.90 per withdrawal |
| Currency exchange | 0.95 % on the interbank rate |
Source: Yuh price overview, retrieved on 19.08.2026.
The three places where Yuh&Me does cost money
So where does the Yuh joint account cost money after all? In exactly three places. Depending on how you use it, these cost items matter more or less to you.
Cash in Switzerland
One withdrawal per calendar week is free. The catch is in the word “calendar week”: the counter resets to zero every Monday. Anyone withdrawing on Sunday and Monday pays nothing; anyone withdrawing on Monday and Tuesday pays CHF 1.90 for the second withdrawal. For occasional withdrawers that is irrelevant. But anyone who goes to the ATM twice a week out of habit racks up around CHF 99 per year.
Foreign currency transactions
The 0.95 % markup applies to card payments in foreign currency, in each case on the interbank rate, i.e. the reference rate. To put that in perspective: two weeks in Italy with CHF 2'000 in card payments cost you CHF 19 in markup.
Cash withdrawals abroad
For each withdrawal abroad you pay CHF 4.90 with the Yuh joint account. If you regularly withdraw money abroad, that can add up. If you never or rarely use the card abroad, it matters less.
Who is the Yuh&Me joint account suitable for?
Yuh&Me suits two people who want to keep their shared expenses cleanly separate from their individual spending and handle their banking entirely by app. The type of relationship does not matter: couple, two-person flatshare, siblings or a parent with an adult child, Yuh allows all of these.
Who can open a Yuh joint account?
Three conditions, all three mandatory:
- Both people are at least 18 years old
- Both live in Switzerland (a shared address is not required)
- Both people have their own Yuh personal account
Conditions that play no role: no marriage, no registered partnership, no proof of the type of relationship, no minimum incoming payments, no minimum balance. Yuh does ask about the relationship when you open the account, but only for information, not as a condition.
Who is Yuh&Me suitable for?
Yuh&Me is a good fit for:
- couples who run their shared fixed costs and everyday expenses through a separate account and do not want to pay anything for it
- two-person flatshares, siblings and friends; relationship status is irrelevant
- couples and other pairs without a shared address, for whom many other joint account providers are therefore not an option.
Who is Yuh&Me not suitable for?
Yuh&Me is less suitable for:
- groups of three or more (max. 2 people at Yuh)
- couples who want to invest together or hold a shared securities account
- households and groups with very high foreign currency turnover
- anyone who withdraws cash frequently. From two withdrawals a week, Yuh&Me costs around CHF 99 per year.
- anyone who wants personal advice in a branch.
Pros and cons of the Yuh joint account
Advantages
- Advantage: Free account management
- Advantage: Four free Mastercards (two physical, two virtual), including shipping
- Advantage: TWINT and eBill directly from the shared account
- Advantage: No shared address, no proof of marital status required
- Advantage: Clean separation of private and shared account in the same app
- Advantage: Fully digital opening, no branch appointment
- Advantage: Deposits protected up to CHF 100'000 (esisuisse)
Disadvantages
- Disadvantage: Exchange rate markup of 0.95 %, higher than at other providers
- Disadvantage: Only two account holders, not possible for three or more
- Disadvantage: 0 % interest on balance and savings projects
- Disadvantage: Only one free cash withdrawal per week
- Disadvantage: No branches
Frequently asked questions
Yes, account management costs CHF 0 per month, with no conditions. All four Mastercards, TWINT, eBill and the shared savings projects are free too. Fees only apply to cash withdrawals from the second one per calendar week (CHF 1.90), withdrawals abroad (CHF 4.90 per withdrawal) and currency exchange (0.95 %).
For a couple that pays only in francs and makes at most one cash withdrawal per week: CHF 0. With CHF 3'000 in foreign currency card payments and four withdrawals abroad, it comes to around CHF 48. For comparison: neon duo costs CHF 72 per year in basic fees alone, PostFinance CHF 60, UBS me CHF 180.
Two people who are both at least 18 years old, live in Switzerland and each have their own active Yuh personal account. Marital status does not matter: married couples, unmarried couples, siblings, friends and flatmates can all open a Yuh&Me account.
No. Yuh only requires that both people live in Switzerland, not at the same address. That makes Yuh&Me available to couples without a shared address, siblings in separate households and other pairs too.
Yuh officially calls the product “joint account”; there is no separate “Yuh partner account”. Partner account, couples account and household account are common synonyms; legally it is the same account with two equal account holders. The marketing name Yuh&Me does not appear in the app, where it is consistently called joint account.
Yuh is a brand of Swissquote Bank Ltd, a FINMA-supervised Swiss bank. The account balance is protected up to CHF 100'000 via esisuisse.
The Yuh promo code YUHEVALUNO applies to the personal Yuh account, not directly to Yuh&Me. Since both people need their own Yuh account for the joint account, the code can be entered when opening both accounts. Link: Yuh bonus code
Legal disclaimer
Evaluno does not provide investment, legal or tax advice and is no substitute for personal advice.