

frankly 3a at a glance
| Provider | Sparen 3 pension foundation of Zürcher Kantonalbank |
| On the market since | April 2020 |
| Costs per year | 0.43 to 0.47 % depending on the product |
| Investment products | 15 Swisscanto products (Sustainable, Responsible, Index) in 5 risk levels with 15 to 95 % equities |
| Number of accounts/strategies | up to 5 accounts, each with its own strategy |
| Access | App (iOS, Android) and web version |
| Languages | German, French and English |
| Assets under management | CHF 6.9 billion |
| Promo code | Evaluno35: CHF 35 credit on fees |
Data as of 30.10.2026. Sources: frankly app (screenshots from October and November 2026), frankly.ch (FAQ and product pages, accessed on 30.10.2026), Evaluno pillar 3a fund comparison (costs, data as of 30.9.2026) and App Store (languages, accessed on 16.11.2026). No guarantee.
What is frankly? ZKB’s pillar 3a
frankly is the digital pension solution of Zürcher Kantonalbank (ZKB) and has been on the market since April 2020. You use it to open and manage your pillar 3a via the app or in the web version on your computer.
frankly is a brand, not a separate company. Your contractual partner is ZKB’s Sparen 3 pension foundation. The investment products come from Swisscanto, ZKB’s fund management company. ZKB has existed for more than 150 years and has over one million customers.
frankly tested: our experience with a real 3a account
Evaluno tests frankly with a real 3a account that has been paid into since 2024. The result: the app is simple and clear, the products are solid, and the price is attractive.
Test result at a glance
| Criterion | Rating | Reason |
|---|---|---|
| Costs | very good | Inexpensive compared with the market as a whole, with only a few cheaper providers: 0.43 to 0.47 % on invested money, uninvested money in the 3a account is fee-free |
| Investment offering | very good | Wide choice of strategies with up to 95 % equities, including sustainable options |
| Returns | very good | Thanks to low fees and solid Swisscanto funds, the frankly products have delivered very good returns so far |
| App and usability | very good | Simple and clear, also in the browser; strategy switch directly in the app |
| Account opening | very good | Simple and quick: 100 % digital with ID scan |
How Evaluno tests
The basis is an ordinary customer account at frankly: opened privately, paid into with the tester’s own money and not provided by frankly. Fees, interest rates and products come from the app (screenshots from October and November 2026) and from frankly.ch. Evaluno compares costs and returns with over 350 pillar 3a products (data as of 30 September 2026). Evaluno rates all 3a providers against the same five criteria.
frankly 3a fees: how much does frankly cost?
Depending on the product, frankly costs 0.43 to 0.47 % a year: the All-in fee of 0.43 % plus product costs. The All-in fee applies only to money invested in securities and is charged quarterly. Money you save in the 3a account without investing it remains fee-free.
Community discount: how the fee goes down
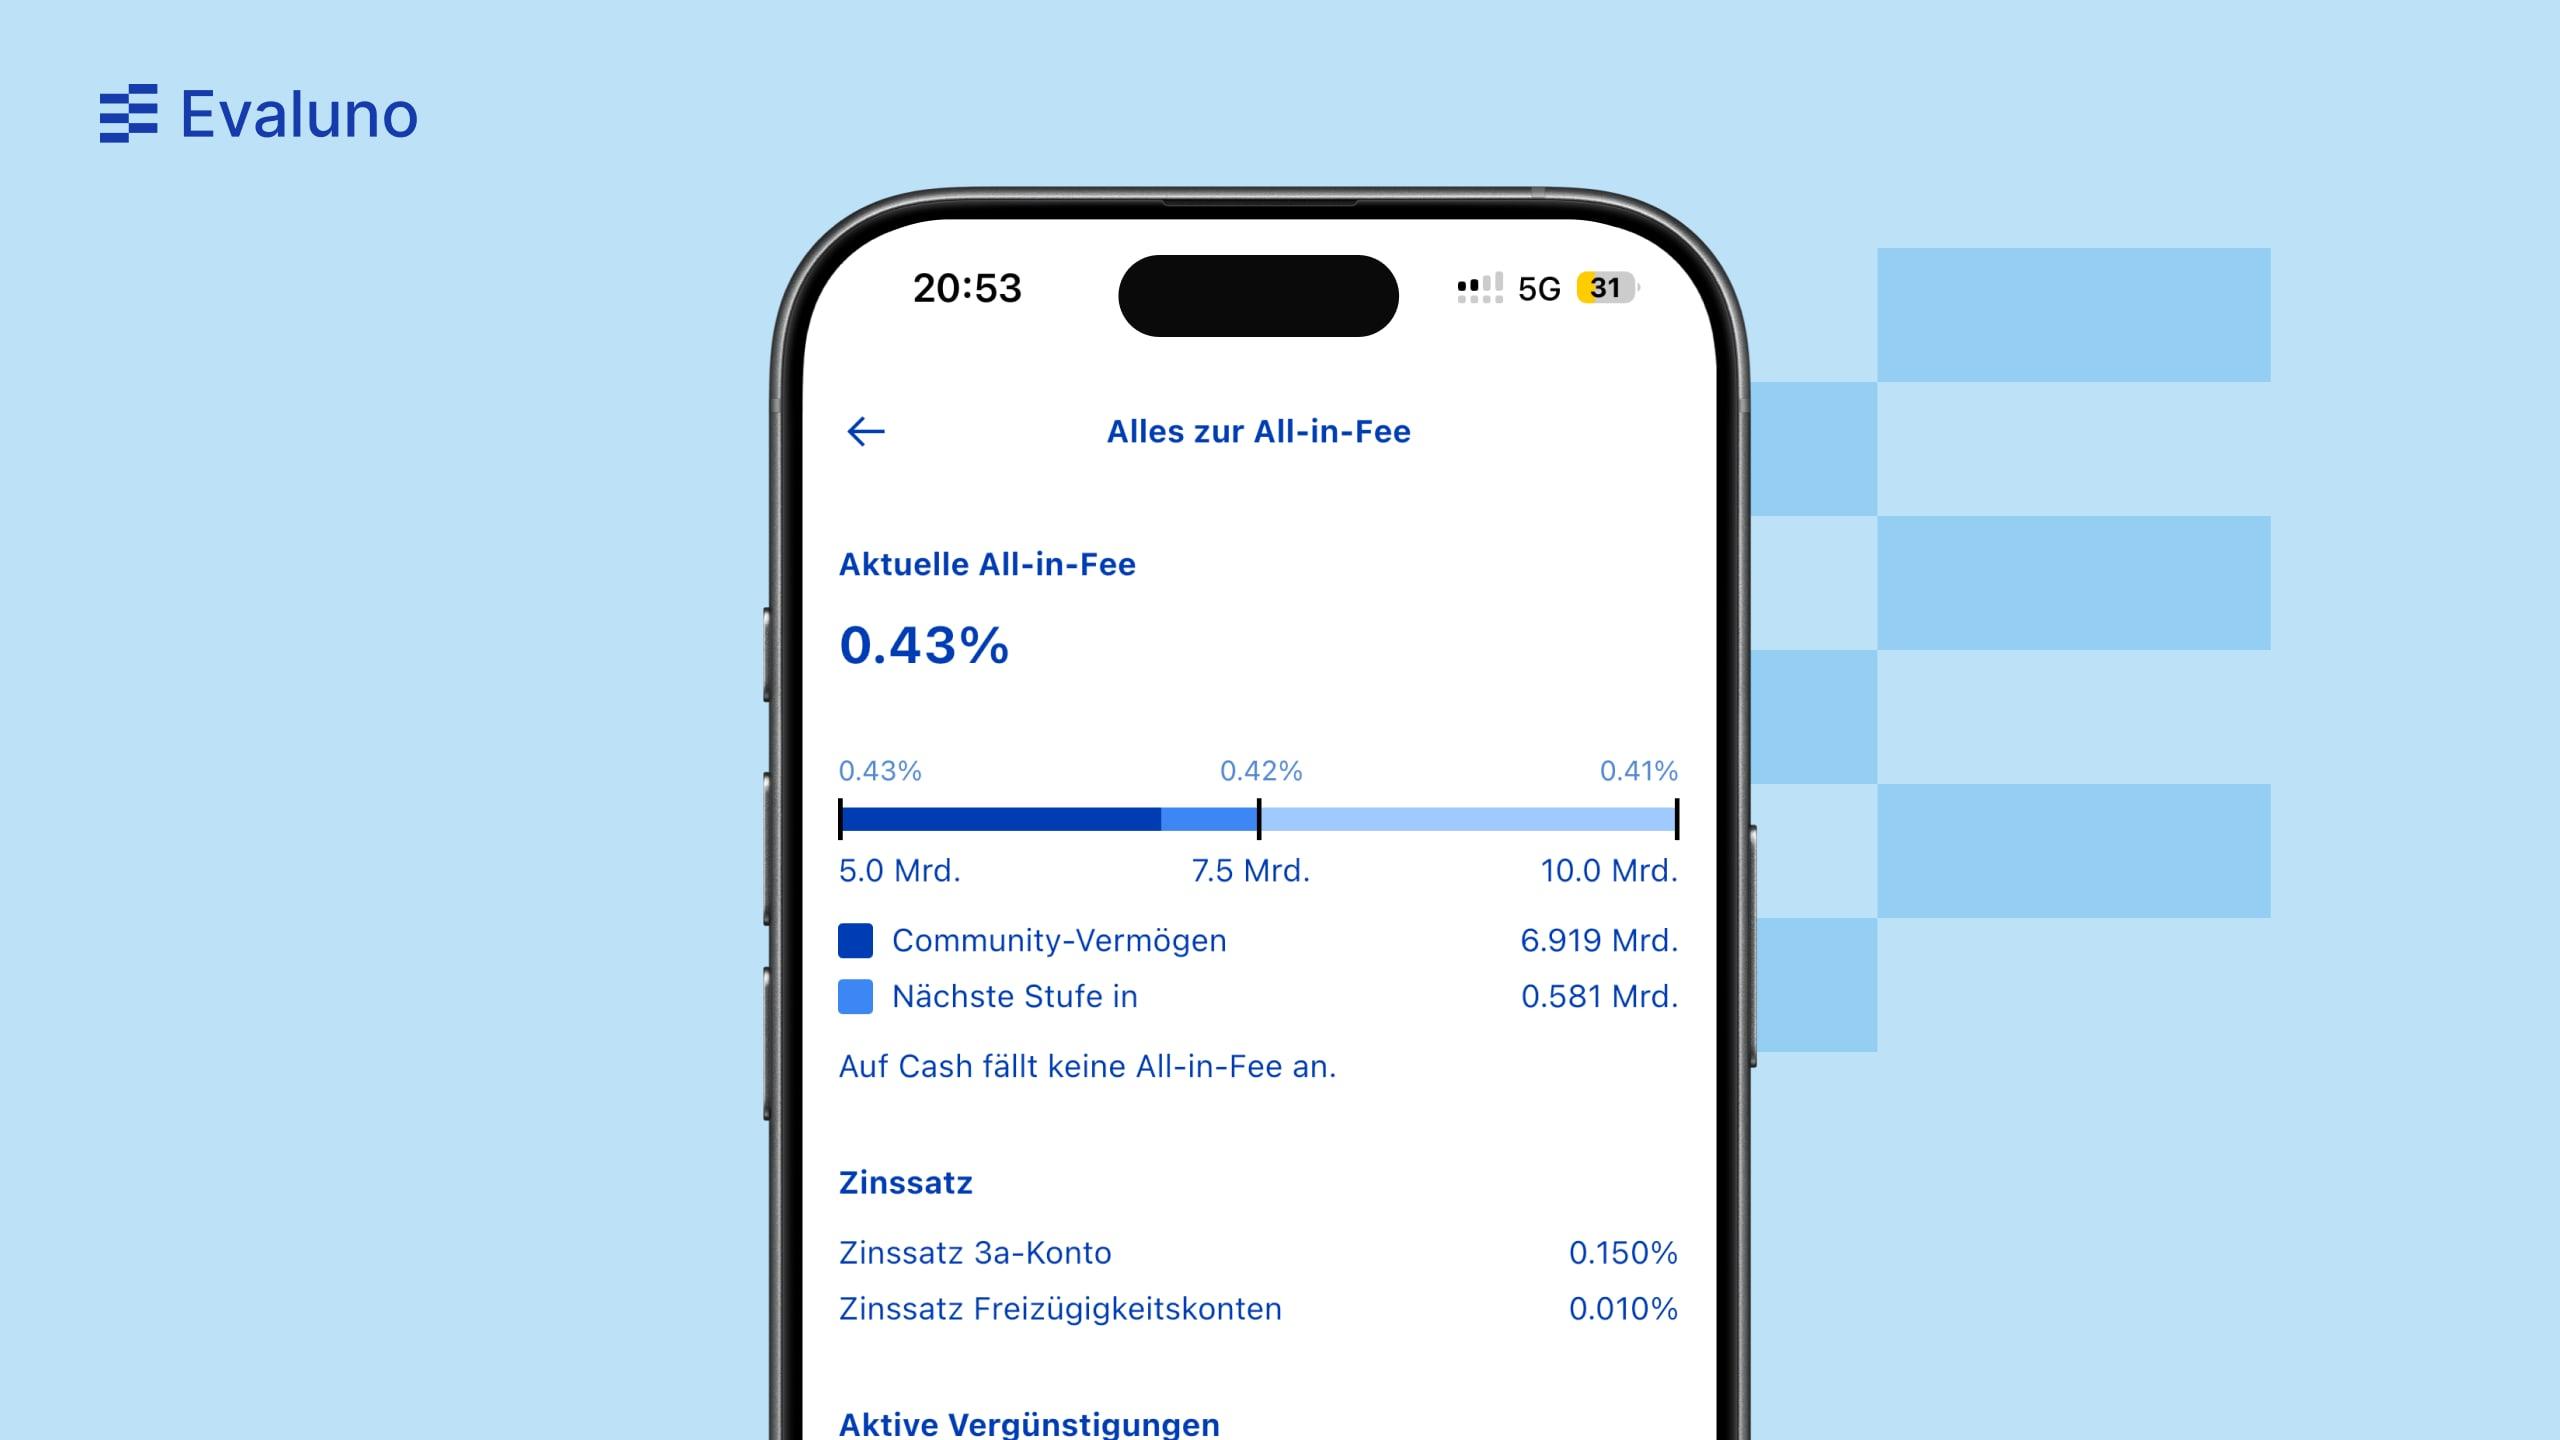
The more money the frankly community invests, the lower the All-in fee becomes for everyone. On 28 October 2026, the community’s assets stood at CHF 6.9 billion according to the app, so the tier from CHF 5 billion applies, at 0.43 %. From CHF 7.5 billion, the All-in fee drops to 0.42 %, and from CHF 10 billion to 0.41 %. frankly shows the tiers in the app and in the web version.
What the All-in fee includes and what it doesn’t
- Included: opening and managing the account, purchases and sales, custody of securities, early withdrawal and pledging for home ownership
- Not included: issue and redemption charges on Index products (for Extreme 95 Index, e.g. 0.09 % when buying and 0.08 % when selling)
Example: how much you pay a year
With a balance of CHF 50'000 invested, you pay CHF 215 to 235 a year, depending on the product.
| Balance | Invested (0.43 to 0.47 %) | Not invested (0 %) |
|---|---|---|
| CHF 10'000 | CHF 43 to 47 | CHF 0 |
| CHF 50'000 | CHF 215 to 235 | CHF 0 |
| CHF 100'000 | CHF 430 to 470 | CHF 0 |
frankly 3a strategies: Sustainable, Responsible or Index?
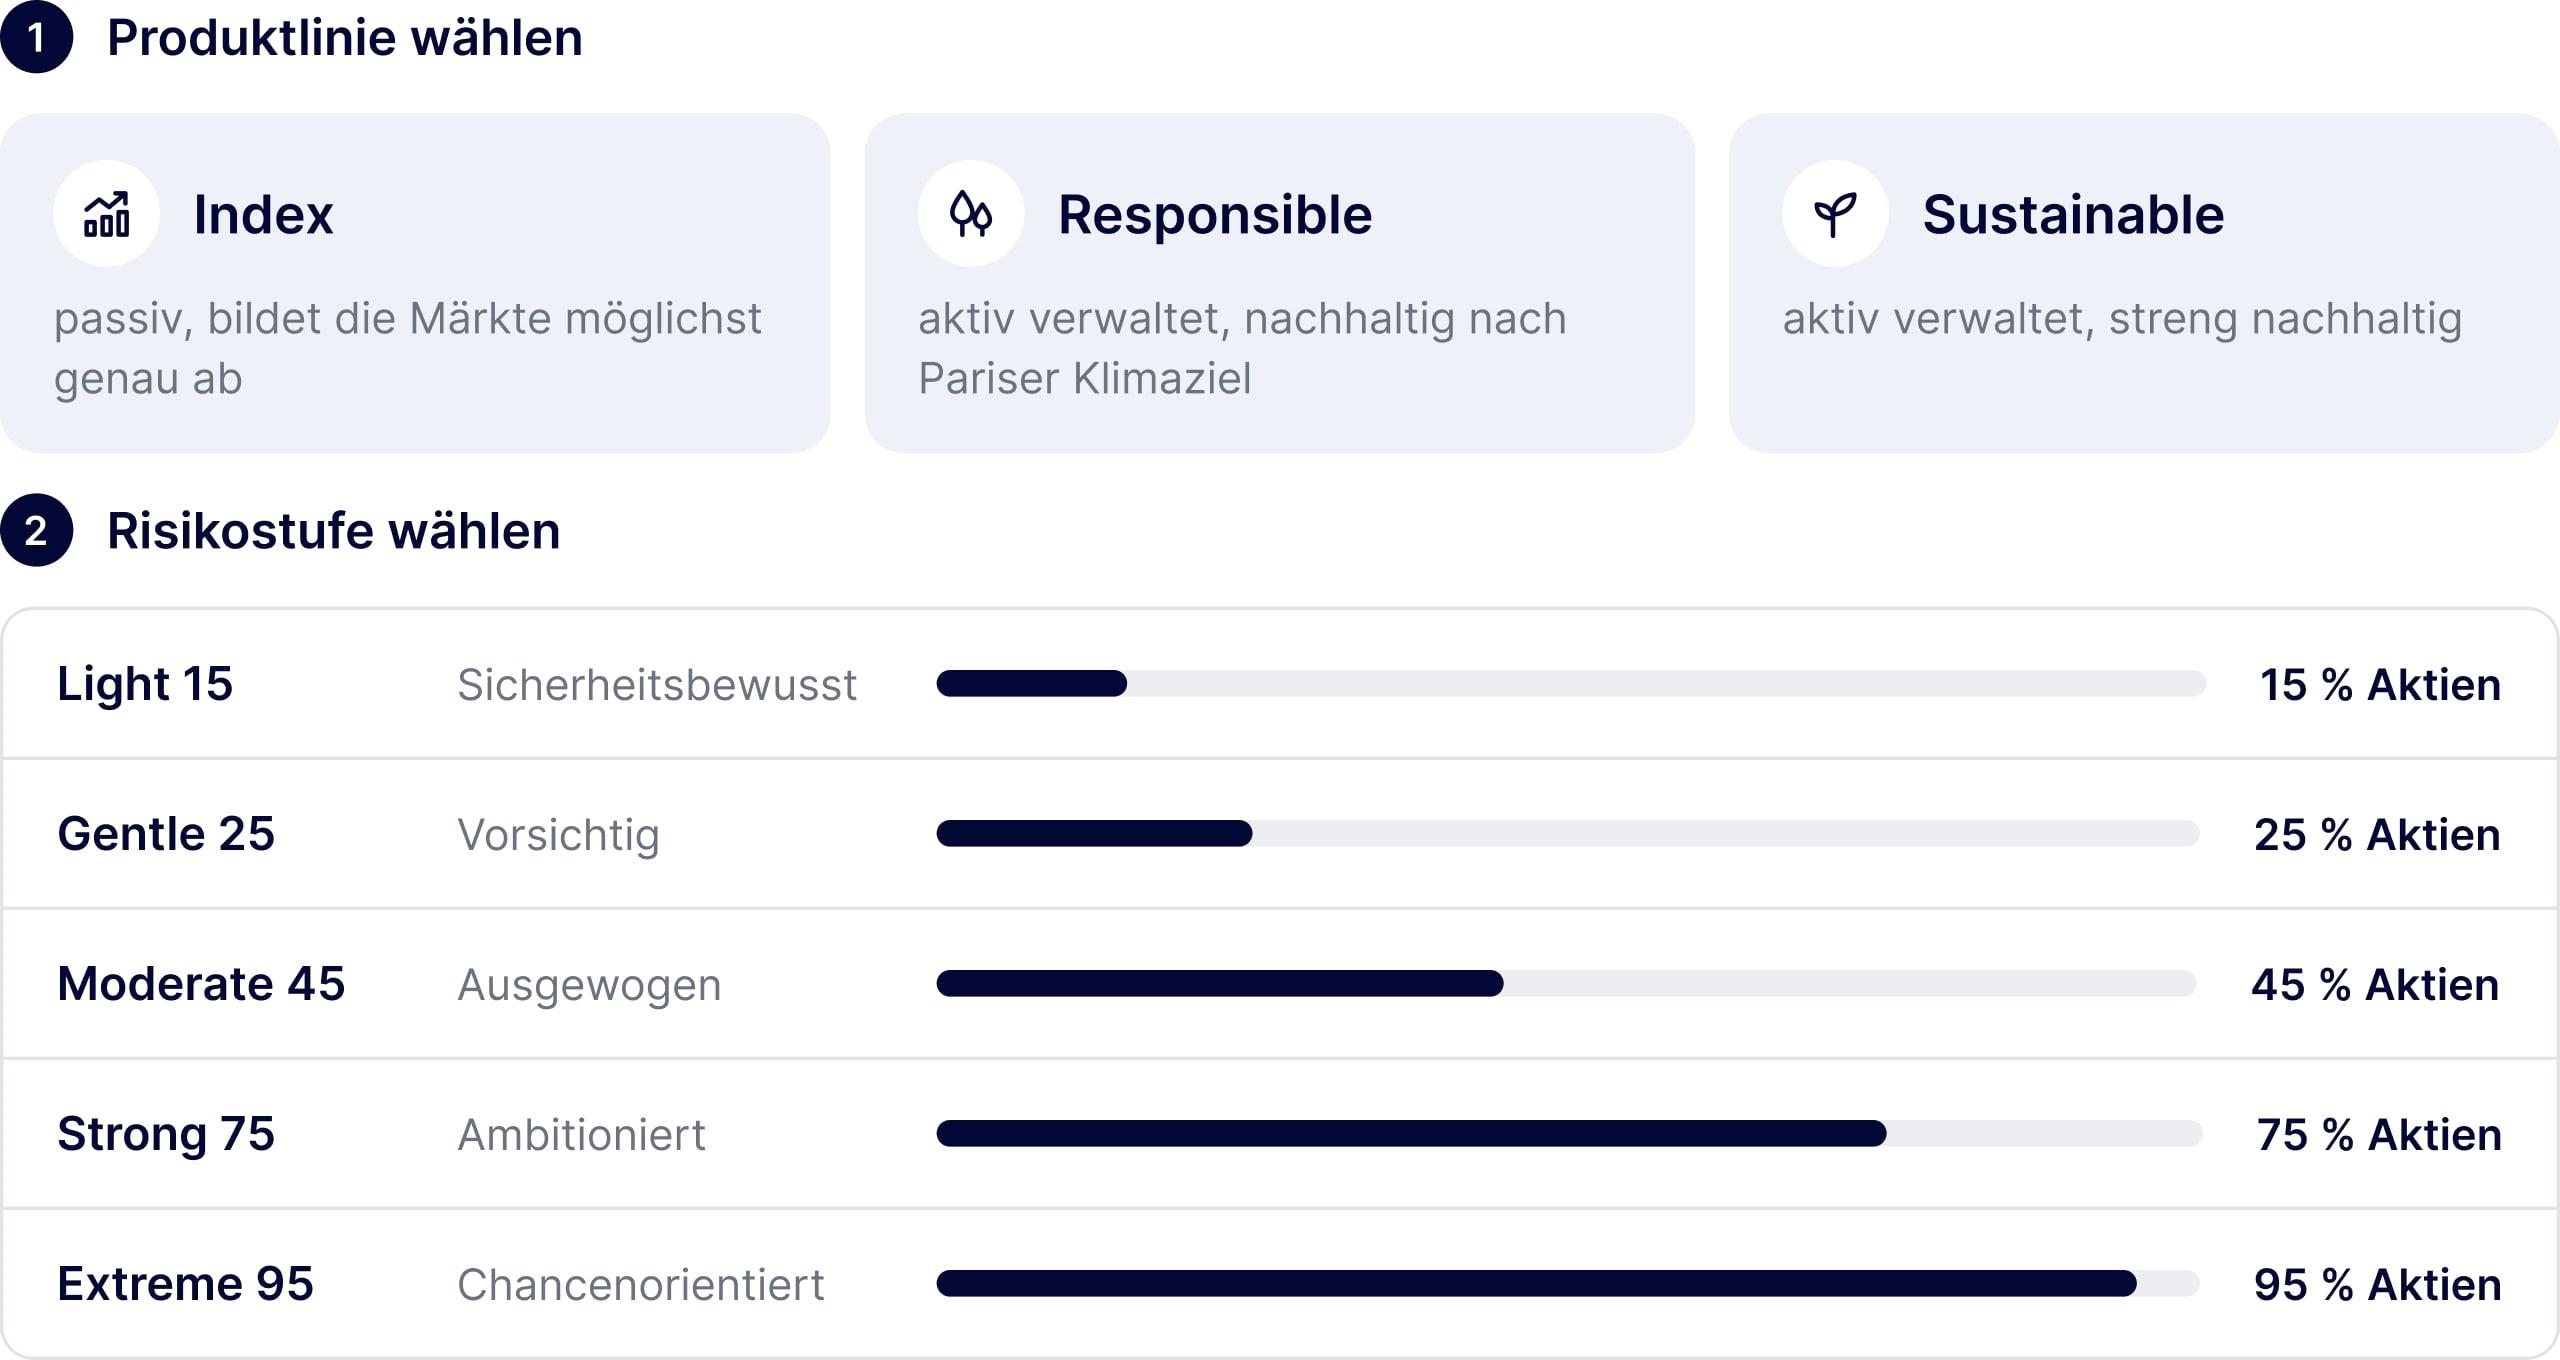
With frankly, you first choose a product line and then one of five risk levels. The product lines differ in how they are managed: Index tracks the markets passively and as closely as possible, while Responsible and Sustainable are actively managed by Swisscanto and take sustainability into account to differing degrees. The risk level determines the equity share. Depending on the level, it ranges from 15 to 95 %, and the number in the name shows it, for example Light 15 or Extreme 95.
A simple approach helps you choose: first consider how important sustainability and active management are to you, which gives you the product line. Then choose the risk level according to your investment horizon and how well you can cope with price fluctuations. When you open your account, the frankly app asks about your investment horizon, risk and sustainability, and you then choose the right investment product.
The investment products at a glance
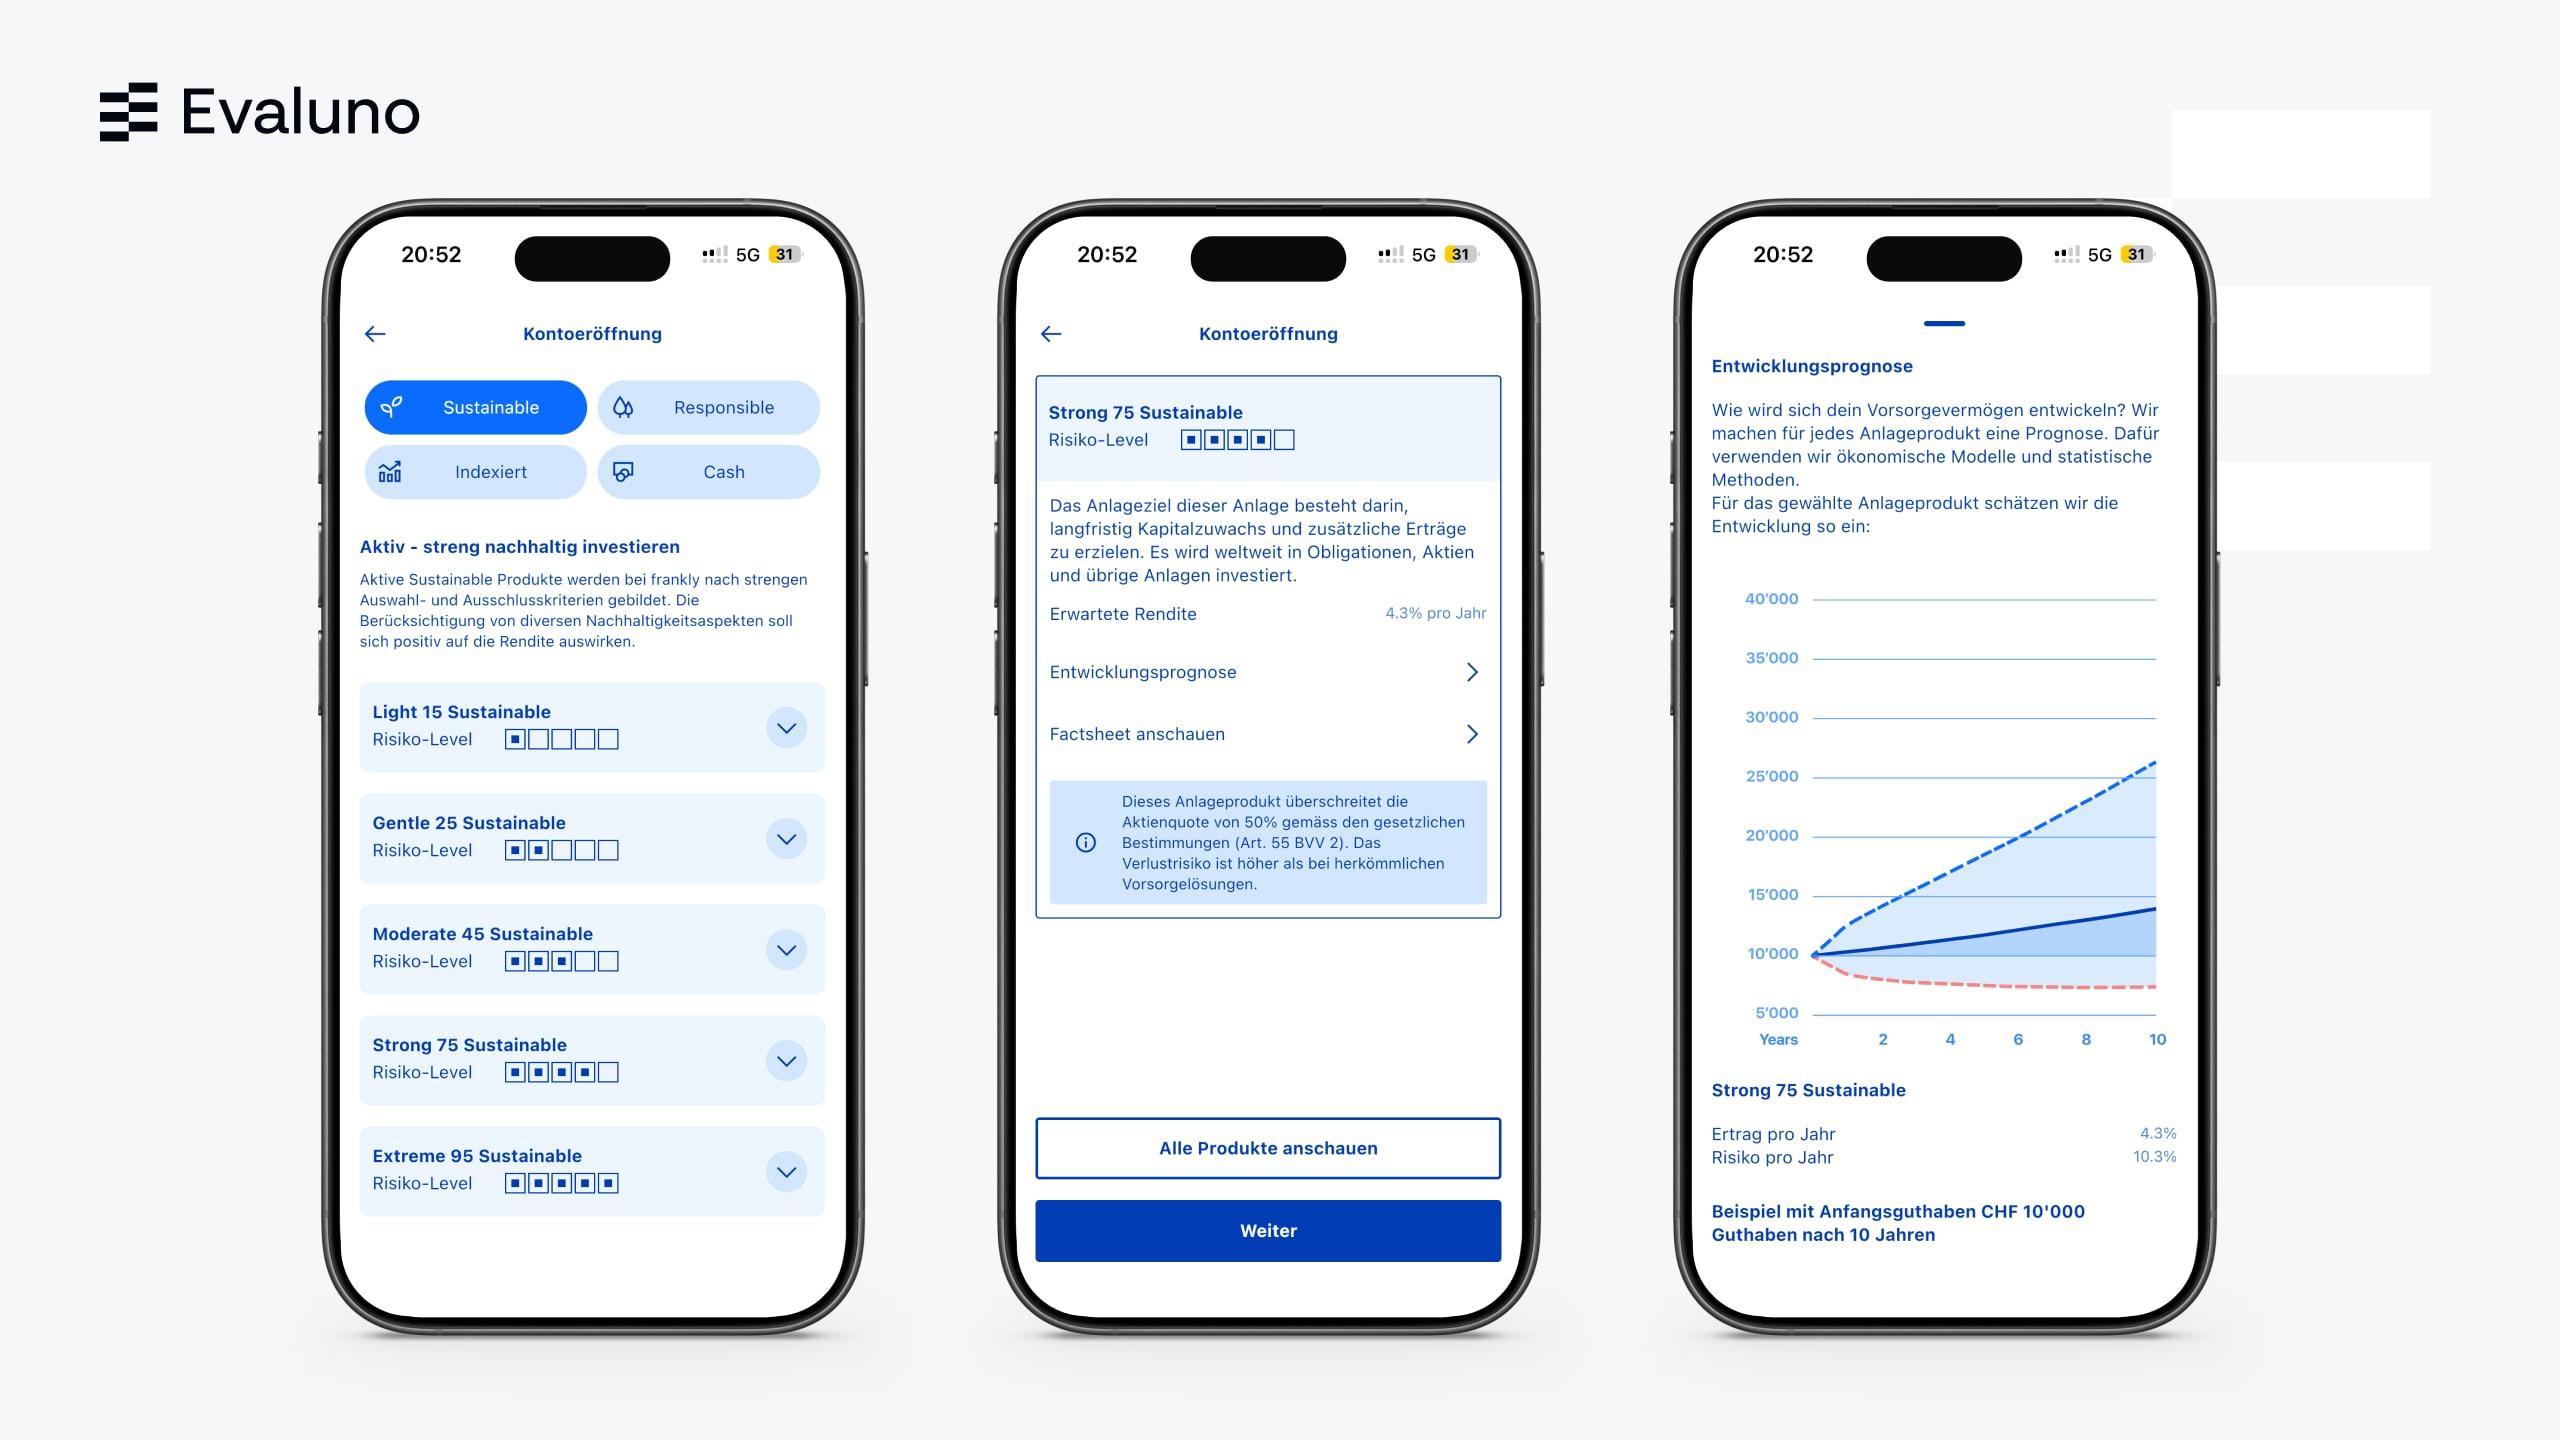
In the frankly app, you can view each investment product with its risk level, details and performance forecast, and select it directly. You can switch strategy in the app at any time. You can also hold up to five 3a accounts, each with its own strategy.
Sustainable, Responsible or Index: what’s the difference?
Sustainable goes furthest on sustainability and invests specifically in companies and countries that contribute to the UN Sustainable Development Goals. Responsible is aligned with the Paris climate goal, while Index tracks the markets without active stock selection. If you don’t want any investment risk, you save the money as cash in the 3a account, without the All-in fee and currently with 0.15 % interest.
Which strategy suits you?
What matters is your investment horizon and how well you cope with fluctuations. Retirement is often decades away, which is why a high equity share such as Strong 75 or Extreme 95 suits many people. If you need the money in a few years, for example for a home, a low risk level or cash makes more sense. With up to five accounts, you can combine both.
frankly returns: how the strategies perform
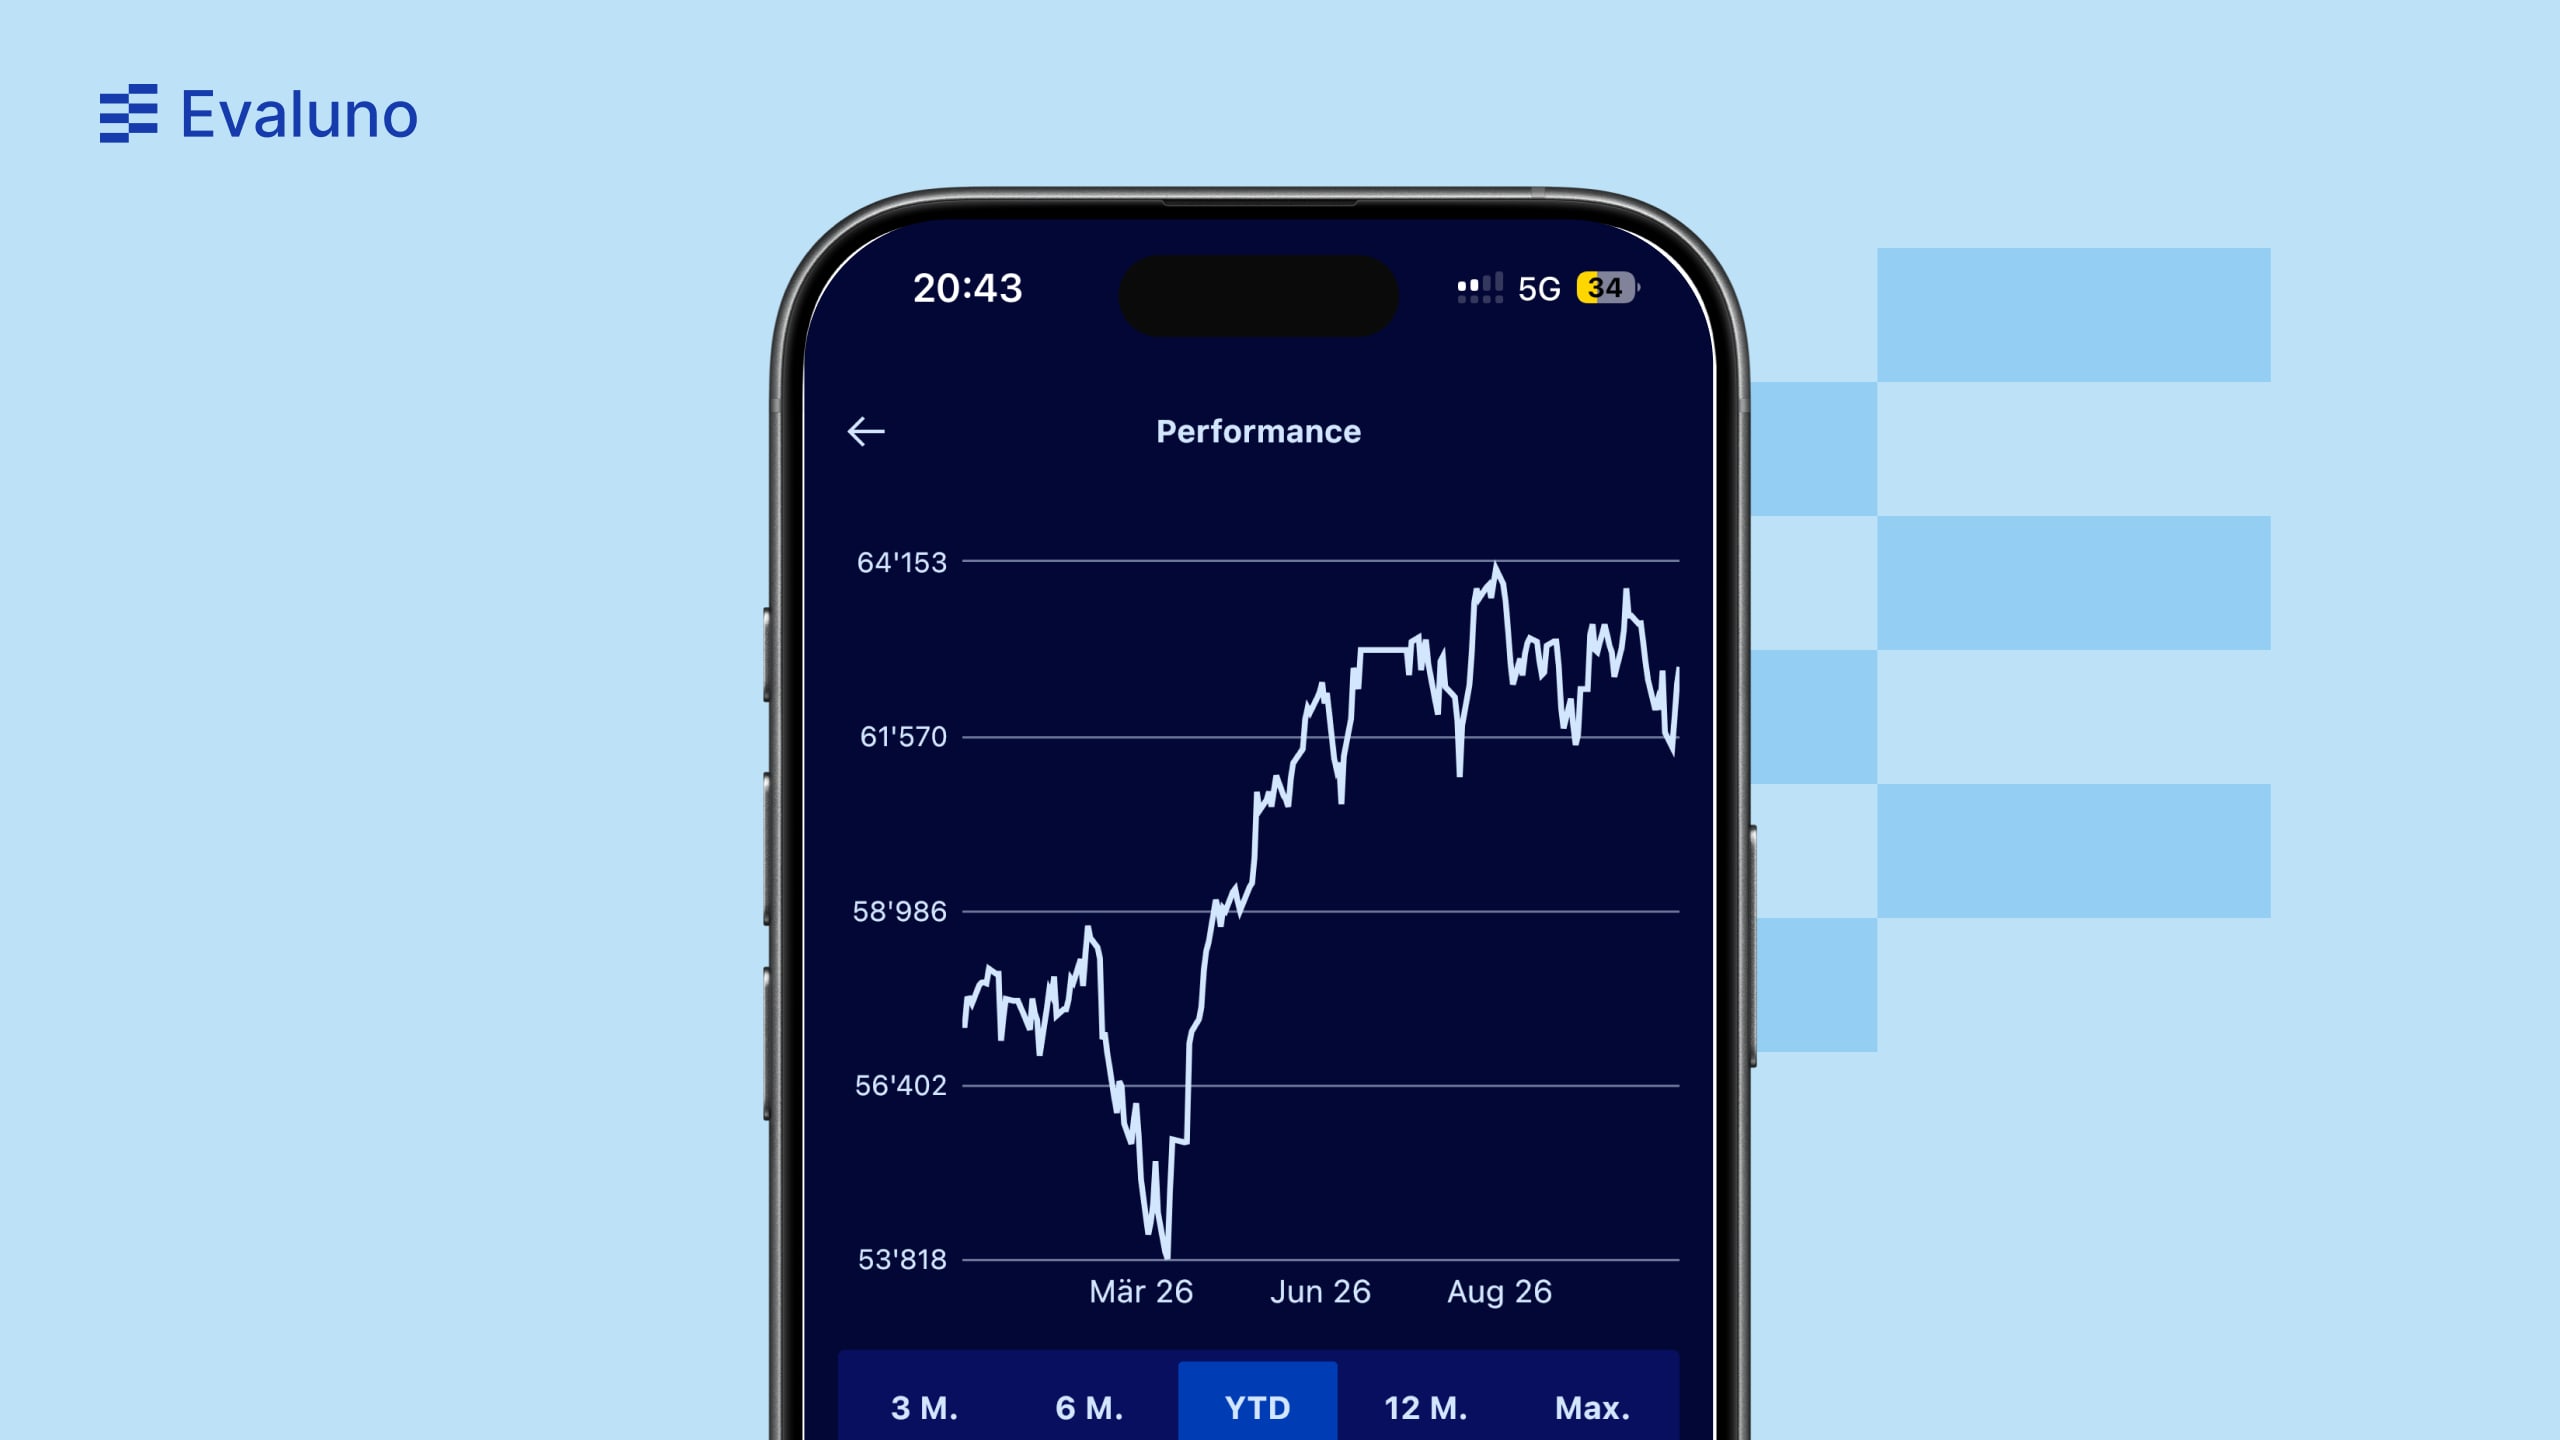
The return you achieve with frankly depends mainly on the equity share. In the five years to 30 September 2026, Extreme 95 Responsible gained 44.5 % and Light 15 Responsible 6.3 %. Over five years, the actively managed Responsible version was slightly ahead of the Index version at every comparable risk level; over three years, Index was ahead.
Performance of the frankly products
The tables show the performance of all 15 frankly products over one, three and five years, so you can see at a glance how the three product lines differ for the same equity share.
| Risk level | Equities | Index | Responsible | Sustainable |
|---|---|---|---|---|
| Extreme 95 | 95 % | +16.7 % | +17.3 % | +20.3 % |
| Strong 75 | 75 % | +15.2 % | +14.7 % | +15.6 % |
| Moderate 45 | 45 % | +9.9 % | +8.4 % | +8.2 % |
| Gentle 25 | 25 % | +5.2 % | +5.1 % | +3.8 % |
| Light 15 | 15 % | +3.0 % | +2.8 % | +1.7 % |
Source: Evaluno pillar 3a fund comparison (data as of 30.9.2026). Cumulative performance in CHF to 30.9.2026. «–»: no figures yet for this period. Past returns are no guarantee of future returns.
| Risk level | Equities | Index | Responsible | Sustainable |
|---|---|---|---|---|
| Extreme 95 | 95 % | +53.5 % | +51.0 % | +56.0 % |
| Strong 75 | 75 % | +45.1 % | +41.5 % | +42.8 % |
| Moderate 45 | 45 % | +30.1 % | +26.0 % | +24.5 % |
| Gentle 25 | 25 % | +20.9 % | +18.0 % | +15.6 % |
| Light 15 | 15 % | – | +14.1 % | – |
Source: Evaluno pillar 3a fund comparison (data as of 30.9.2026). Cumulative performance in CHF to 30.9.2026. «–»: no figures yet for this period. Past returns are no guarantee of future returns.
| Risk level | Equities | Index | Responsible | Sustainable |
|---|---|---|---|---|
| Extreme 95 | 95 % | +41.7 % | +44.5 % | – |
| Strong 75 | 75 % | +33.8 % | +35.5 % | – |
| Moderate 45 | 45 % | +18.4 % | +20.6 % | – |
| Gentle 25 | 25 % | +8.7 % | +11.4 % | – |
| Light 15 | 15 % | – | +6.3 % | – |
Source: Evaluno pillar 3a fund comparison (data as of 30.9.2026). Cumulative performance in CHF to 30.9.2026. «–»: no figures yet for this period. Past returns are no guarantee of future returns.
frankly vs VIAC and finpension
In short: VIAC and finpension are slightly cheaper and allow up to 99 % equities. frankly scores with Zürcher Kantonalbank behind it and actively managed, sustainable Swisscanto funds.
The biggest difference lies in the investments: VIAC and finpension rely mainly on low-cost index funds and also let you put together your own strategy. Besides Index products, frankly offers actively managed funds and gives you a fixed choice of 15 strategies. On returns, frankly holds its own: over five years, its best product (+44.5 %) was level with VIAC (+44.4 %) and clearly ahead of finpension (+37.0 %).
If you want the lowest possible costs and your own strategy, finpension or VIAC is the right choice. If you’re looking for a simple pillar 3a from a cantonal bank with sustainable funds, frankly is a good option. The table shows the main differences. You’ll find all digital 3a providers in the Evaluno pillar 3a fund comparison.
| Criterion | frankly |  VIAC |  finpension |
|---|---|---|---|
| Total costs per year | 0.43 to 0.47 % | 0.41 to 0.44 % | 0.39 % |
| Max. equity share | 95 % | 99 % | 99 % |
| Investment strategies | 15 | 15 | 18 |
| Custom strategy | No, fixed strategies only | Yes, funds and weightings freely selectable | Yes, funds and weightings freely selectable |
| Index strategies | Yes | Yes | Yes |
| Sustainable strategies | Yes | Yes | Yes |
| Best 5-year return | +44.5 % | +44.4 % | +37.0 % |
| Best product | Extreme 95 Responsible | Global Nachhaltig 100 | Global 100 |
| Interest on 3a account | 0.15 % | 0.20 % | 0.00 % |
Total costs per year including product costs. Interest on uninvested balance, as of November 2026. Return over 5 years to 30.9.2026, in each case for the provider’s best product. Source: Evaluno pillar 3a fund comparison (data as of 30.9.2026). Past returns are no guarantee of future returns.
Is frankly safe?
Yes. Your 3a balance is not held by the bank but by ZKB’s Sparen 3 pension foundation. Invested money is held in Swisscanto investment products, which are separate from the bank and do not form part of the bankruptcy estate if it fails. The foundation deposits uninvested money with Zürcher Kantonalbank, whose liabilities are backed by the Canton of Zurich’s state guarantee.
Securities fluctuate: with a high equity share, your balance can fall significantly at times. frankly protects access with two factors, namely a password and a registered smartphone or an SMS code. In the app, you can also log in with your fingerprint or face recognition.
The frankly app in everyday use
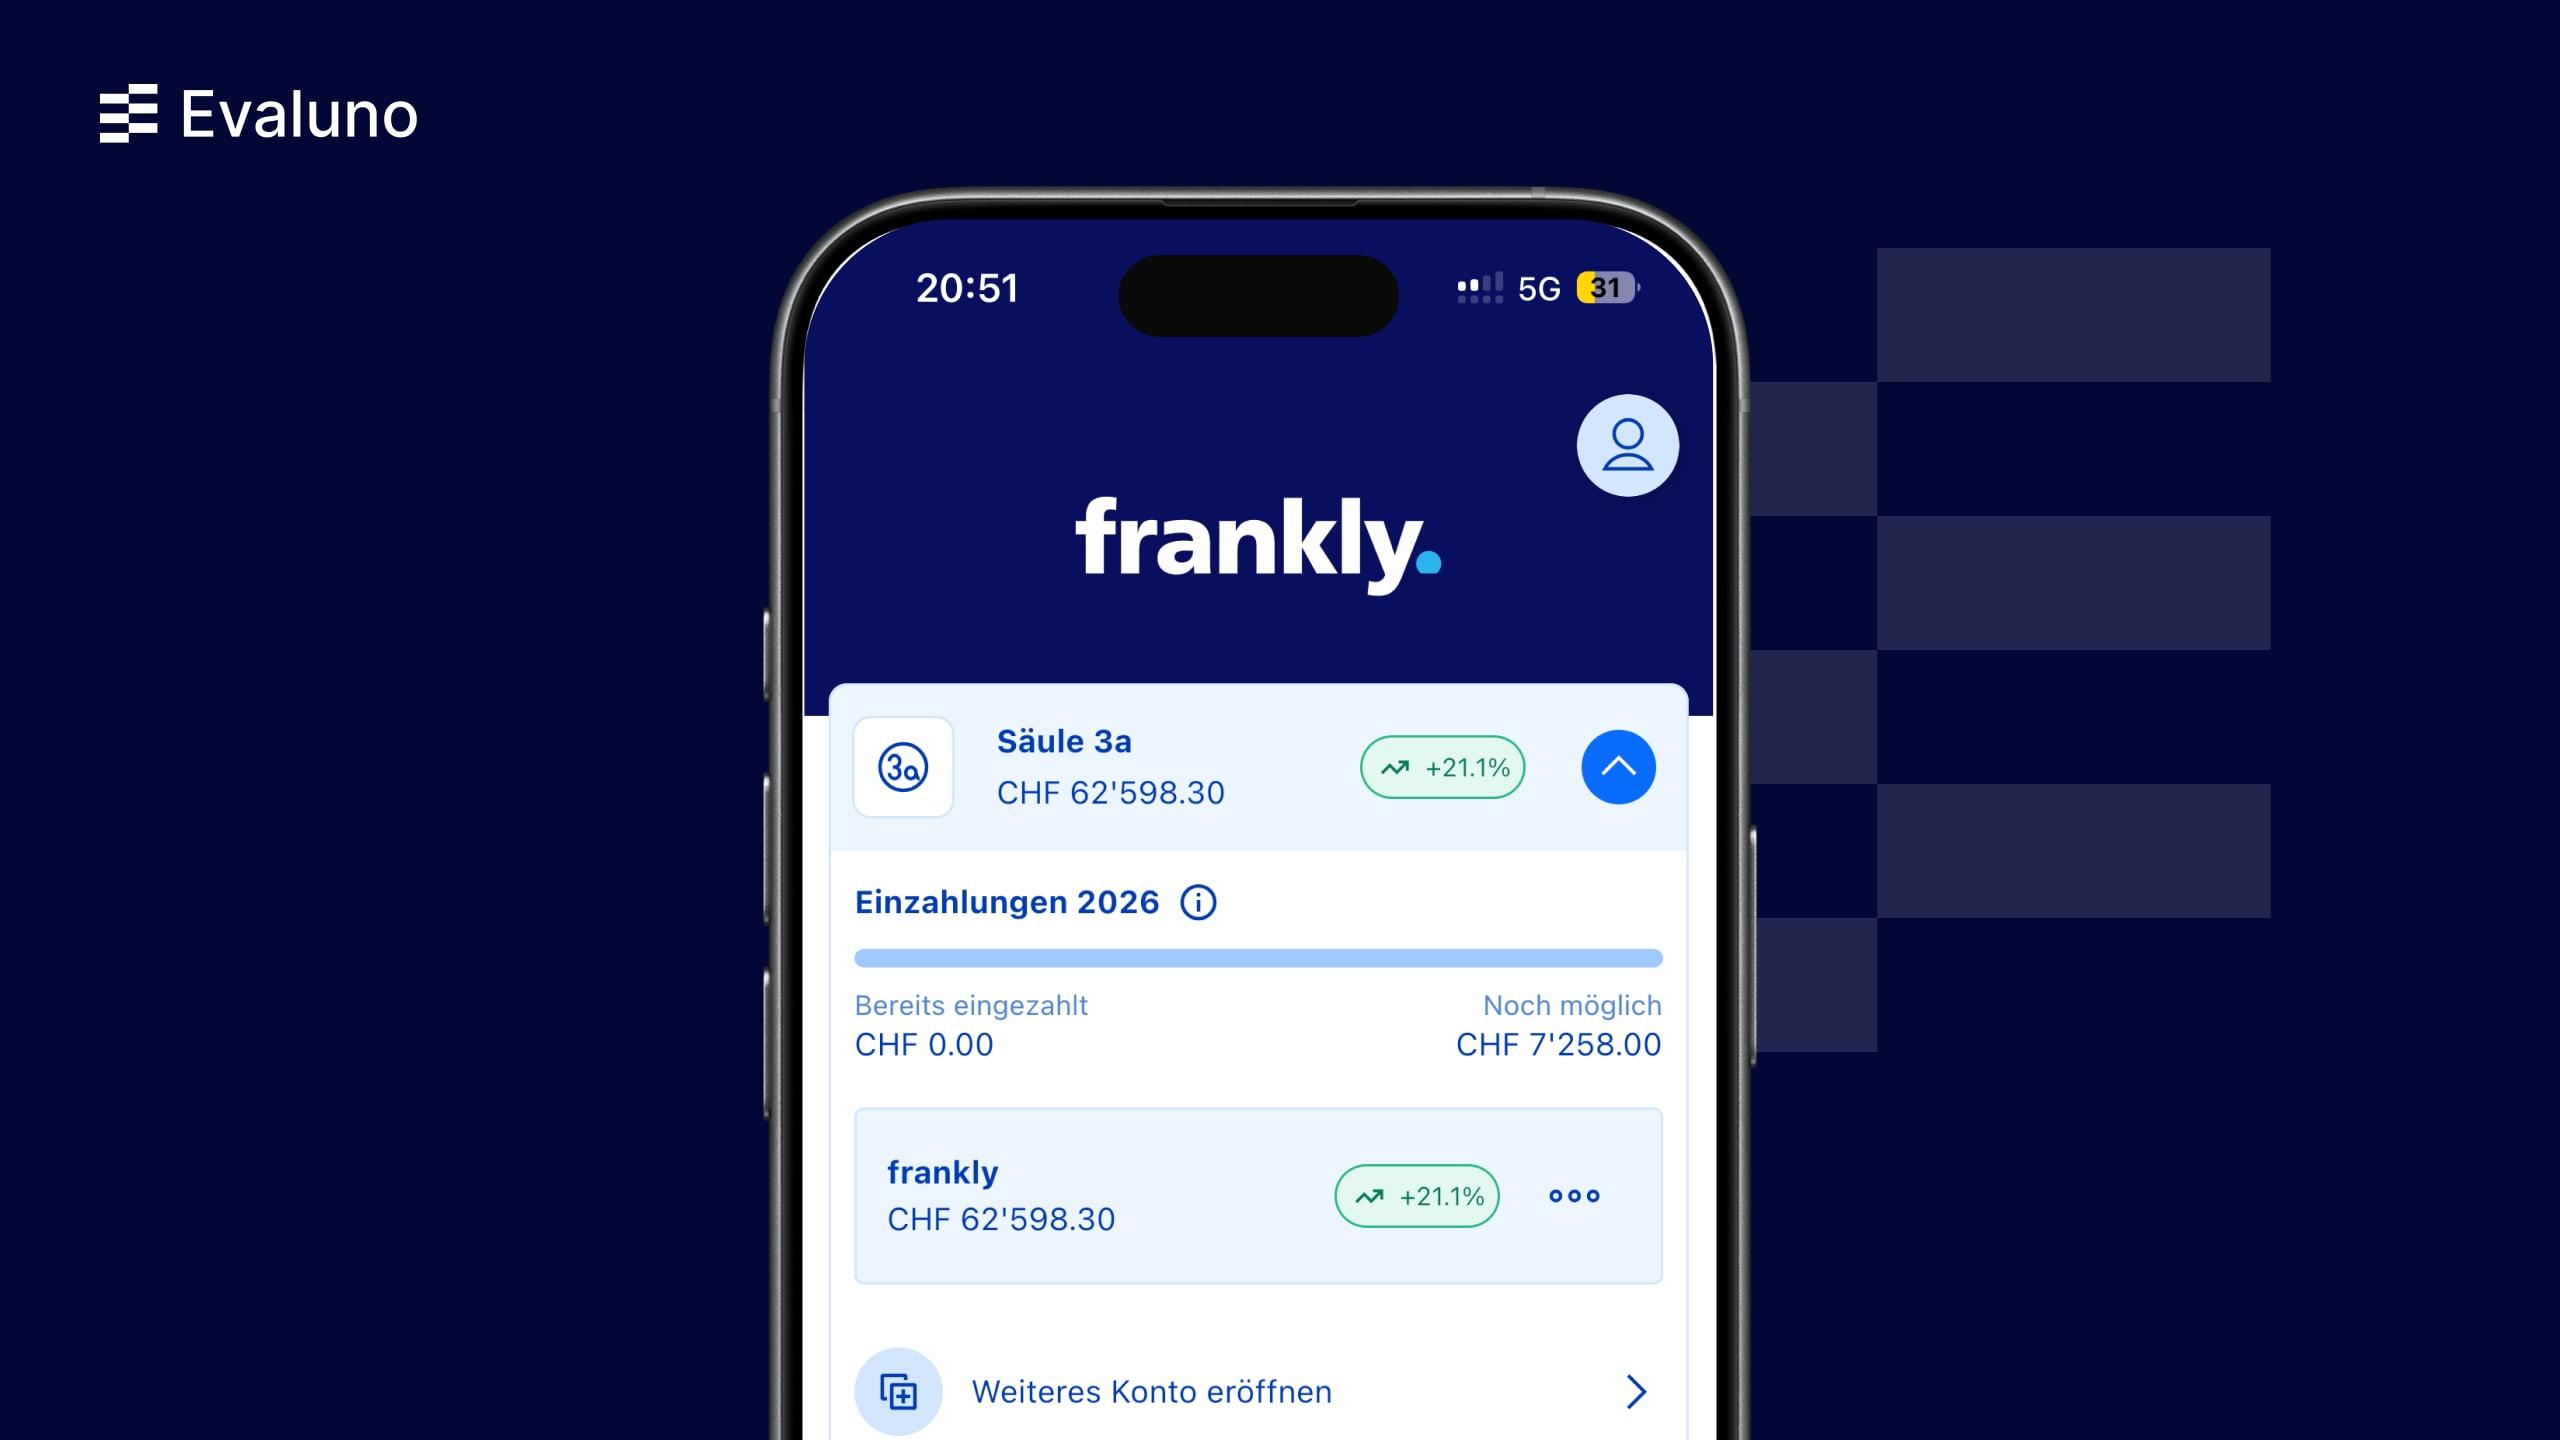
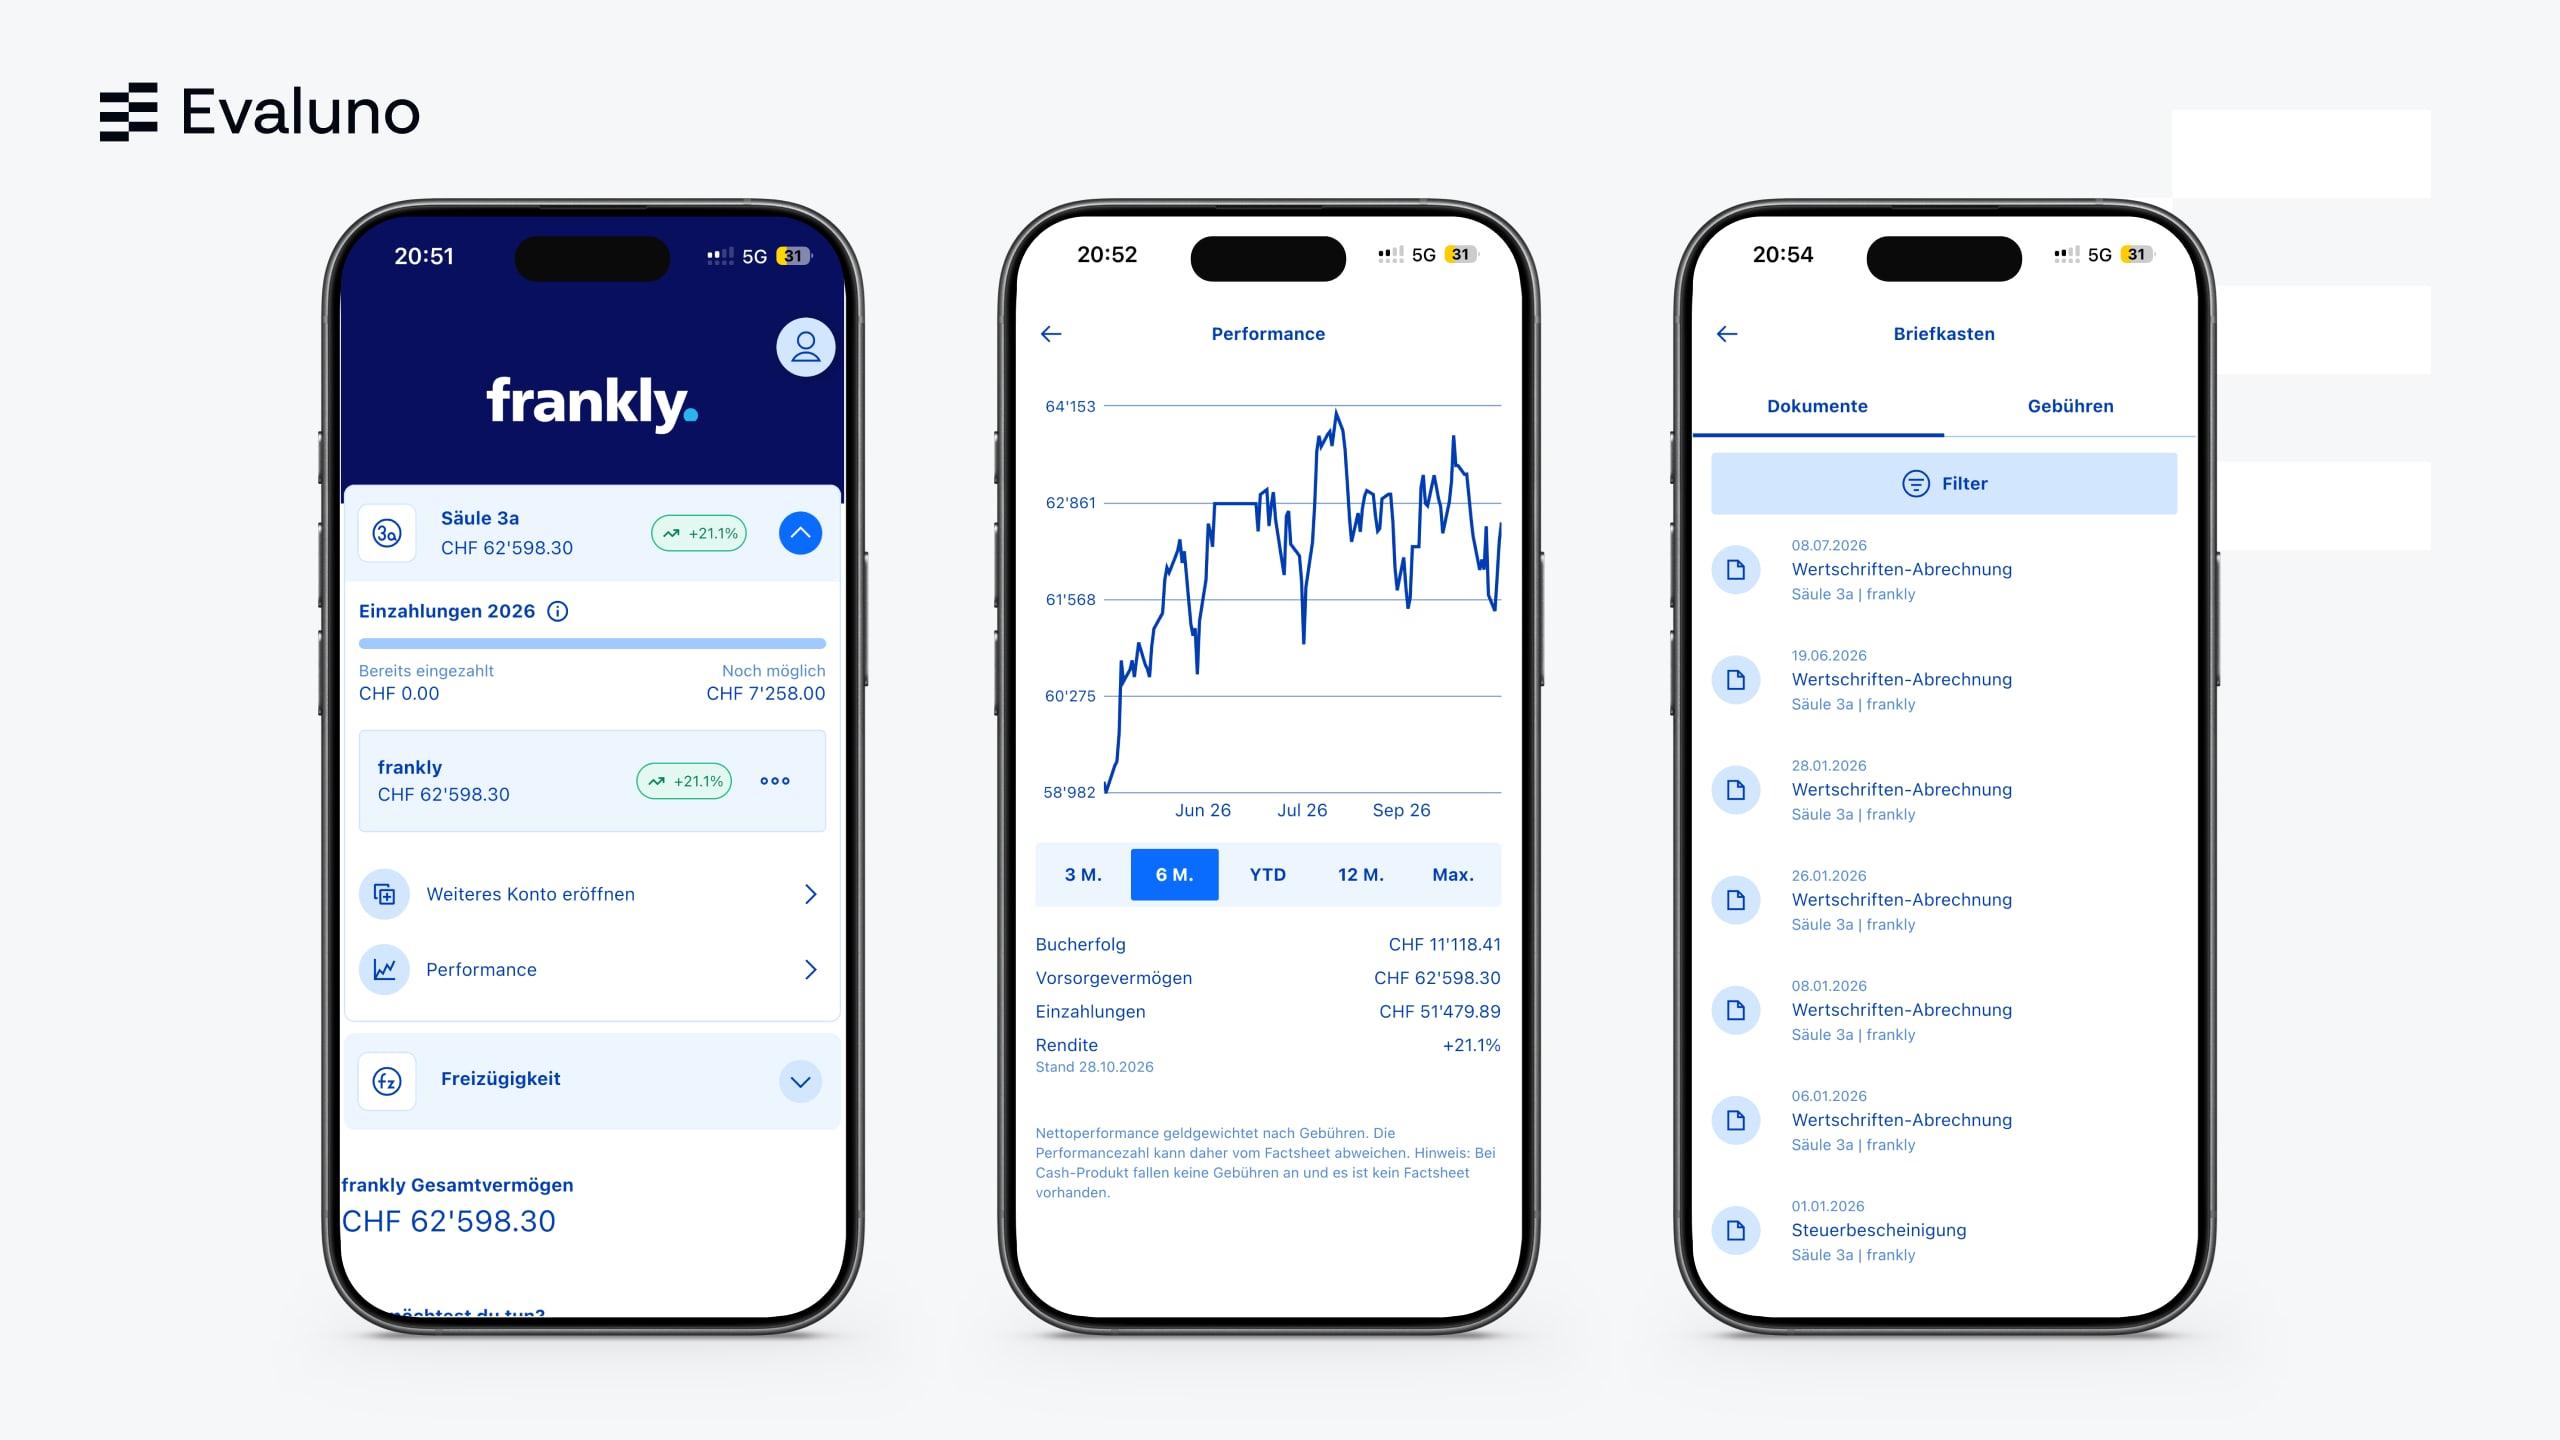
The frankly app is clearly structured and easy to use: you reach the most important functions directly from the home screen. There you can see your assets, the payments made this year and how much you can still pay in. Under «Performance», you track how your investments are doing over different periods, from three months to the entire investment period, including book gain and return. You open additional 3a accounts via «Open another account», and you can switch strategy directly in the app too.
Paying in
You pay in by bank transfer from your e-banking, most easily with a standing order. You’ll find the IBAN in the app’s payment section, and the web version also offers a QR code for it. With a ZKB eBanking contract, you can select frankly directly as the recipient account. In 2026, if you have a pension fund, you can pay in up to CHF 7'258 and deduct it from your taxes.
Tax certificate and documents
The tax certificate is available in the app’s «Mailbox» at the beginning of January, one for each account. That’s also where you’ll find the statements for your securities.
Support
Support is available by phone on 0800 320 002 and by email, Monday to Friday from 8 am to 10 pm and at weekends from 9 am to 6 pm. For pension questions, you can also make an appointment with a specialist.
frankly ratings: how satisfied are customers?
Customers rate frankly mostly positively. On the App Store, the frankly app has 4.7 out of 5 stars from 9'925 ratings, and on Google Play 3.8 out of 5 from 1'460 reviews. This largely matches Evaluno’s test: users mainly praise the easy handling, the quick account opening and the fair fees. Criticism mostly concerns the app’s technology, such as login problems after updates, the new design since the end of 2024 and the ID scan when opening an account, especially on Android devices.
How users rate frankly
As of 16.11.2026
- App Store
- 9'925 ratings
- 4.7 out of 5 stars
- Google Play
- 1'460 reviews
- 3.8 out of 5 stars
Often praised
- Simple, clear handling
- Quick account opening
- Fair fees
- Friendly support
Often criticised
- Login problems after updates
- New design with more clicks
- Orders take two to three bank working days
Sources: App Store and Google Play (Switzerland), accessed on 16.11.2026. Praise and criticism: summary of around 380 reviews.
frankly promo code: CHF 35 fee credit
With the code Evaluno35, you get a CHF 35 credit on your fees. Vouchers are only valid for new customers who enter the code within 48 hours of opening their first account, and they cannot be combined. The code is valid until 31 December 2026. The credit is offset against the All-in fee. You’ll find all the conditions on the Evaluno frankly promo code page. Evaluno receives a commission on accounts opened with the promo code.
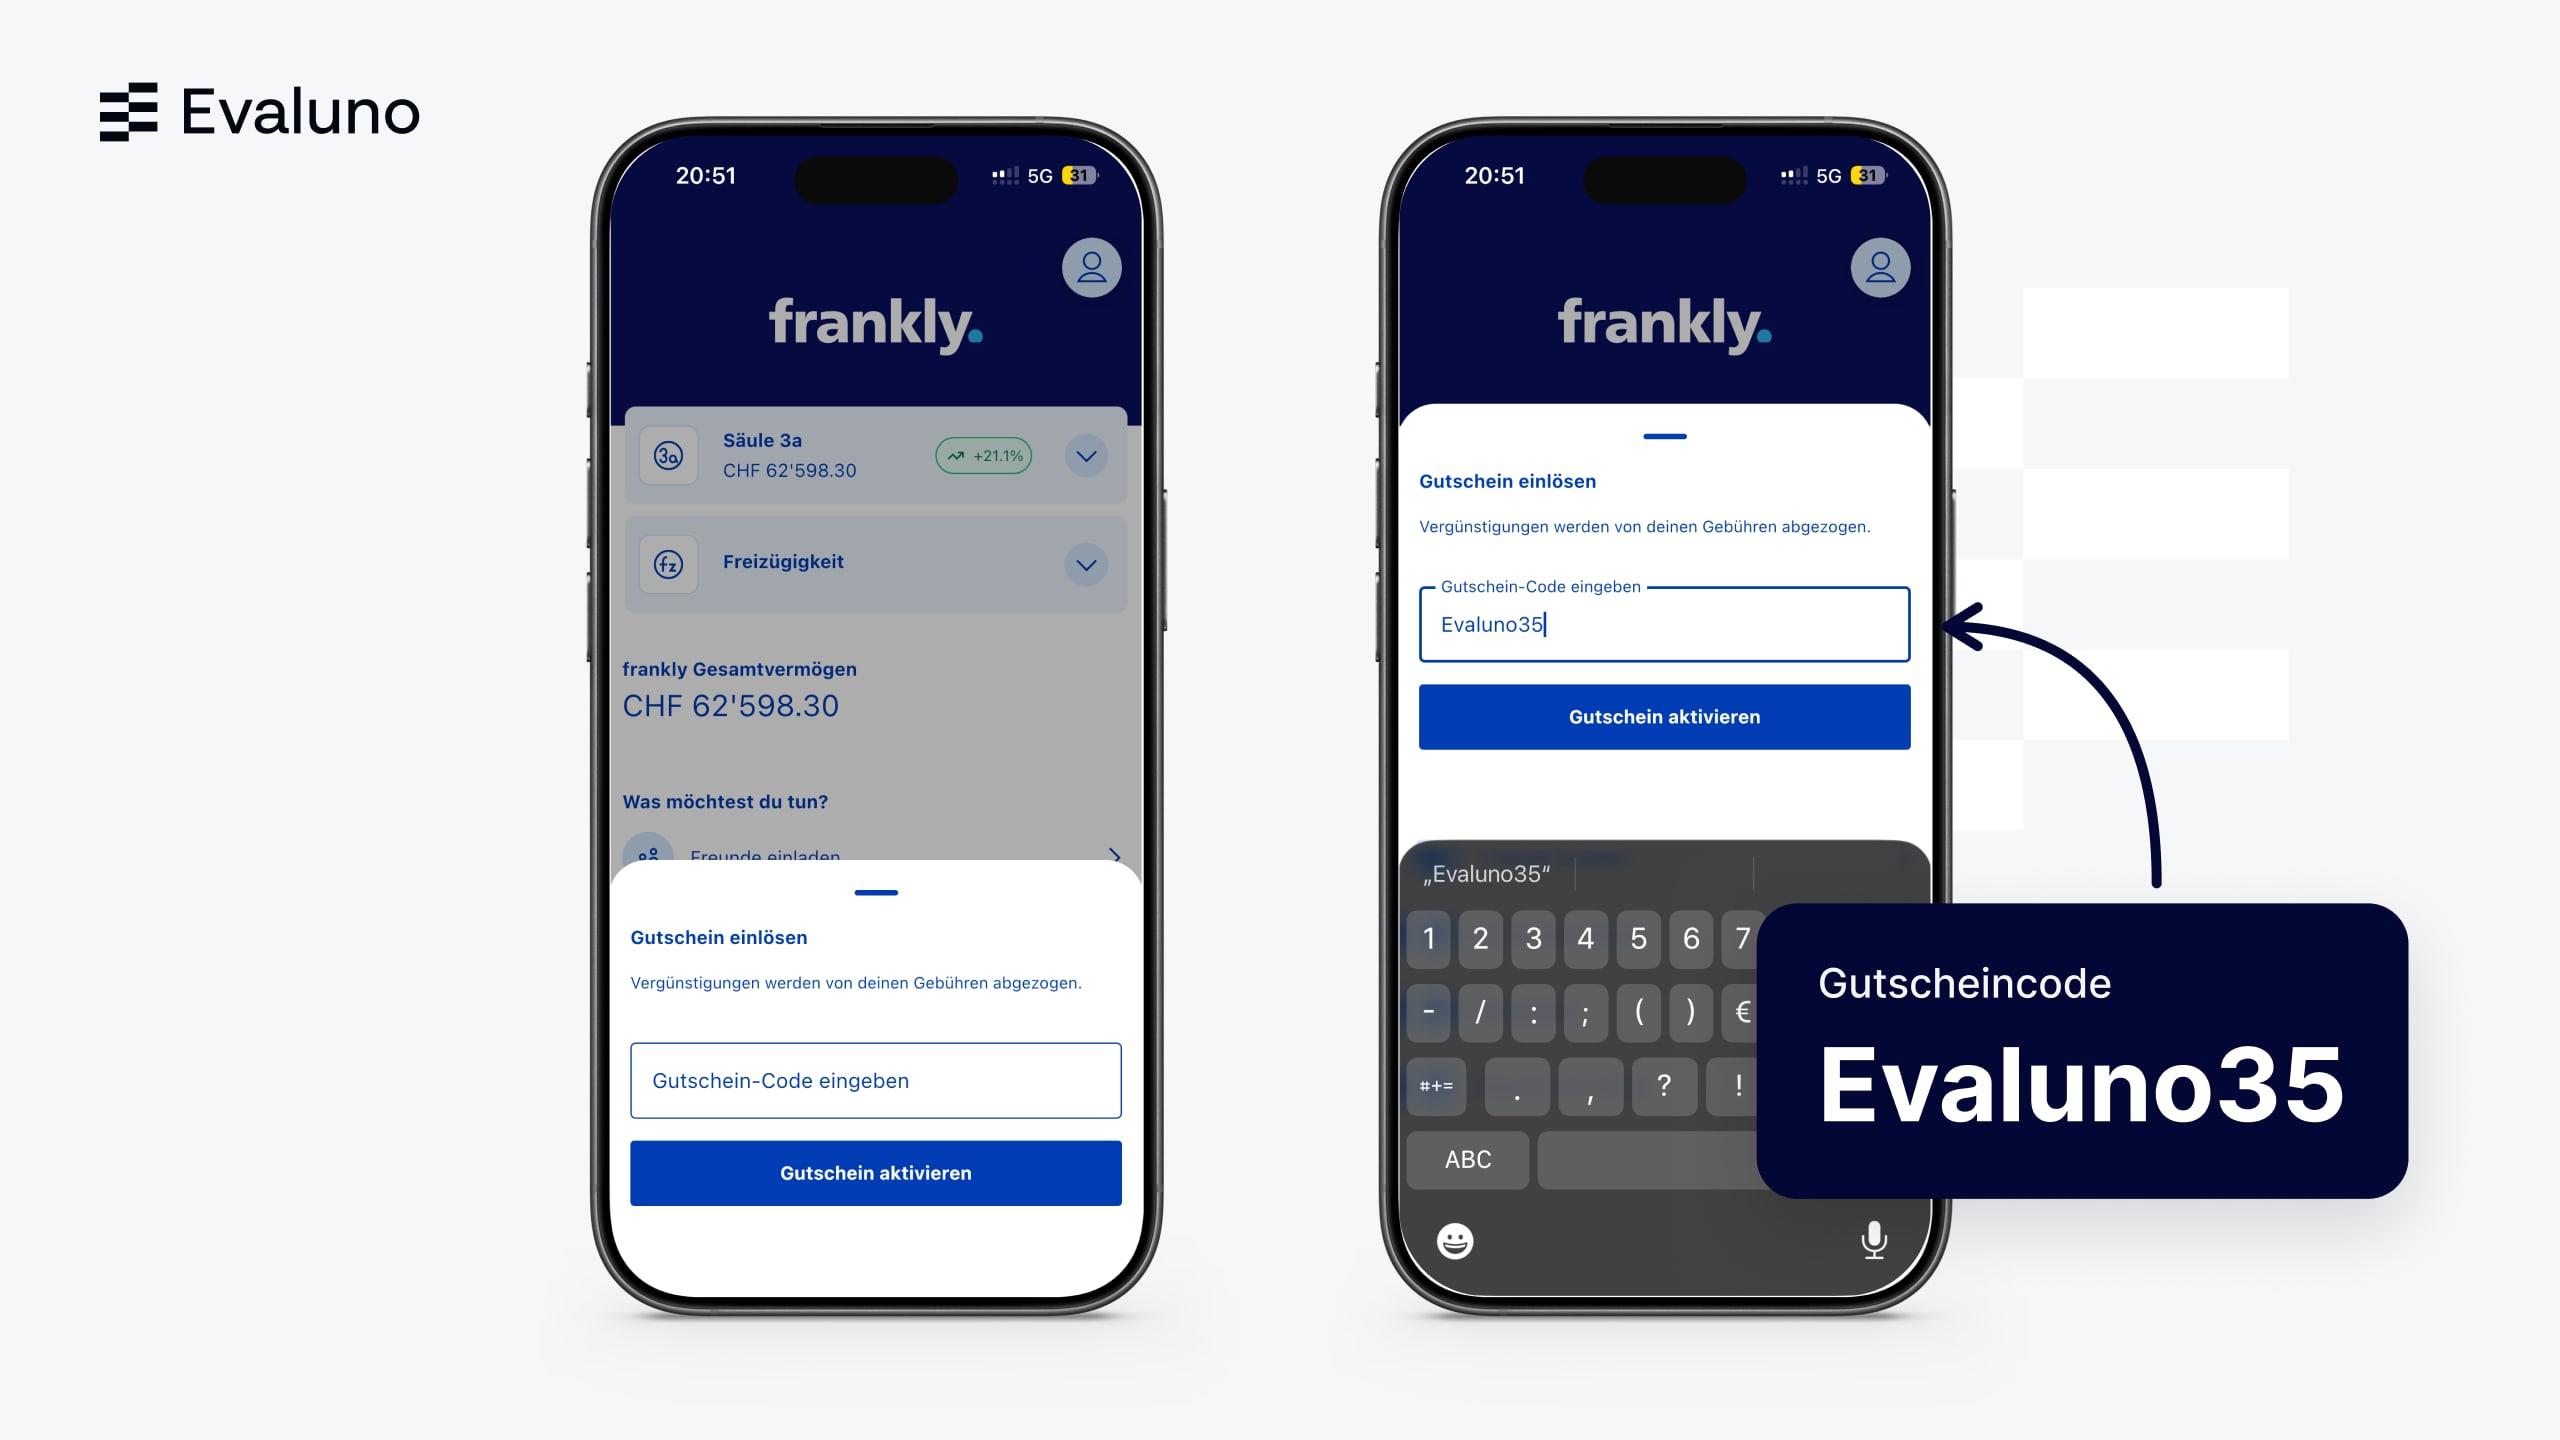
How to redeem the voucher
- Open an account in the frankly app or in the browser
- At the end of the opening process, choose «Redeem voucher» on the «Everything OK» page
- Enter the code Evaluno35 and confirm
- The credit appears under «All about the All-in fee» and is offset against your fees
Opening a frankly account: step by step
Opening an account is fully digital in the app or the browser and takes a few minutes. You must be at least 18, live in Switzerland and have a Swiss mobile number. For identification, you scan your ID card, passport or B or C residence permit.
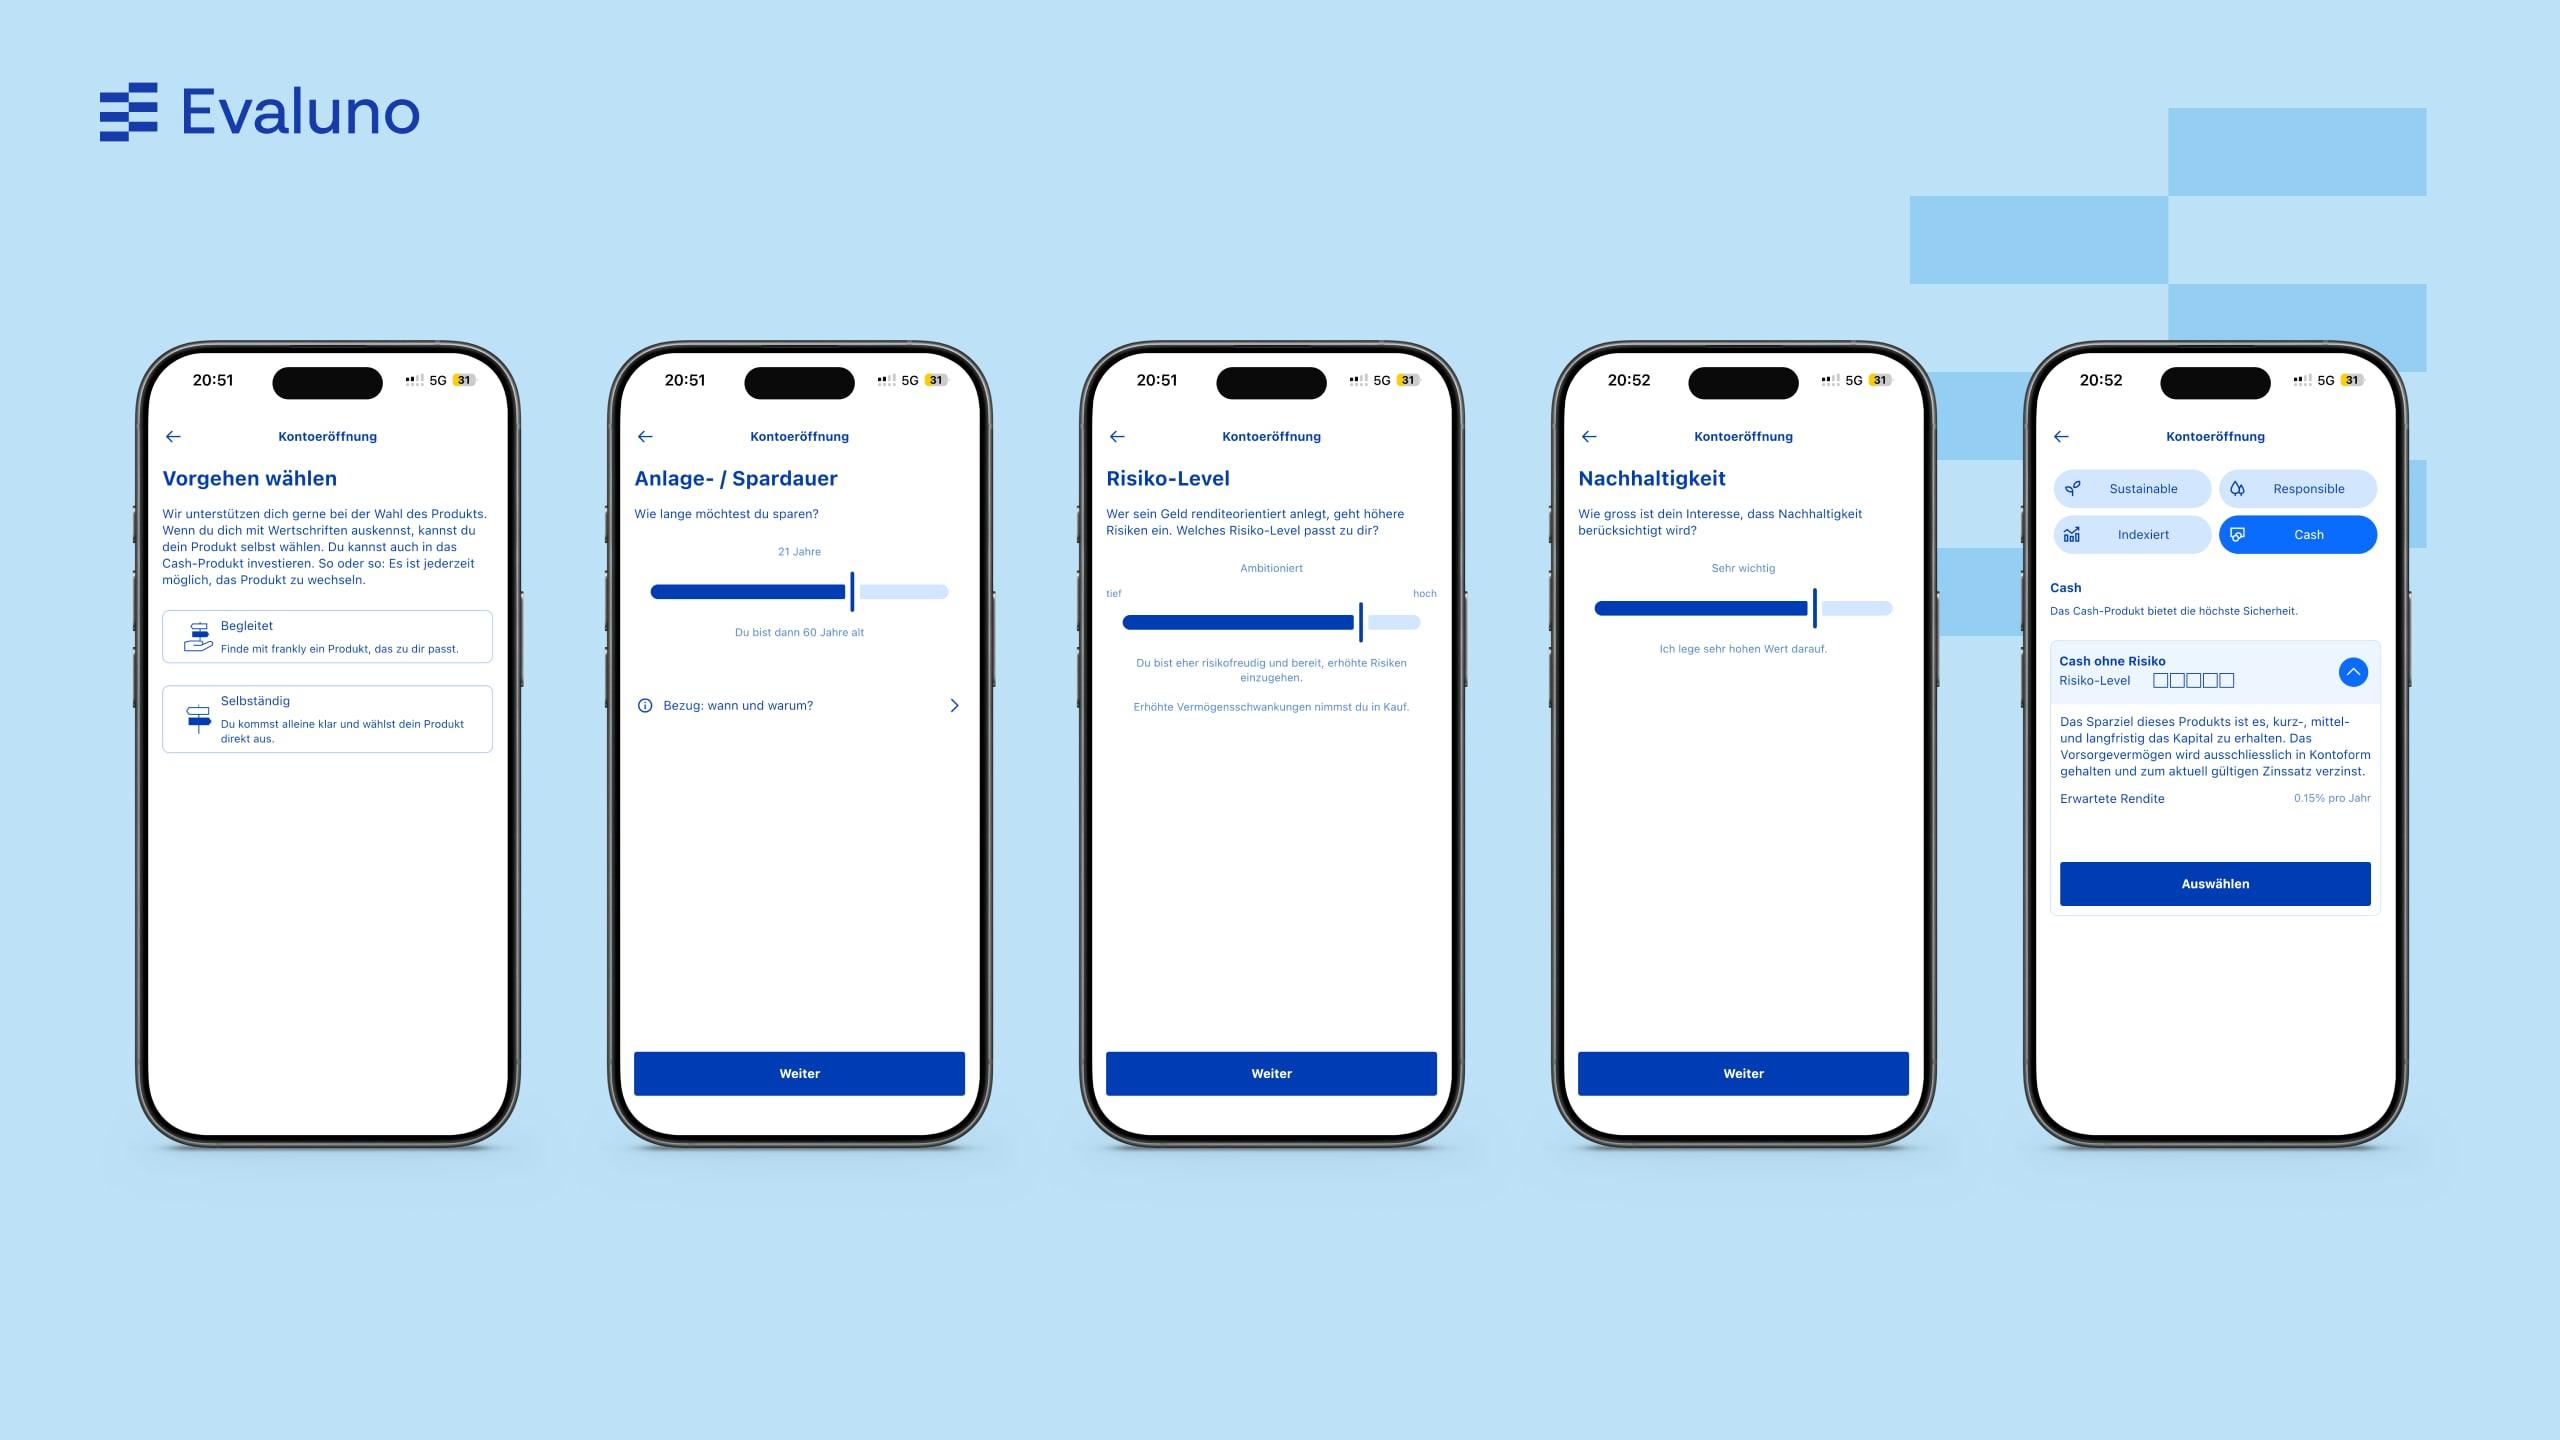
- Download the app or register online at frankly.ch
- Scan your ID and confirm your identity
- Choose your approach: guided or on your own
- Enter the investment horizon, risk level and sustainability, then choose the investment product
- Enter the promo code and transfer your first payment
Switching your pillar 3a to frankly
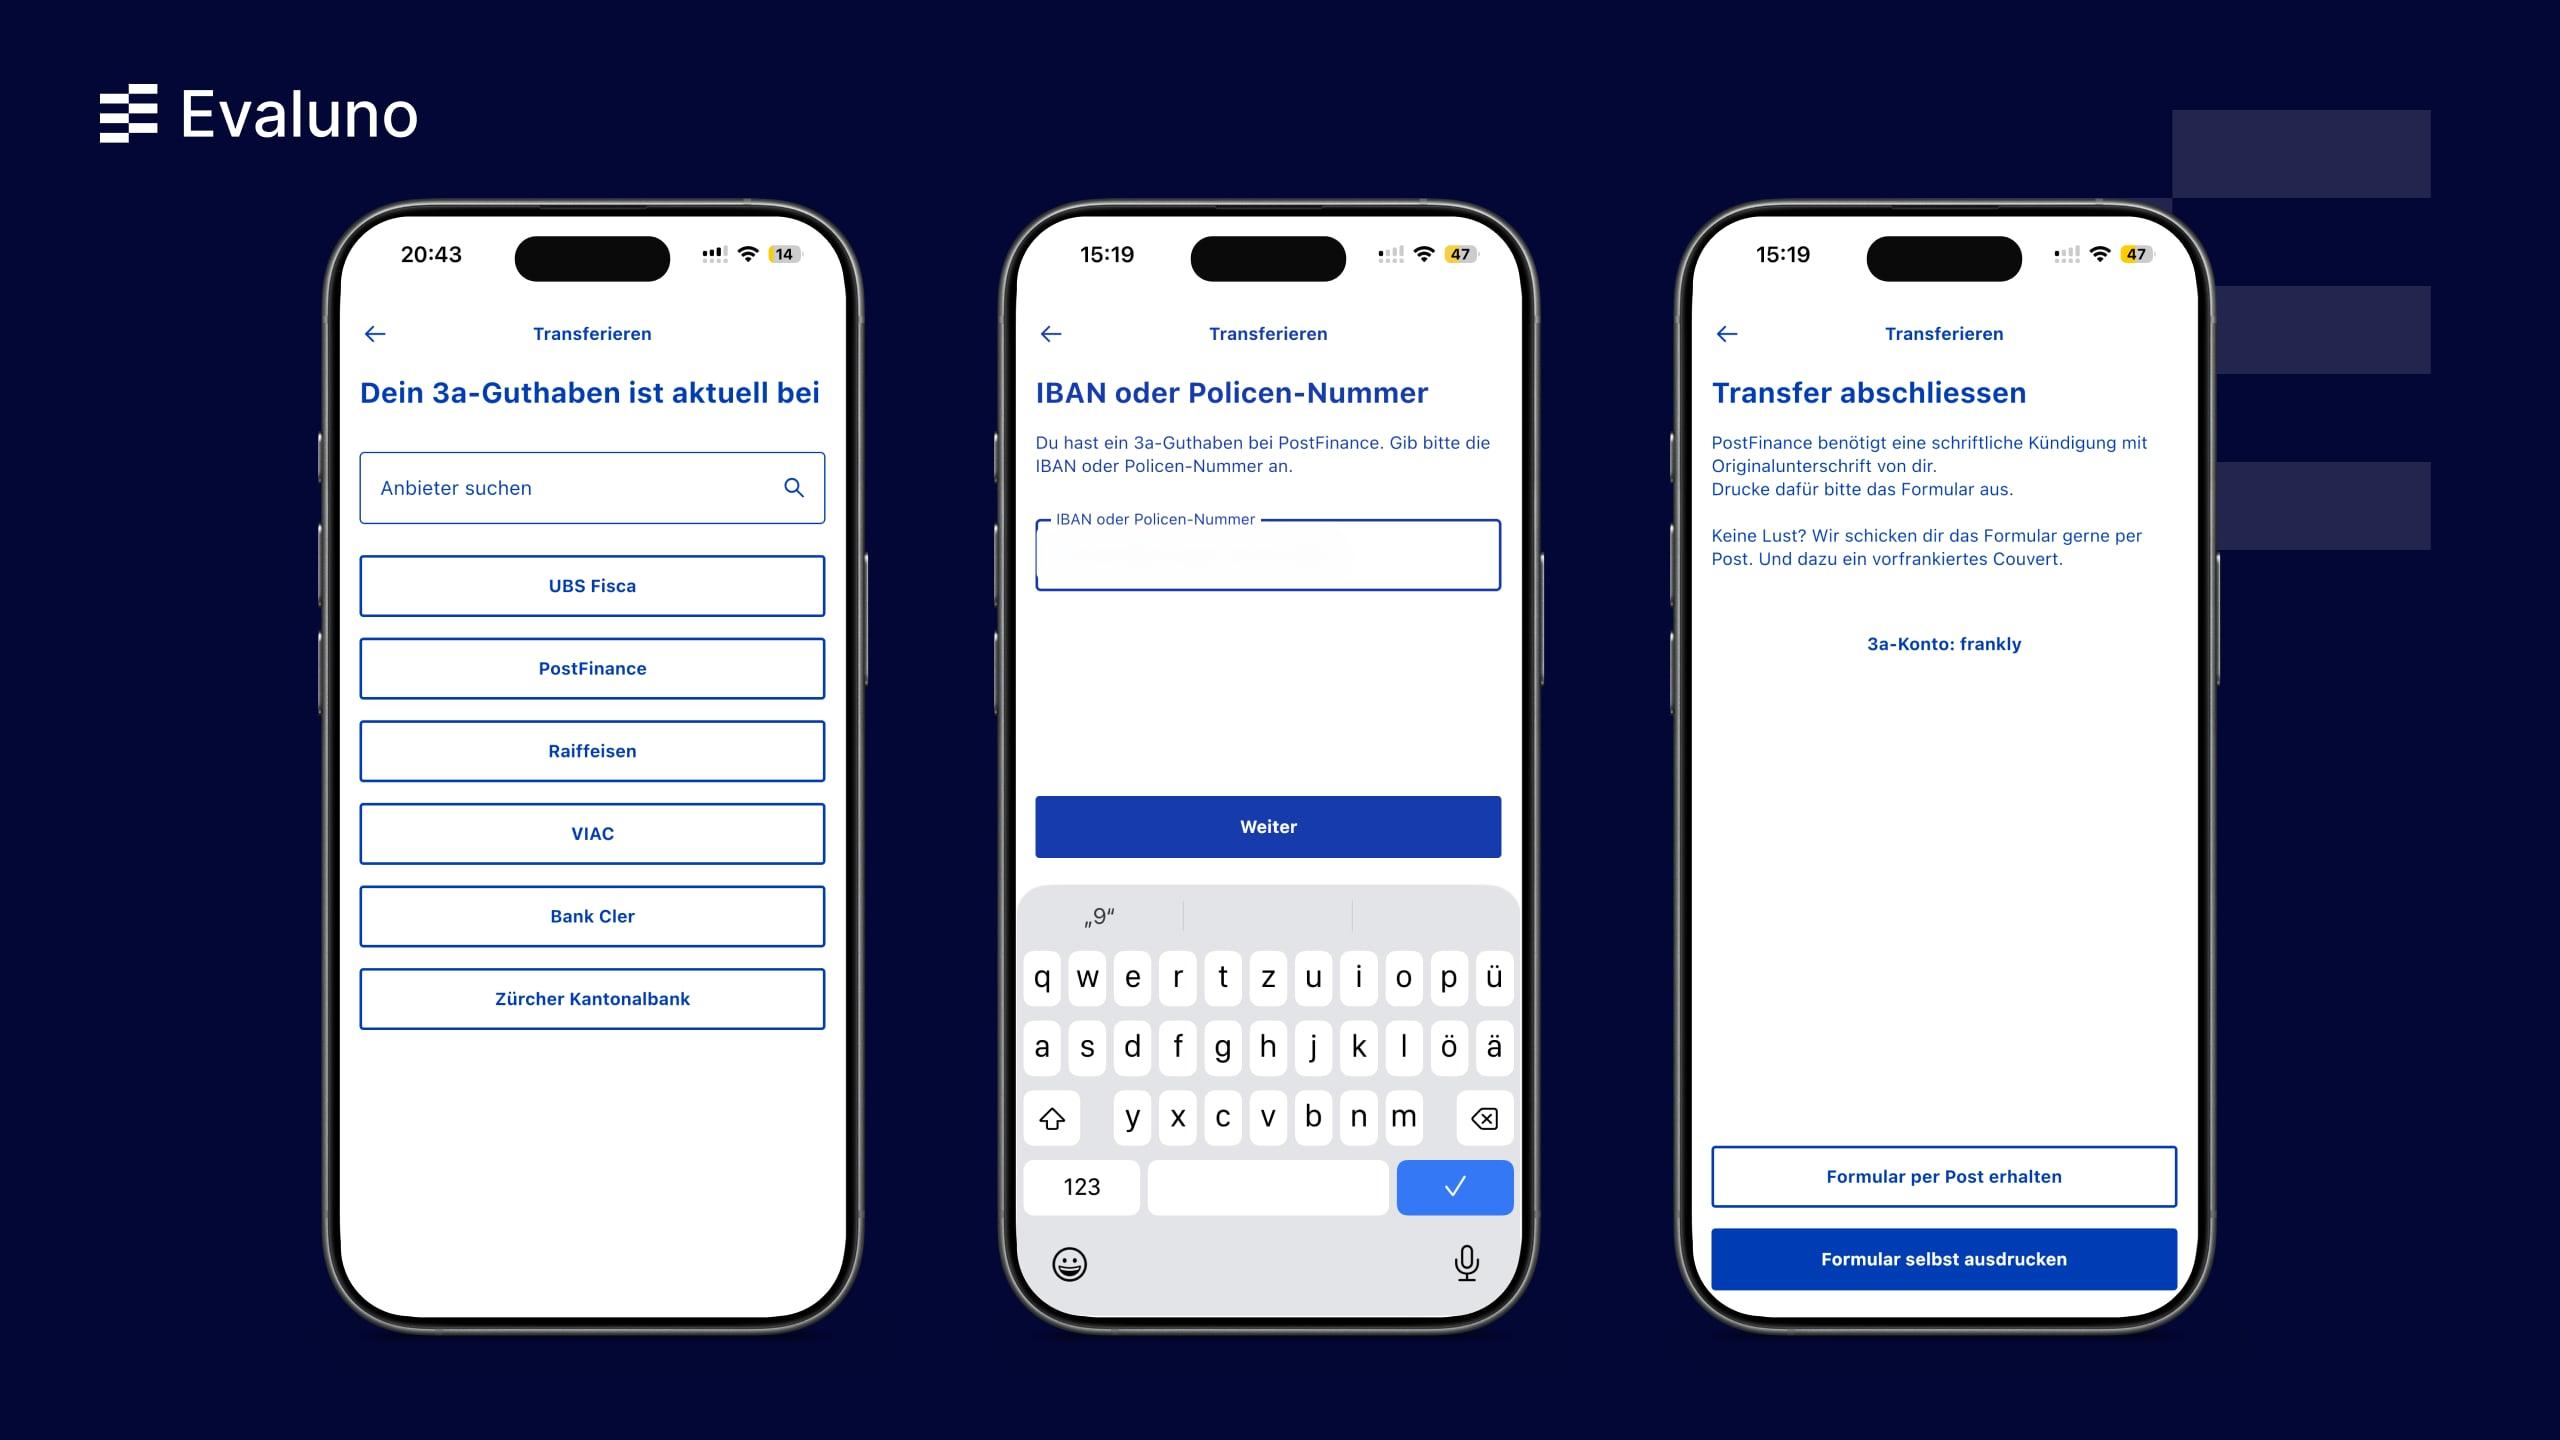
You start the switch in the frankly app with «Transfer to frankly». frankly creates a form, which you sign and send to your current provider. frankly refunds your old provider’s charges for the sale, closing and transfer as a discount on the All-in fee if you send the statement to support. An existing balance can only be transferred in full and does not count towards the year’s maximum amount. You’ll find general tips on switching in the guide to switching your pillar 3a.
Pros and cons of frankly
Pros
- Advantage: Attractive fees
- Advantage: Clear app, also in the browser
- Advantage: Simple, fully digital account opening
- Advantage: Easy management, strategy switch directly in the app
- Advantage: Up to 5 accounts, each with its own strategy
Cons
- Disadvantage: Maximum 95 % equities
- Disadvantage: Swisscanto products only, no custom strategy
- Disadvantage: Product costs and charges come on top
- Disadvantage: Withdrawals and transfers by form and post
Verdict: is frankly 3a worth it?
Yes, if you’re looking for a simple and secure pillar 3a and having Zürcher Kantonalbank behind it matters to you. frankly offers solid Swisscanto funds, an interest-bearing 3a account with no fee and a clear app, also in the browser. Compared with the market as a whole, the costs are attractive. The frankly products also perform very well on returns compared with the market. The drawbacks are the maximum equity share of 95 % and the lack of a custom strategy. If you want up to 99 % equities or a strategy you put together yourself, you’re better off with finpension or VIAC.
Frequently asked questions about frankly
Yes, for anyone looking for a simple pillar 3a with Zürcher Kantonalbank behind it. At 0.43 to 0.47 % a year, the costs are attractive compared with the market as a whole, and the products have performed very well over the past five years.
Depending on the product, frankly costs 0.43 to 0.47 % a year, including product costs. This includes the All-in fee of 0.43 %, which applies only to invested money. You pay nothing on uninvested money. Index products also incur issue and redemption charges.
Yes. With the code Evaluno35, you get a CHF 35 credit on your fees. You enter it when opening your account under «Redeem voucher», no later than 48 hours after opening your first account. The code is valid for new customers until 31 December 2026.
The two are close: VIAC costs 0.41 to 0.44 % a year depending on the strategy, frankly 0.43 to 0.47 %. Over five years, the best products were level, frankly Extreme 95 Responsible with +44.5 % and VIAC Global Nachhaltig 100 with +44.4 %. VIAC allows up to 99 % equities and a custom strategy, while frankly offers Zürcher Kantonalbank as a partner and actively managed Swisscanto funds.
At 0.39 % a year, finpension is cheaper and allows up to 99 % equities. On returns, frankly was ahead over five years: Extreme 95 Responsible gained 44.5 %, finpension’s best product, Global 100, 37.0 %.
Yes. frankly is the digital pillar 3a of Zürcher Kantonalbank. The contractual partner is ZKB’s Sparen 3 pension foundation, and the funds come from Swisscanto, ZKB’s fund management company.
No. frankly is open to anyone who lives in Switzerland, is at least 18 and has a Swiss mobile number. You don’t need an account with Zürcher Kantonalbank. If you are a ZKB customer with an eBanking contract, you can also see your frankly assets in your e-banking.
Yes. Your contractual partner is the Sparen 3 pension foundation of Zürcher Kantonalbank. Invested money is held in Swisscanto investment products, which are protected in the event of bankruptcy, and uninvested money with ZKB, backed by the Canton of Zurich’s state guarantee. The value of the securities can fluctuate.
It depends on the investment product. To 30 September 2026, the products with the highest equity share (Extreme 95) gained 16.7 to 20.3 % over one year, 51.0 to 56.0 % over three years and 41.7 to 44.5 % over five years. You’ll find the figures for all 15 frankly products in the Evaluno pillar 3a fund comparison.
That depends on your investment horizon and your risk capacity. If you have more than ten years until you withdraw the money, a high equity share such as Strong 75 or Extreme 95 is often a good fit. In the five years to 30 September 2026, the Responsible products were slightly ahead of the Index products at every comparable level.
Yes, if you want it to be. The Sustainable product line invests on strictly sustainable lines, and Responsible is aligned with the Paris climate goal. The Index products do not take sustainability into account specifically.
Fully digitally in the app or the browser: you scan your ID, choose an investment product and you’re done in a few minutes. There is no minimum amount, you can pay in from as little as CHF 1.
You start the switch in the frankly app with «Transfer to frankly» and send the signed form to your current provider. frankly refunds its charges for the sale, closing and transfer as a discount on the All-in fee.
Up to five. With several accounts, you can later spread your withdrawals over several years and save tax. However, an existing balance cannot be split across several accounts when you switch.
In the «Mailbox» of the frankly app or the web version. The tax certificate for the previous year is available there at the beginning of January, one for each account.
A withdrawal is only possible for legal reasons, for example on retirement, for a home you live in yourself, when becoming self-employed or when emigrating. In the app, you choose the withdrawal option for the account and send the signed form by post. Early withdrawal for home ownership is included in the All-in fee.
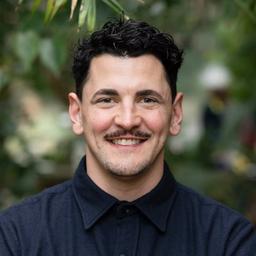
Silvan Forster is an author and co-founder of Evaluno.ch. He studied business administration with a specialisation in Banking & Finance and, with around ten years in the financial industry, knows financial products and their fee structures first-hand. He is a frankly customer himself and wrote this review using his own account.
More about Silvan ForsterSource: provider websites, product documents and direct information from providers, as of .
All information without guarantee. Past performance is no indicator of future results, prices can fluctuate. Evaluno earns a commission when an account is opened through some of these links. This does not change the results or their ranking. Evaluno’s methodology
Related topics
Pillar 3a fund comparison
373 pillar 3a funds compared: costs from 0.10 % to 1.71 %, five-year performance, filterable by equity share. Compare independently.
View comparison
Pillar 3a account comparison
All 106 Swiss pillar 3a accounts compared by interest rate: cantonal banks, UBS, Raiffeisen, PostFinance, Migros Bank and more. Compare now.
View comparisonLegal disclaimer
Evaluno does not provide investment, legal or tax advice and is no substitute for personal advice.