

VIAC 3a at a glance
| Provider | VIAC AG, Basel; contractual partner: Terzo Pension Foundation of Bank WIR |
| On the market since | 2017 |
| Costs per year | 0.41 to 0.44 % including product costs, from 0.16 % without bonds, no fee on the 3a account |
| Investment products | 15 strategies (Global, Global Sustainable, Switzerland) with 20 to 99 % equities, funds from Swisscanto or UBS, plus Account Plus and the 3a account |
| Number of accounts/strategies | up to 5 portfolios, each with its own strategy |
| Access | App (iPhone, Android) and web app |
| Languages | German, French, Italian and English |
| Assets under management | over CHF 3 bn in pillar 3a |
| Other products | VIAC Vested benefits, VIAC Invest, VIAC Life, VIAC Mortgage |
| Promo code | EVO25V: CHF 2'000 fee-free for life |
Data as of 18.11.2026. Sources: VIAC app (screenshots from November 2026), viac.ch (pages on pillar 3a, fees and strategies, FAQ, accessed on 18.11.2026), strategy costs: Evaluno pillar 3a fund comparison (data as of 30.9.2026). No guarantee.
What is VIAC 3a? The pillar 3a with Bank WIR
VIAC 3a is the digital pension offering of VIAC AG, based in Basel. The company has existed since 2017, and the app came onto the market in the same year. You open and manage your pillar 3a via the app or in the web app on your computer.
Your contractual partner is the Terzo Pension Foundation of Bank WIR in Basel. The money in the 3a account is held at Bank WIR, and the securities are kept in custody by UBS or Zürcher Kantonalbank. Besides pillar 3a, VIAC also offers vested benefits accounts (VIAC Vested benefits), the wealth management service VIAC Invest as well as VIAC Life and VIAC Mortgage. This review covers VIAC 3a only. Over 175'000 customers use VIAC.
VIAC review: tested with a real pillar 3a account
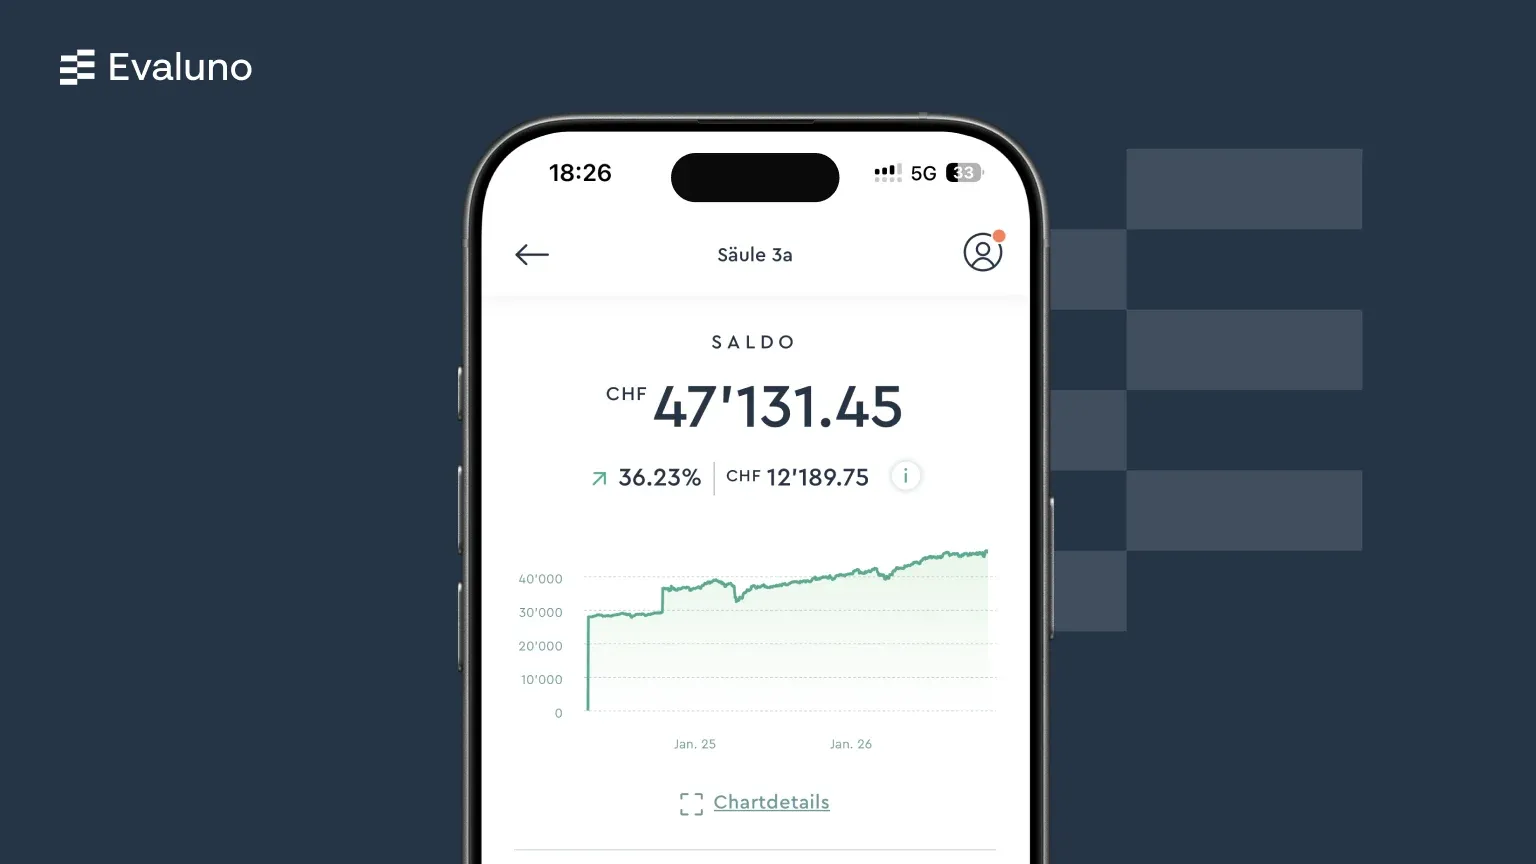
Evaluno tests VIAC with a real 3a account that has been paid into since 2024 in the Global 100 strategy with Swisscanto funds. The result: the costs are low, the returns are convincing and the app is clear.
VIAC 3a test result at a glance
| Criterion | Rating | Reason |
|---|---|---|
| Costs | very good | 0.41 to 0.44 % a year including product costs; no fee on the 3a account |
| Investment range | very good | 15 strategies with up to 99 % equities, plus your own strategy from around 80 funds and ETFs |
| Returns | very good | Global Sustainable 100 with one of the best 5-year returns in the Evaluno comparison |
| App and ease of use | very good | Clear, with a securities overview, transactions and chat; also in the browser |
| Account opening | very good | Quick and easy: fully digital, in less than ten minutes |
How Evaluno tests pillar 3a providers
The basis is an ordinary customer account at VIAC: opened privately, paid into with our own money and not provided by VIAC. Fees, products and processes come from the app (screenshots from November 2026) and from viac.ch. Evaluno compares costs and returns with over 350 pillar 3a funds and investment strategies (data as of 30.9.2026). Evaluno rates all pillar 3a providers on the same five criteria.
VIAC 3a fees: how much does VIAC cost?
VIAC 3a costs 0.41 to 0.44 % a year depending on the strategy, including product costs. The administration fee is only charged on the invested portion, and a fee cap limits it to 0.40 % at most; the costs of the funds come on top. If you choose a strategy without bonds, the rest stays in the 3a account, and with a low equity share the costs fall to as little as 0.16 %. Money in the 3a account stays fee-free, and the 3a account and Account Plus cost nothing.
Interest on the VIAC 3a account: 0.20 % with no fee
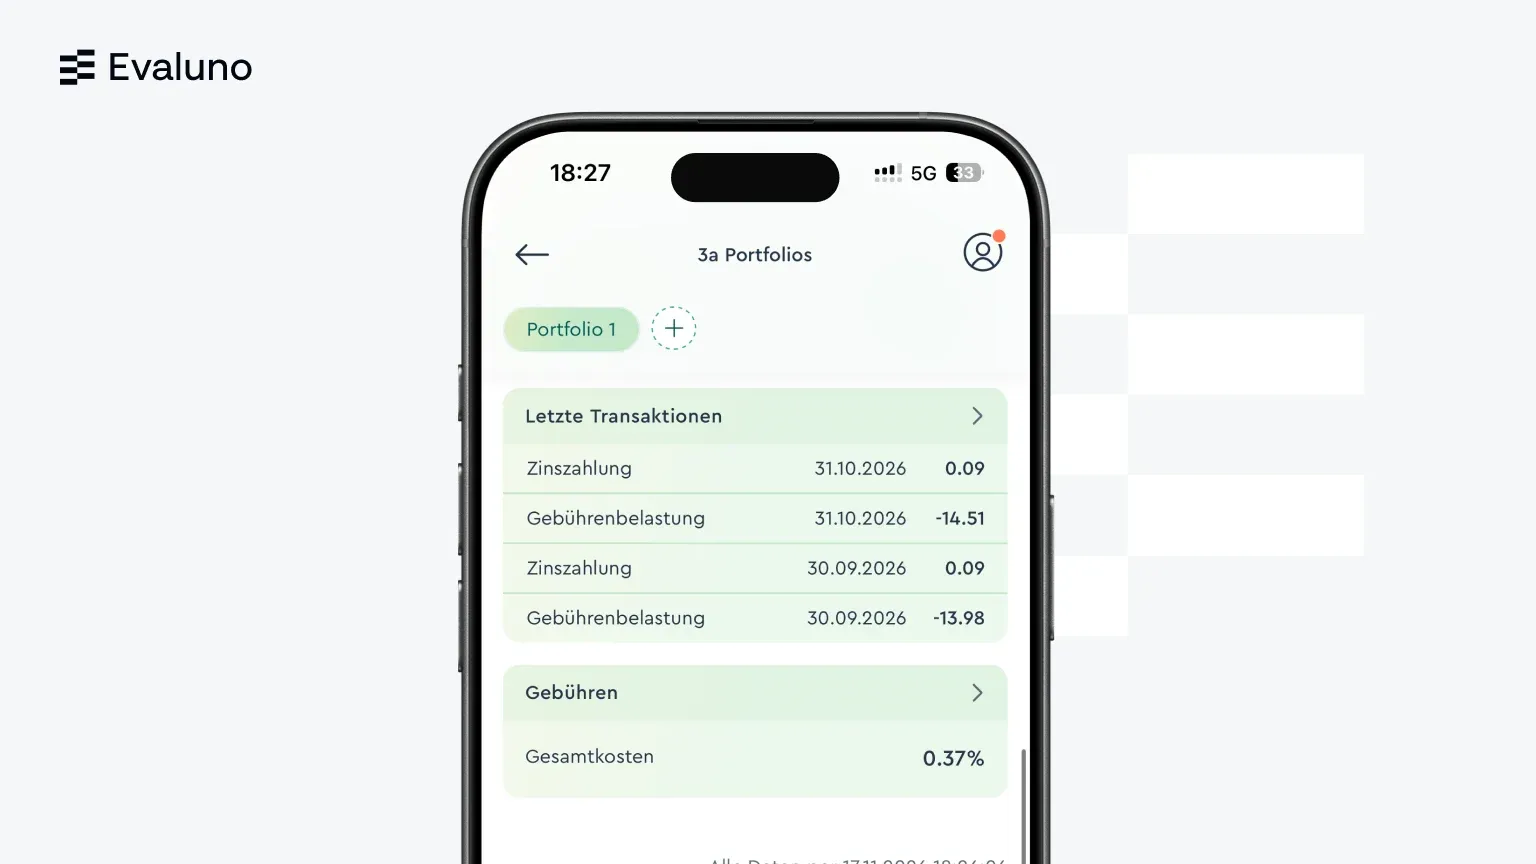
If you do not invest your money, you choose the 3a account at VIAC. It has no fee and currently pays 0.20 % interest. In the strategies, too, there is no fee on the portion held in the account. In the test account with Global 100, the app shows total costs of 0.37 % a year.
What the VIAC fee includes and what it does not
- Included: account opening, management, purchases and sales, rebalancing, deposits and withdrawals, transfer to another provider
- Not included: early withdrawal for home ownership CHF 300 (free if financed through Bank WIR), currency costs of up to 0.20 % per purchase for funds in foreign currencies, on average less than 0.05 % a year, stamp duty on ETFs in your own strategy
Example: how much VIAC 3a costs per year
VIAC calculates the fee as a percentage of the invested assets, so it rises with your wealth. With CHF 50'000 you pay CHF 205 to 220 a year with a ready-made strategy, depending on the strategy. For comparison: at finpension the same assets cost CHF 195 to 205 a year, at frankly CHF 215 to 235. With the code EVO25V, CHF 2'000 of your assets also stay fee-free, which saves around CHF 8 a year.
| Assets | From 0.41 % a year | Up to 0.44 % a year |
|---|---|---|
| CHF 10'000 | CHF 41 | CHF 44 |
| CHF 50'000 | CHF 205 | CHF 220 |
| CHF 100'000 | CHF 410 | CHF 440 |
VIAC 3a strategies and funds: Global, Global Sustainable or Switzerland?
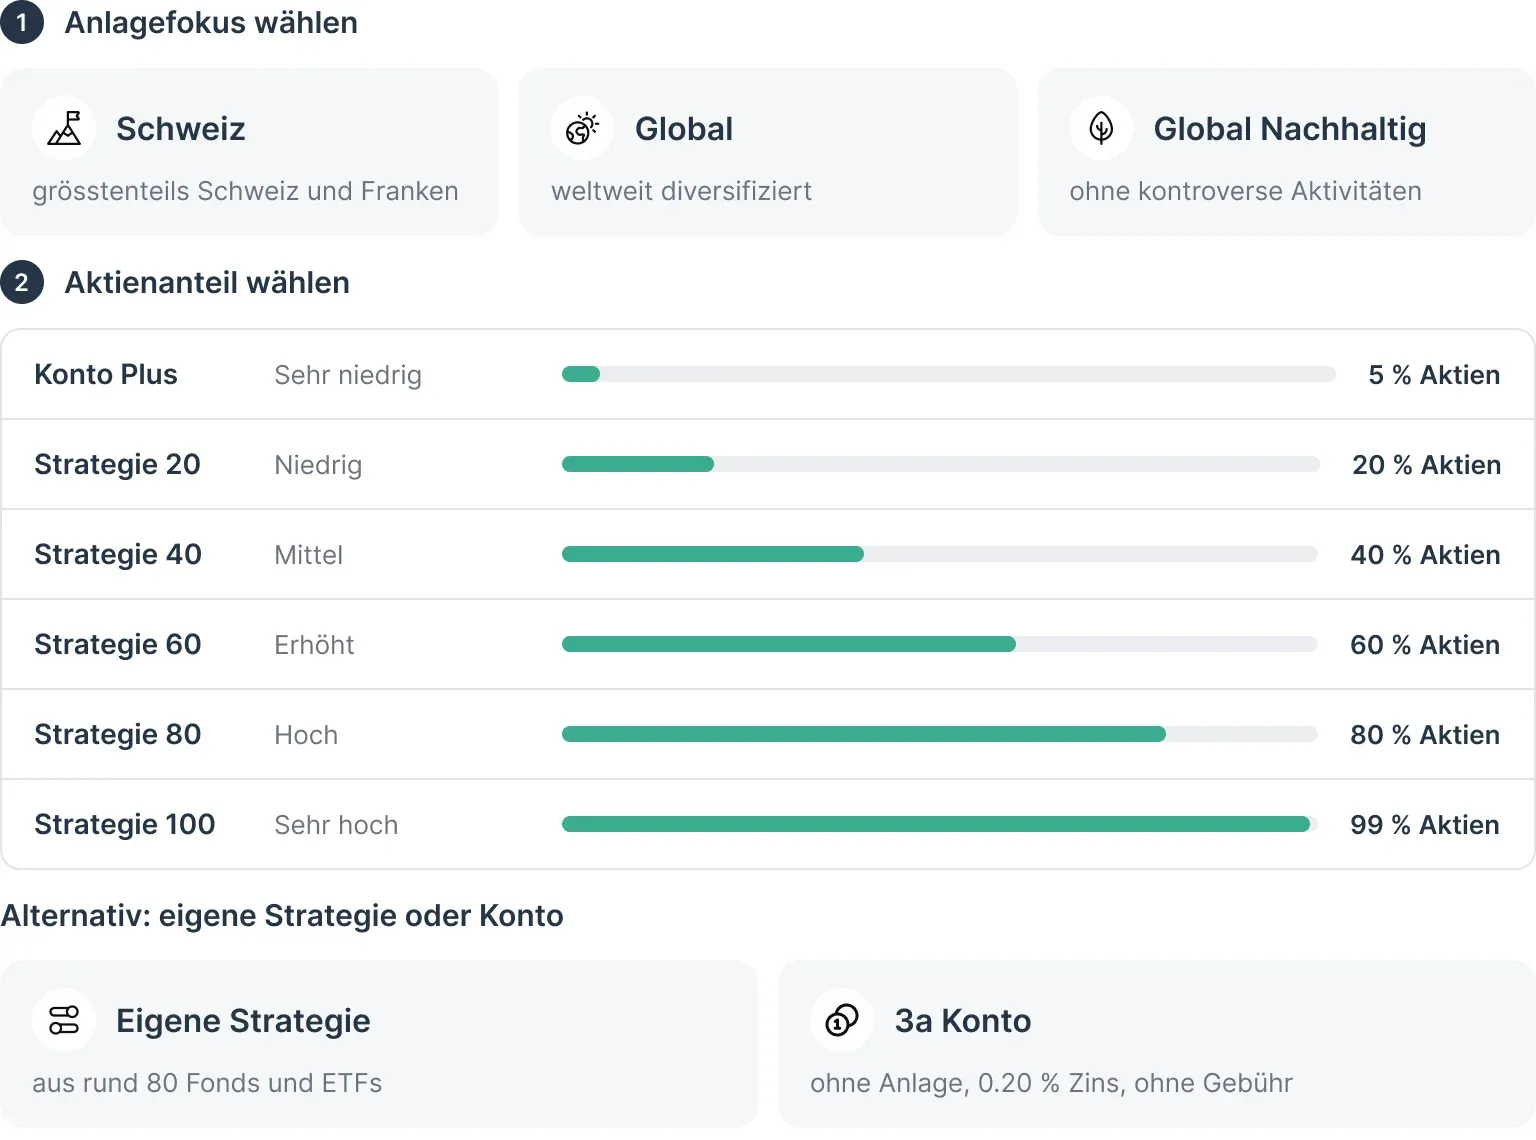
VIAC 3a offers 15 ready-made strategies with the Global, Global Sustainable or Switzerland investment focus, plus your own strategy from around 80 funds and ETFs. At VIAC, you first choose an investment focus and then the equity share. Global invests broadly across the world’s stock markets, Global Sustainable excludes companies with controversial activities, and Switzerland invests mostly in Switzerland and in Swiss francs. The equity share comes in five levels, and the number in the name shows it rounded: Global 100 contains 99 % equities.
Every strategy is available with funds from Swisscanto or UBS (formerly Credit Suisse). You also choose whether the portion not invested in equities goes into bonds or stays in the 3a account. Without bonds, this portion earns interest in the 3a account and incurs no administration fee, which makes the strategy cheaper. VIAC implements the strategies with low-cost index funds and ETFs. If you want more control, you put together your own strategy from around 80 funds and ETFs, even with up to 5 % in bitcoin. When you open an account, the app asks about your goal, expected return, risk tolerance and financial knowledge, and then suggests an investor type and a strategy.
All 15 VIAC 3a strategies at a glance
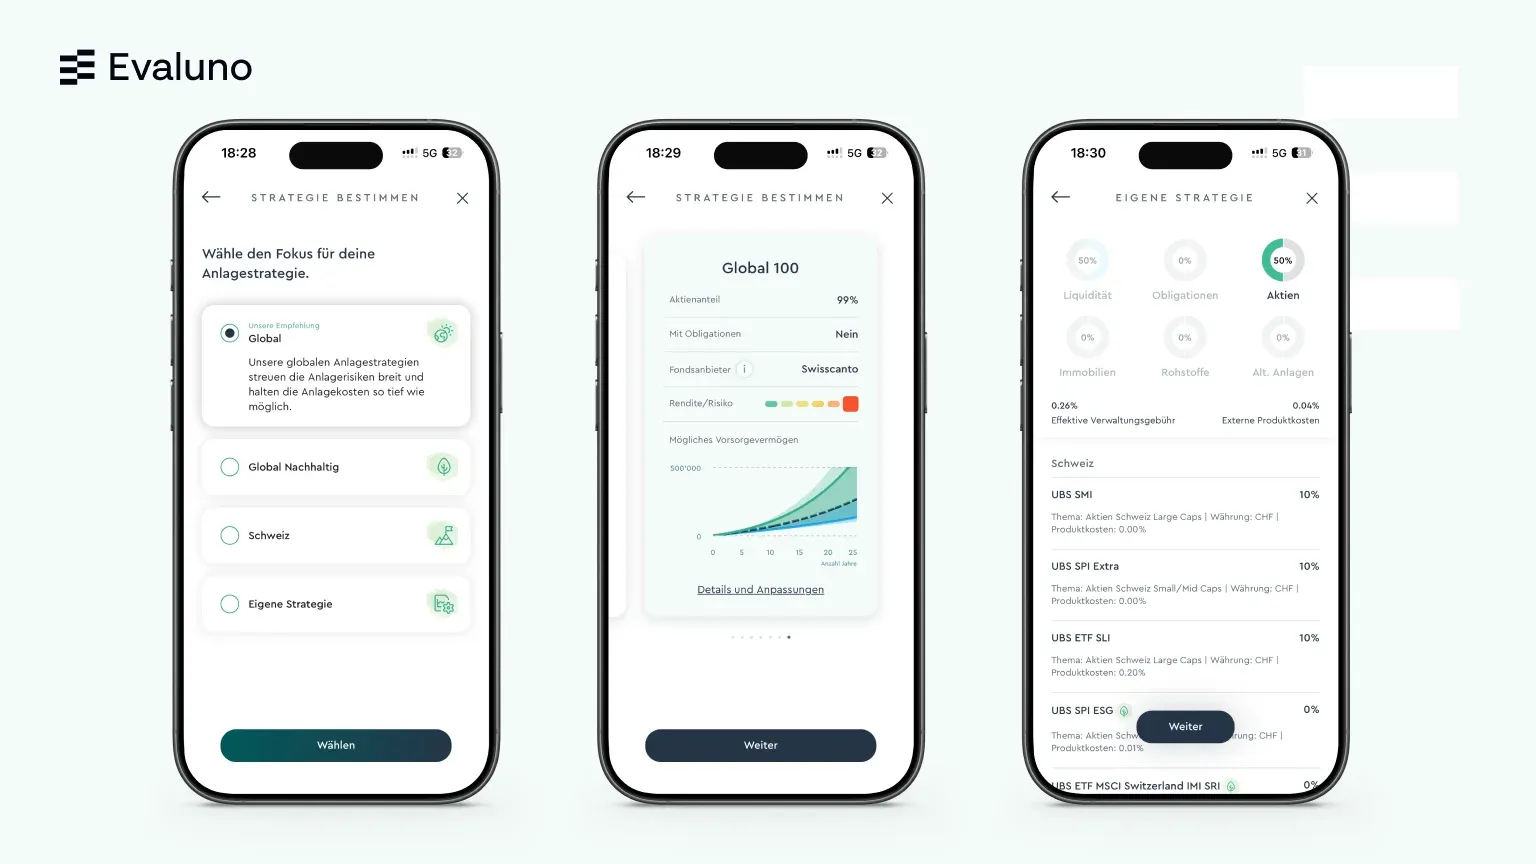
In the VIAC app, you see for each strategy the equity share, the fund provider, the return and risk rating and a forecast for your pension assets. You change your strategy in the app. You can also run up to five portfolios, each with its own strategy.
Global, Global Sustainable or Switzerland: what is the difference?
Global spreads the equities across the world’s stock markets but still contains many Swiss shares, around 40 % in Global 100. Global Sustainable excludes companies with a significant involvement in controversial activities and selects companies according to recognised sustainability criteria. Switzerland invests mostly in Switzerland and in Swiss francs across all asset classes, around 75 % in Switzerland 100. If you want no investment risk, you choose the 3a account: no fee and 0.20 % interest.
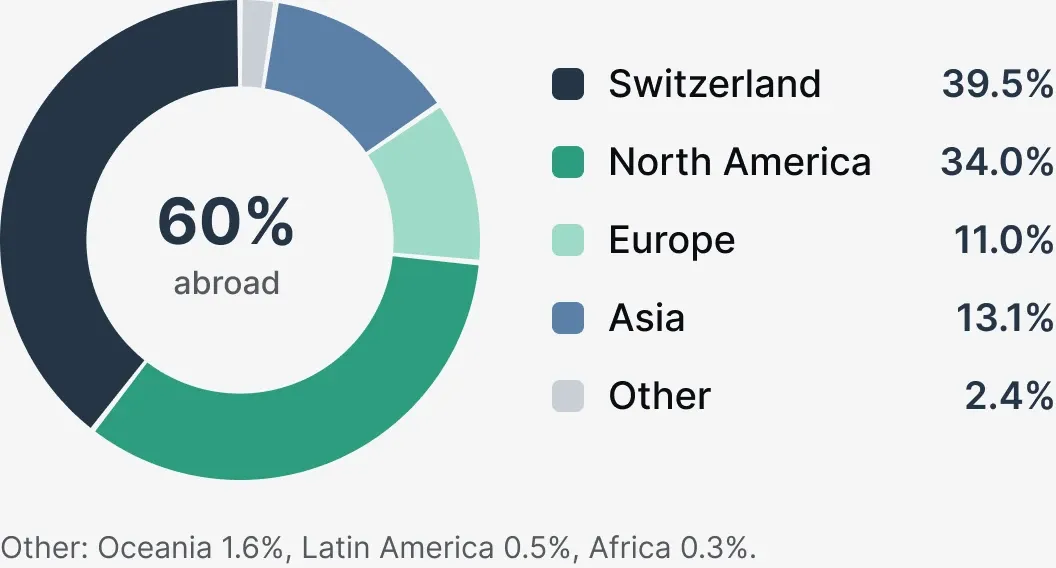
What is in VIAC Global 100? 40 % Swiss shares
VIAC Global 100 invests 99 % in equities, around 40 % of them in Switzerland. That is far more than the name “Global” suggests, because Switzerland makes up only a small fraction of the global stock market. The largest individual holdings are therefore Novartis, Roche and Nestlé, not Nvidia or Apple.
The remaining 60 % is spread mainly across North America (34 %), Asia (13 %) and Europe (11 %). The strategy is implemented with eight index funds from UBS or Swisscanto, without bonds; 1 % is held as cash in the 3a account. The Swiss franc also dominates the currencies, at 40 %.
Regions in VIAC Global 100: 40% Switzerland, 60% abroad
Breakdown of pension assets by region, including 1% cash
Global 100 costs 0.41 % a year and gained 43.8 % in the five years to 30.9.2026.
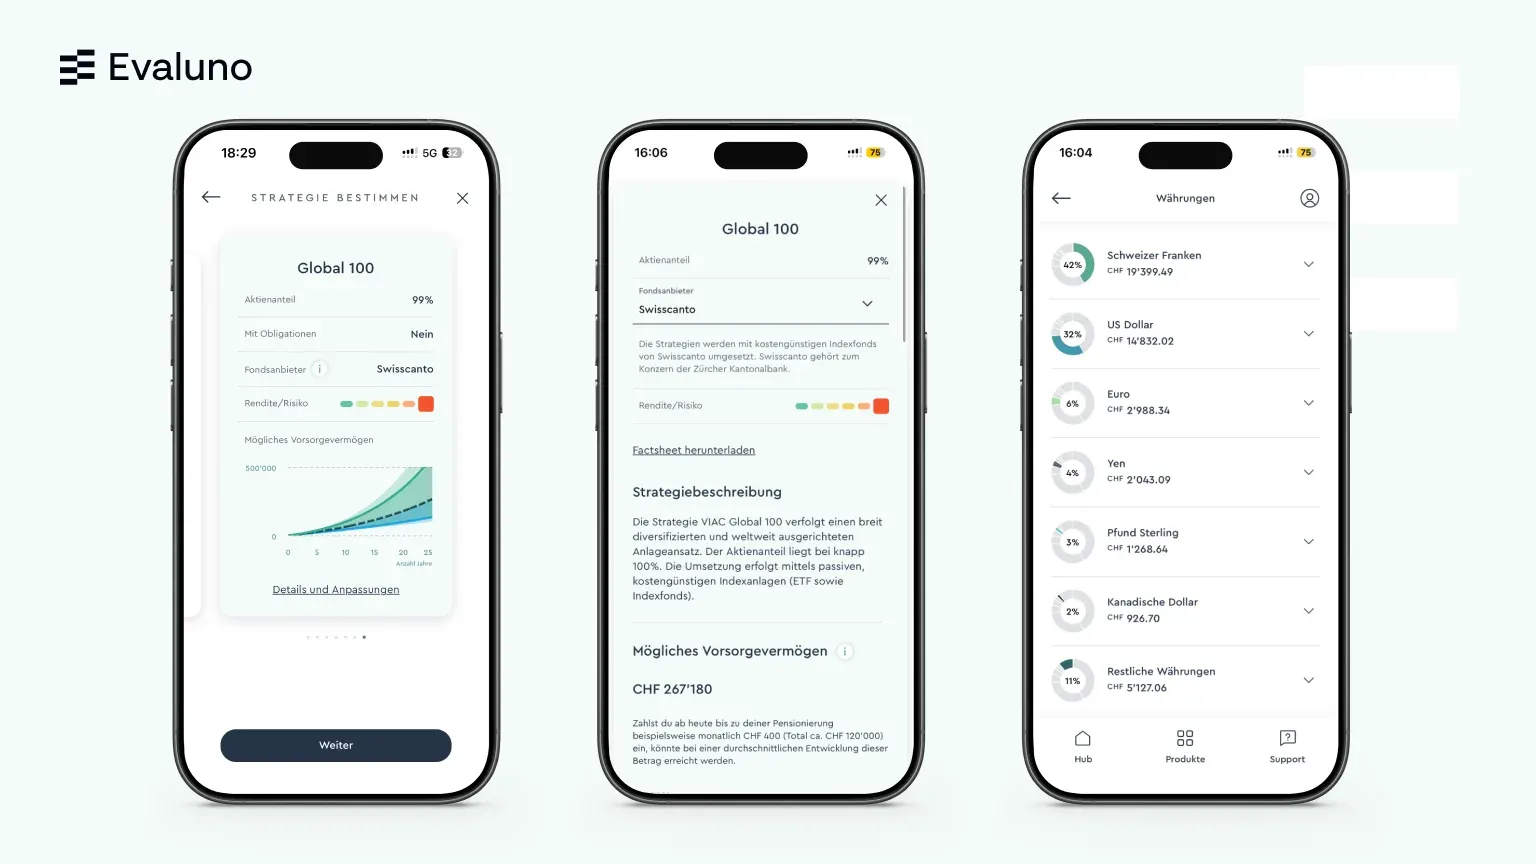
VIAC Global 100 or Global 80: which strategy suits you?
What matters is your investment horizon and how well you can handle fluctuations. Retirement is often decades away, so a high equity share such as Global 80 or Global 100 suits many people. If you need the money in a few years, for example for a home, a low level or Account Plus makes more sense. With up to five portfolios, you can combine both.
VIAC 3a returns and performance: how the strategies compare
How much return you earn with VIAC 3a depends mainly on the equity share. In the five years to 30.9.2026, Global Sustainable 100 gained 44.4 %, Global 100 43.8 %, Global 80 40.9 %, Global 60 33.8 %, Global 40 25.2 % and Global 20 18.2 %. Over five years, Global was ahead of Switzerland at every level, at level 100 for example with 43.8 % against 32.6 % for Switzerland 100. Except at level 100, Global was also ahead of Global Sustainable. Over one year, Global Sustainable 100 had the best performance of all pillar 3a products in the Evaluno comparison.
VIAC Global 100 performance: among the top 10 in the Evaluno comparison
Up to 30.9.2026, VIAC Global 100 returned +20.8 % over one year, +53.3 % over three years and +43.8 % over five years. Over five years, VIAC Global 100 is therefore among the ten pillar 3a products with the best returns in the Evaluno pillar 3a fund comparison, which covers 373 funds and strategies from 47 providers. Because of the high equity share of 99 %, however, the value can fluctuate sharply in the meantime.
Performance of all 15 VIAC strategies over 1, 3 and 5 years
The tables show the performance of all 15 VIAC strategies over one, three and five years. This lets you see at a glance how Switzerland, Global and Global Sustainable differ at the same equity share.
| Level | Equities | Switzerland | Global | Global Sustainable |
|---|---|---|---|---|
| 100 | 99 % | +17.8 % | +20.8 % | +22.5 % |
| 80 | 80 % | +15.9 % | +17.9 % | +18.9 % |
| 60 | 60 % | +11.8 % | +13.3 % | +13.9 % |
| 40 | 40 % | +7.9 % | +8.8 % | +8.9 % |
| 20 | 20 % | +3.8 % | +4.4 % | +4.4 % |
| Level | Equities | Switzerland | Global | Global Sustainable |
|---|---|---|---|---|
| 100 | 99 % | +42.8 % | +53.3 % | +54.1 % |
| 80 | 80 % | +43.1 % | +50.9 % | +48.5 % |
| 60 | 60 % | +34.2 % | +40.9 % | +37.5 % |
| 40 | 40 % | +26.0 % | +29.5 % | +27.7 % |
| 20 | 20 % | +18.1 % | +19.8 % | +18.4 % |
| Level | Equities | Switzerland | Global | Global Sustainable |
|---|---|---|---|---|
| 100 | 99 % | +32.6 % | +43.8 % | +44.4 % |
| 80 | 80 % | +33.8 % | +40.9 % | +38.3 % |
| 60 | 60 % | +28.9 % | +33.8 % | +30.1 % |
| 40 | 40 % | +22.8 % | +25.2 % | +23.4 % |
| 20 | 20 % | +16.5 % | +18.2 % | +16.5 % |
Cumulative performance in CHF up to 30.9.2026. Source: Evaluno pillar 3a fund comparison (data as of 30.9.2026). Past returns are no guarantee of future returns.
VIAC vs finpension and frankly: which pillar 3a is better?
In short: VIAC combines low costs with one of the best returns of the past five years and pays interest without a fee on the 3a account. finpension is slightly cheaper, and frankly was level with its best product.
Over five years, the best VIAC product, Global Sustainable 100, gained 44.4 %, almost as much as at frankly (+44.5 %) and clearly more than at finpension (+37.0 %). On costs, VIAC at 0.41 to 0.44 % sits between finpension (0.39 to 0.41 %) and frankly (0.43 to 0.47 %). For the 3a account, VIAC has the edge: as at frankly, there is no fee, and at 0.20 % the interest rate is the highest of the three providers.
If you are looking for good returns, a high equity share and interest on the 3a account, VIAC is the right choice. If you want the lowest costs, finpension is slightly cheaper. Read more in our finpension 3a review and our frankly 3a review, and find all digital pillar 3a providers in the Evaluno pillar 3a fund comparison.
| Criterion | VIAC |  finpension |  frankly |
|---|---|---|---|
| Total costs per year | 0.41 to 0.44 % | 0.39 to 0.41 % | 0.43 to 0.47 % |
| Max. equity share | 99 % | 99 % | 95 % |
| Investment strategies | 15 | 18 | 15 |
| Individual strategy | Yes, around 80 funds and ETFs | Yes, over 130 index funds | No, fixed strategies only |
| Index strategies | Yes | Yes | Yes |
| Sustainable strategies | Yes | Yes | Yes |
| Best 5-year return | +44.4 % | +37.0 % | +44.5 % |
| Best product | Global Sustainable 100 | Global 100 | Extreme 95 Responsible |
| Interest on 3a account | 0.20 % | 0.00 % | 0.15 % |
Total costs per year including product costs, for finpension with the ready-made strategies. Returns over 5 years up to 30.9.2026, in each case for the provider’s best product. Sources: Evaluno pillar 3a fund comparison (strategies, returns and costs of VIAC and frankly, data as of 30.9.2026) and the providers’ websites (finpension costs, equity share, individual strategy and interest on the 3a account, as of November 2026). Past returns are no guarantee of future returns.
Is VIAC safe?
Yes. Your pillar 3a assets are not held by VIAC AG but by the Terzo Pension Foundation of Bank WIR in Basel. The securities are segregated assets, held in custody by UBS or Zürcher Kantonalbank, and do not form part of the bankruptcy estate in the event of bankruptcy. The assets in the 3a account are held at Bank WIR and are privileged up to CHF 100'000.
Securities fluctuate: with a high equity share, your assets can fall significantly at times. You log in with your mobile number and password or with Face ID, and you can also switch on two-factor authentication for logging in. For important changes, VIAC always requires an SMS code.
The VIAC app in everyday use
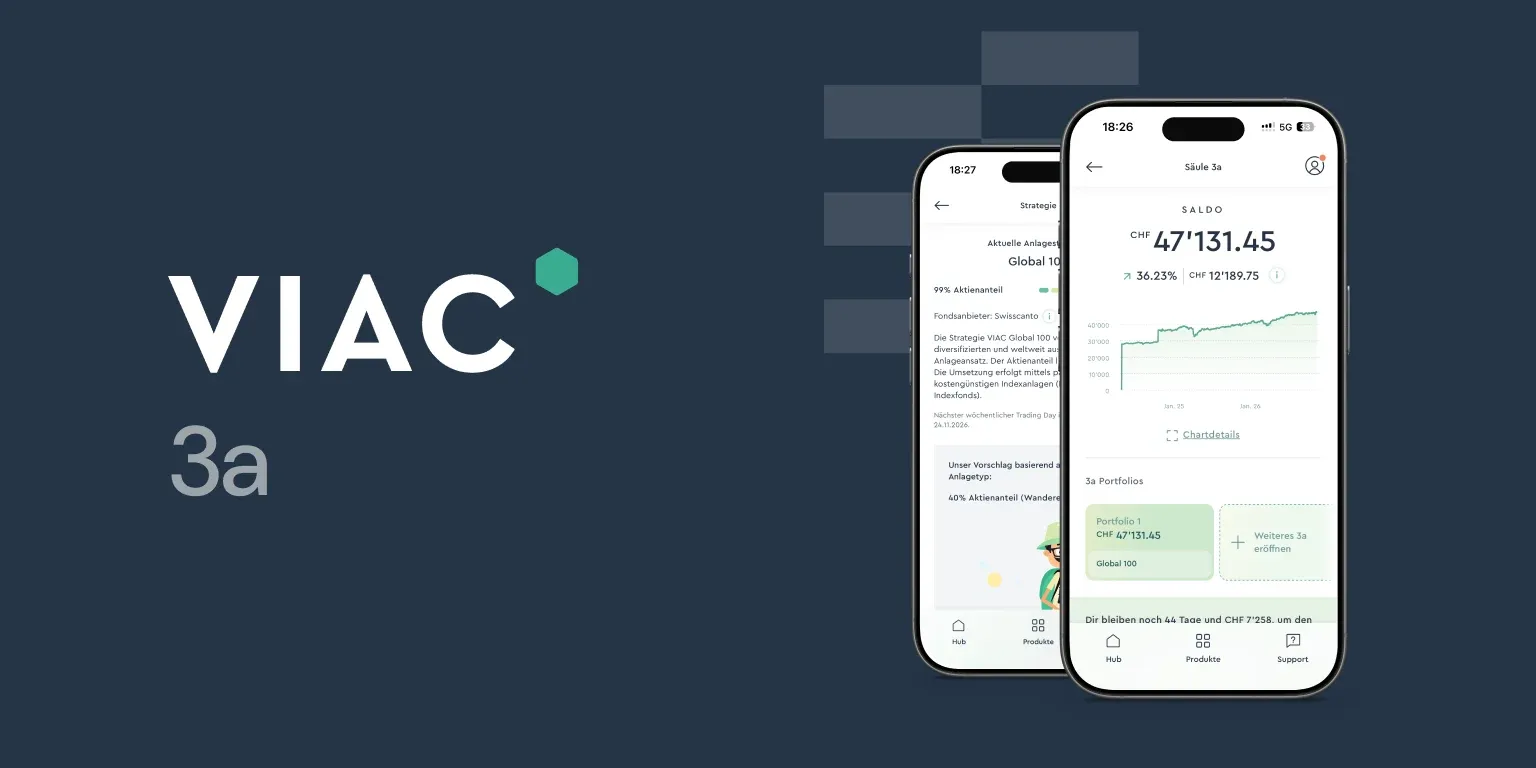
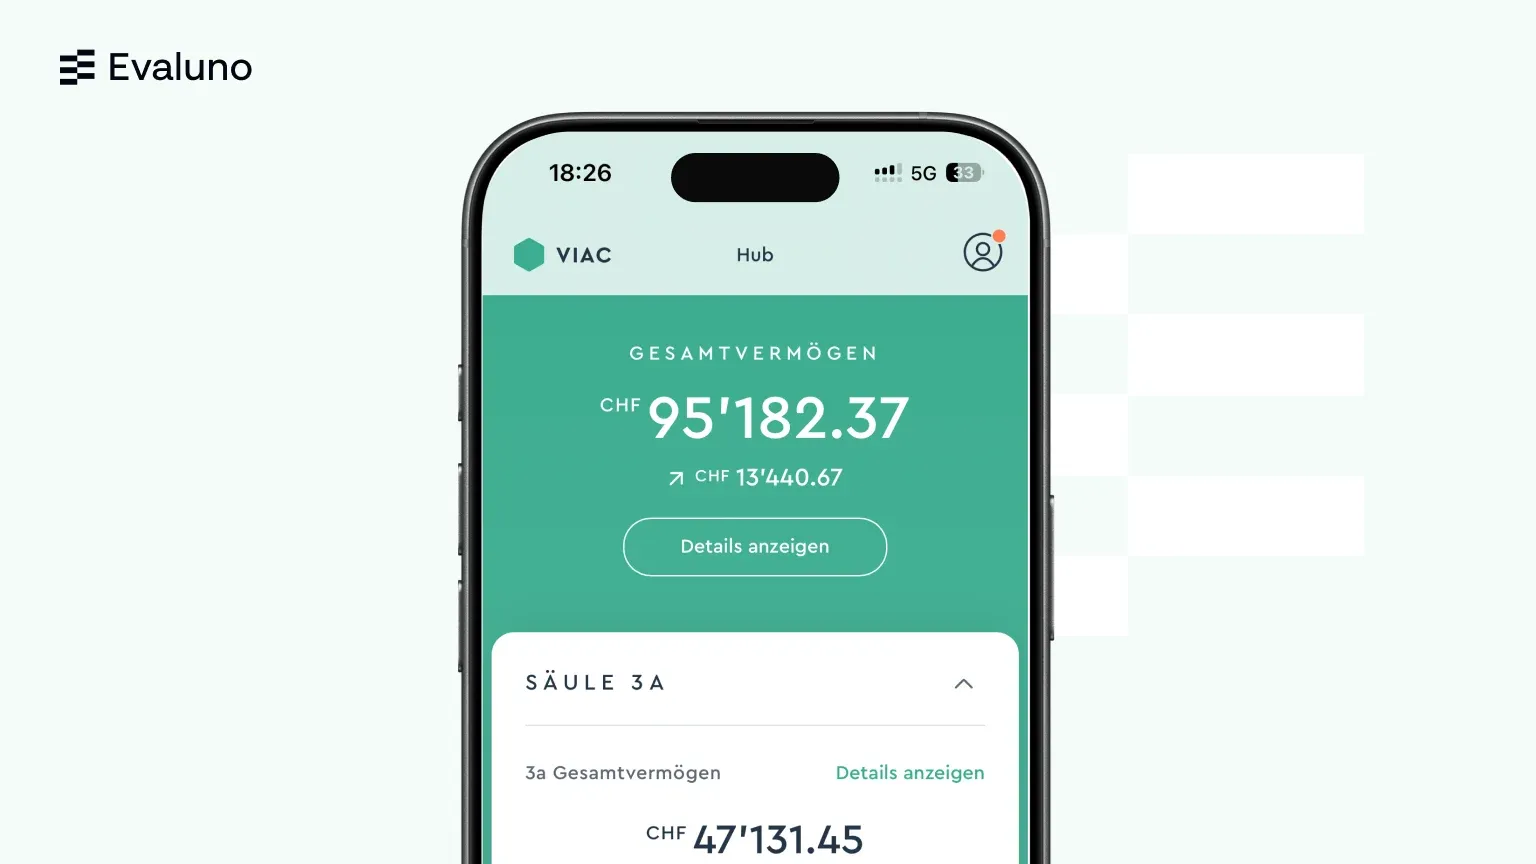
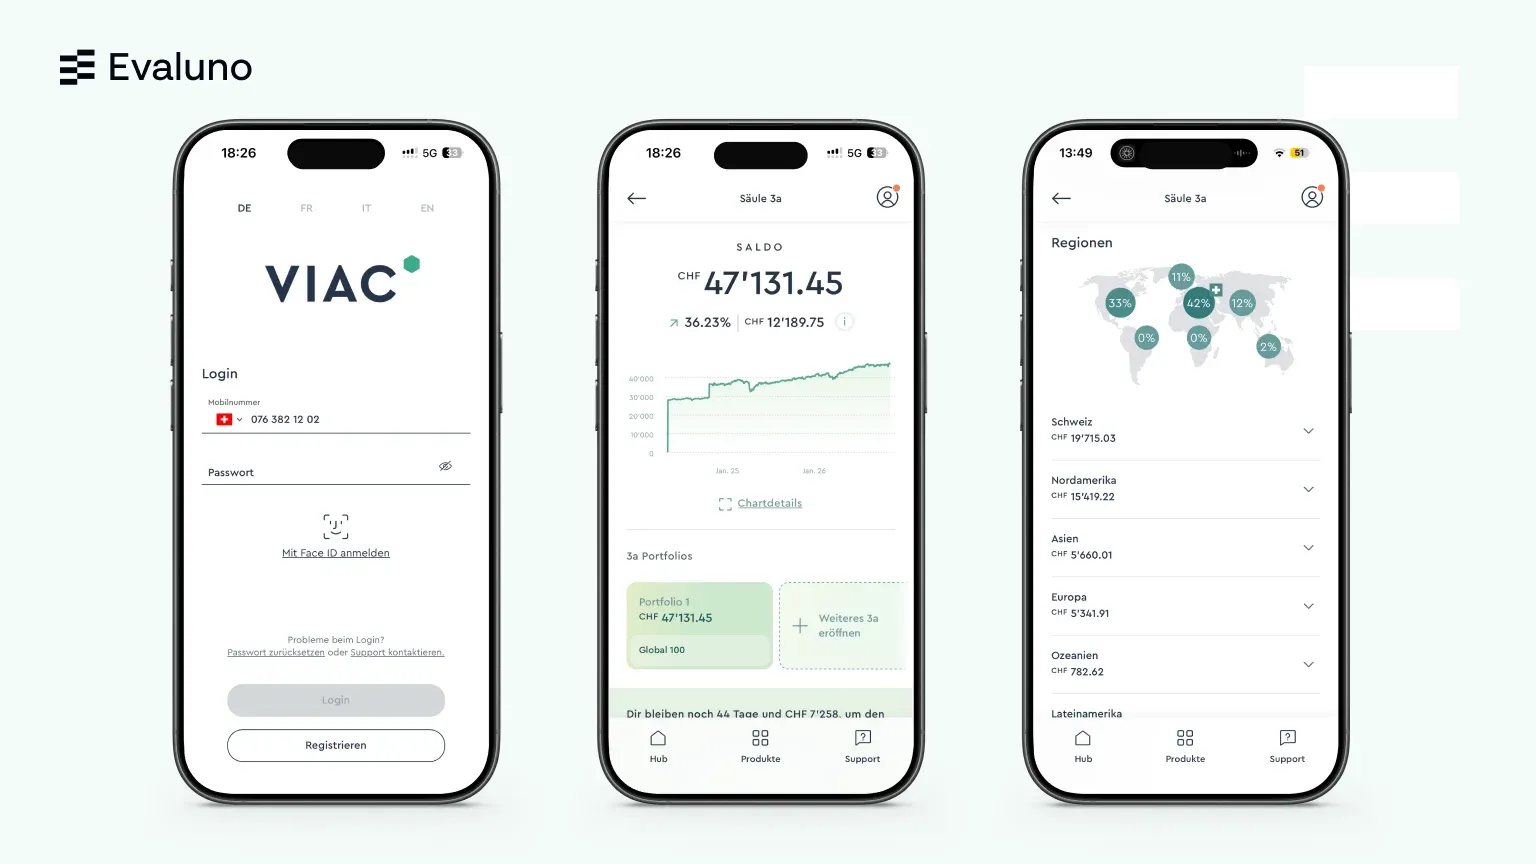
The VIAC app is clear and easy to use. On the Hub screen you see your total assets and pillar 3a with balance, gain and history. In the portfolio you find the strategy, the deposits for the current year, the securities overview with all funds, the breakdown by asset class, region and currency, the latest transactions and the total costs. Trading takes place once a week on Tuesday. The app is available for iPhone and Android. There is no dedicated iPad app: on the iPad, the iPhone app only runs in portrait mode, whereas the web app in the browser adapts to any screen size.
Paying in and catching up on missed years (3a buy-in)
You pay in by bank transfer from your e-banking; the details are in the app under “Deposit / Transfer”. The app shows how much you have already paid in during the current year and how much is left up to the maximum amount. Since 2026, you can catch up on missed contributions from 2025 onwards, up to ten years back; read more in the guide Pillar 3a retroactive payments. In 2026, with a pension fund, you can pay in up to CHF 7'258 and deduct it from your taxes.
VIAC tax certificate and documents
You receive the tax certificate by e-mail each January, and you can also find it in the app.
VIAC support: chat, phone and e-mail
You can reach VIAC customer service by chat, by e-mail at support@viac.ch or by phone on 0800 80 40 40, Monday to Friday from 8.30 am to 6.00 pm. You can find many answers in the FAQ on viac.ch. VIAC does not offer investment advice.
VIAC ratings: how satisfied are customers?
Customers rate VIAC very positively. In the App Store, the VIAC app has 4.7 out of 5 stars from 466 ratings, and on Google Play 4.5 out of 5 from 533 reviews. Users mainly praise the ease of use, the low fees and the fast chat support, which matches the Evaluno test. Criticism focuses on the missing iPad app and on the performance figures. Many reviews contain referral codes, so the most meaningful ones are those describing concrete experiences.
How users rate VIAC
As of 17.11.2026
- App Store
- 466 ratings
- 4.7 out of 5 stars
- Google Play
- 533 reviews
- 4.5 out of 5 stars
Often praised
- Simple, clear app
- Low fees
- Fast chat support
- Good web app
Often criticised
- No dedicated iPad app
- Unclear performance figures
Sources: App Store and Google Play (Switzerland), accessed on 17.11.2026. Star ratings across all years, praise and criticism from reviews with text since app version 7 (end of October 2024).
VIAC code: CHF 2'000 fee-free for life
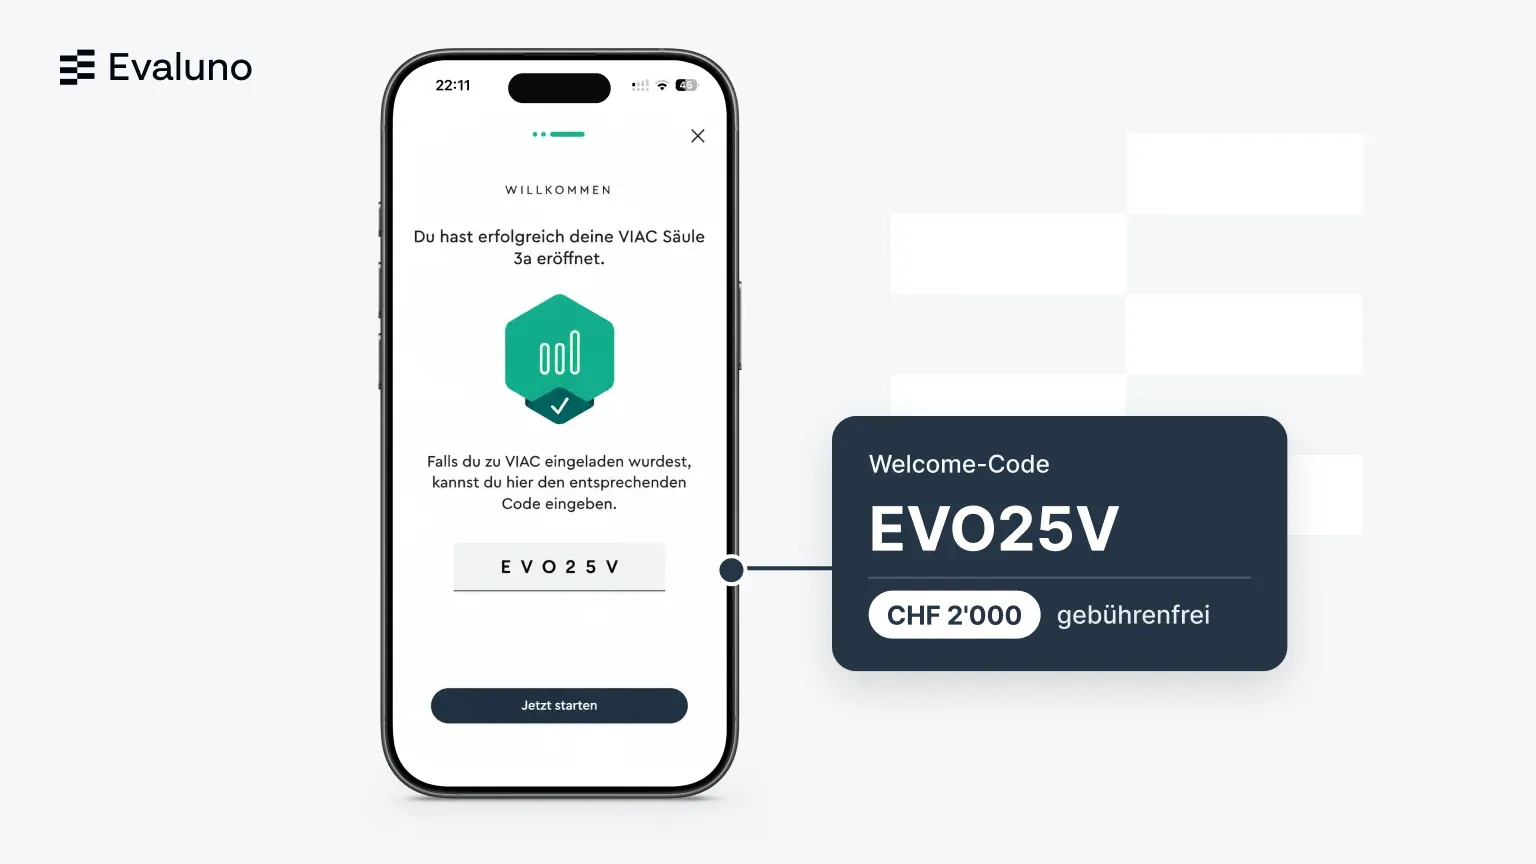
With the code EVO25V, VIAC manages the first CHF 2'000 of your assets without an administration fee, for life. People often also search for a promo code, invitation code or referral code. The code is only valid for new customers who enter it when opening an account, and it runs until 31.12.2026. Each person can receive only one fee-free amount from a code. If you later invite friends yourself, you receive another fee-free amount for each invitation, up to CHF 8'500 per product in total. You can find all the conditions on the Evaluno page on the VIAC code.
How to redeem the VIAC code
- Open an account in the VIAC app or in the browser
- At the end of the account opening, enter the code EVO25V in the welcome step
- Transfer the first deposit
- The fee-free amount of CHF 2'000 applies automatically and is shown in the app in the section on invited friends
Opening a VIAC 3a account: step by step
Opening an account is fully digital in the app or in the browser and takes less than ten minutes. You can open the account from the age of 18, but you can only pay in with earned income subject to AHV. There is no minimum amount: you can pay in from CHF 1.
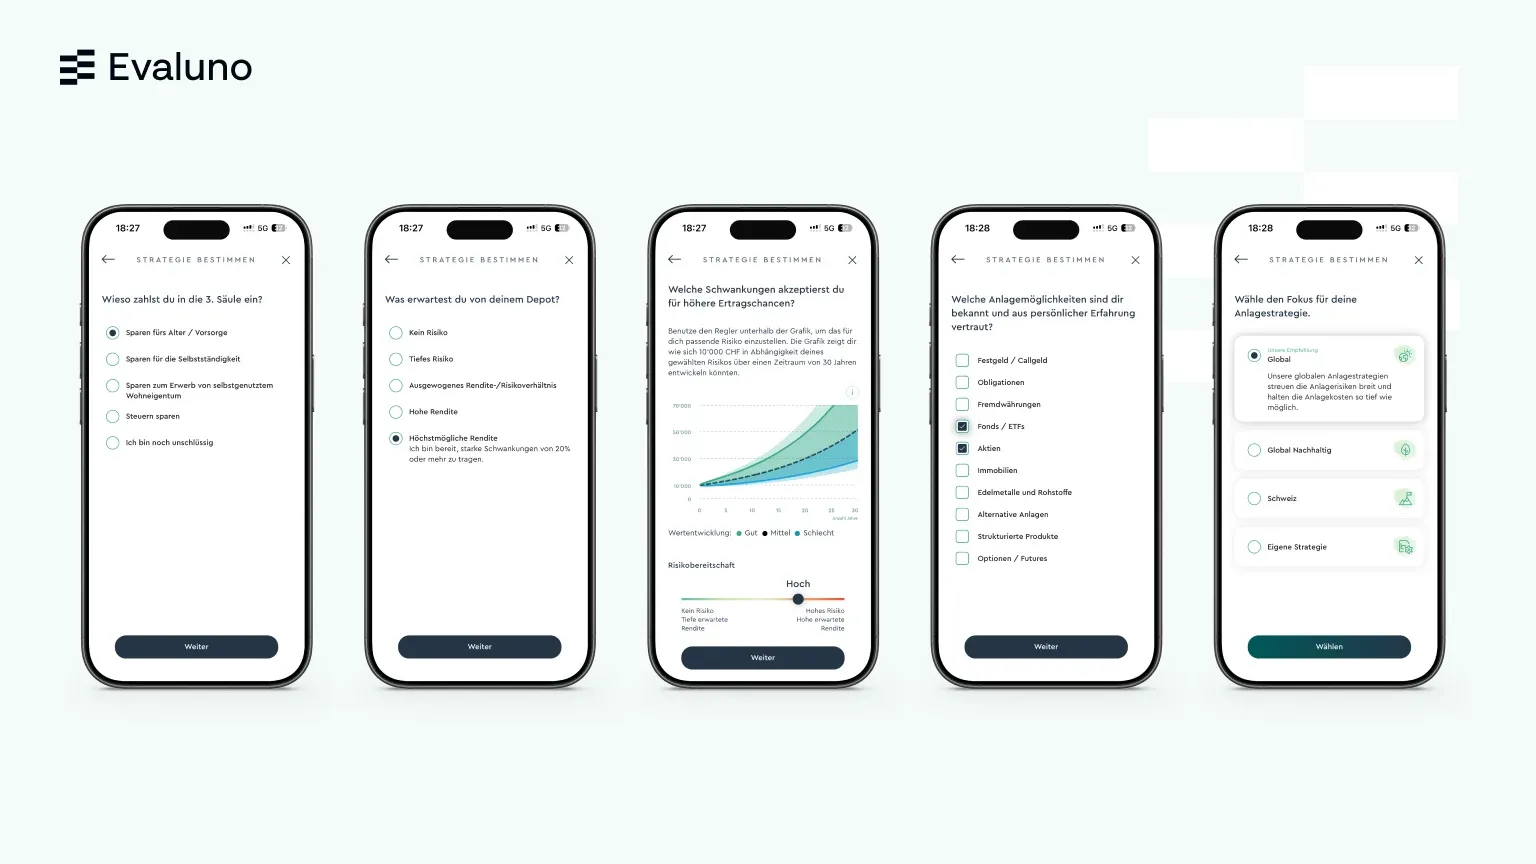
- Download the app or register on viac.ch
- Choose your strategy: goal, expected return, risk tolerance and financial knowledge
- Select the investment focus and strategy
- Enter your personal details and photograph your ID
- In the welcome step, enter the code EVO25V and transfer the first deposit
Switching your pillar 3a to VIAC: how the transfer works
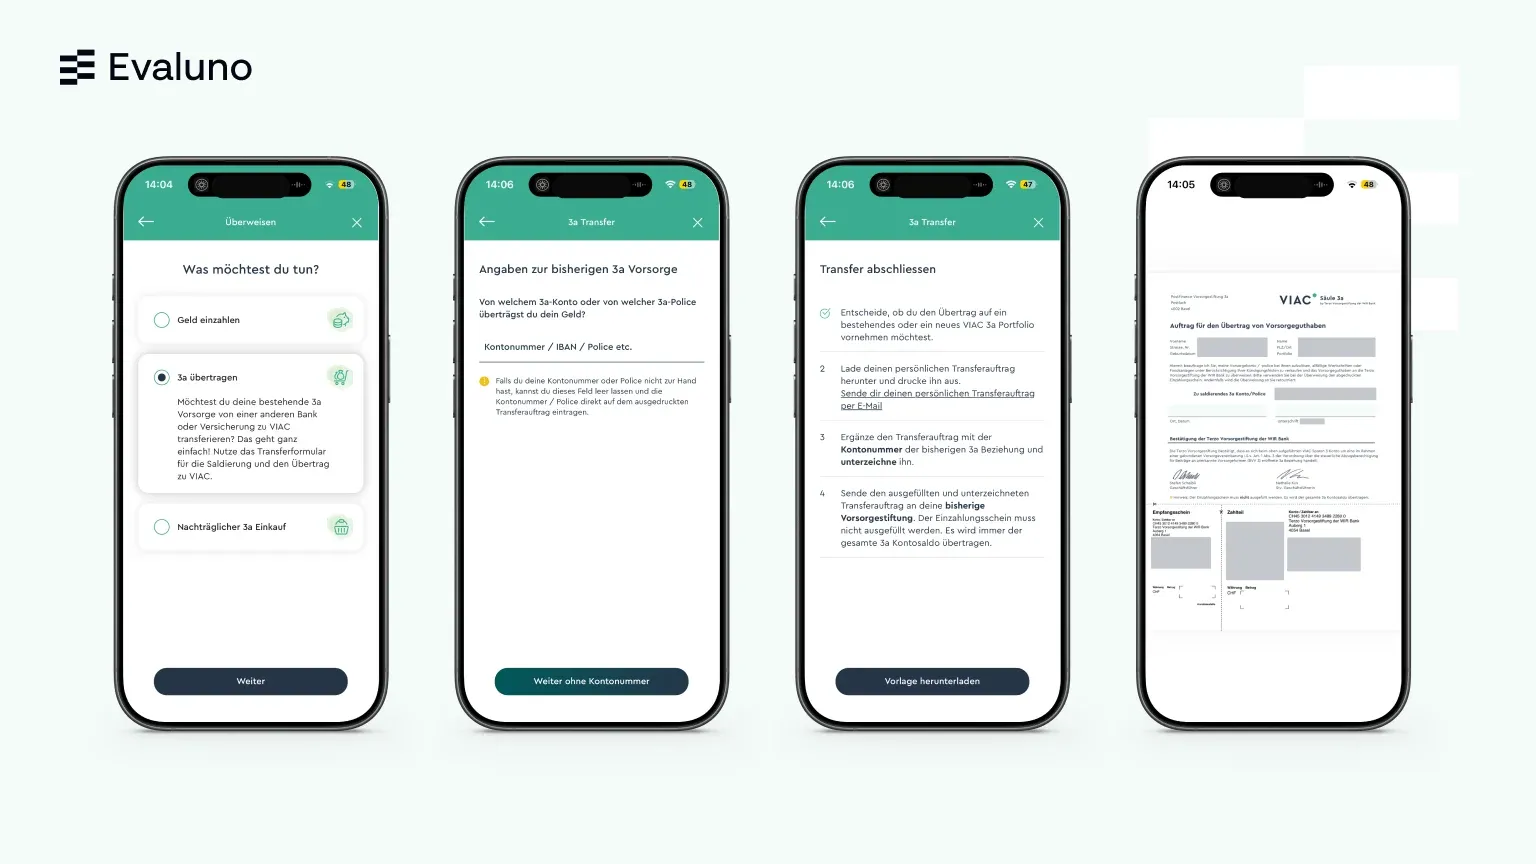
You start the switch in the app under “Deposit / Transfer”, with the option to transfer an existing 3a. You select the portfolio, enter the account or policy number of your current 3a provision and download your personal transfer order or have it sent to you by e-mail. You send the completed and signed order to your current pension foundation; the full balance is always transferred. VIAC charges no fee for the transfer, but your current provider may charge its own fees. You can find general tips on switching in the guide Switching pillar 3a.
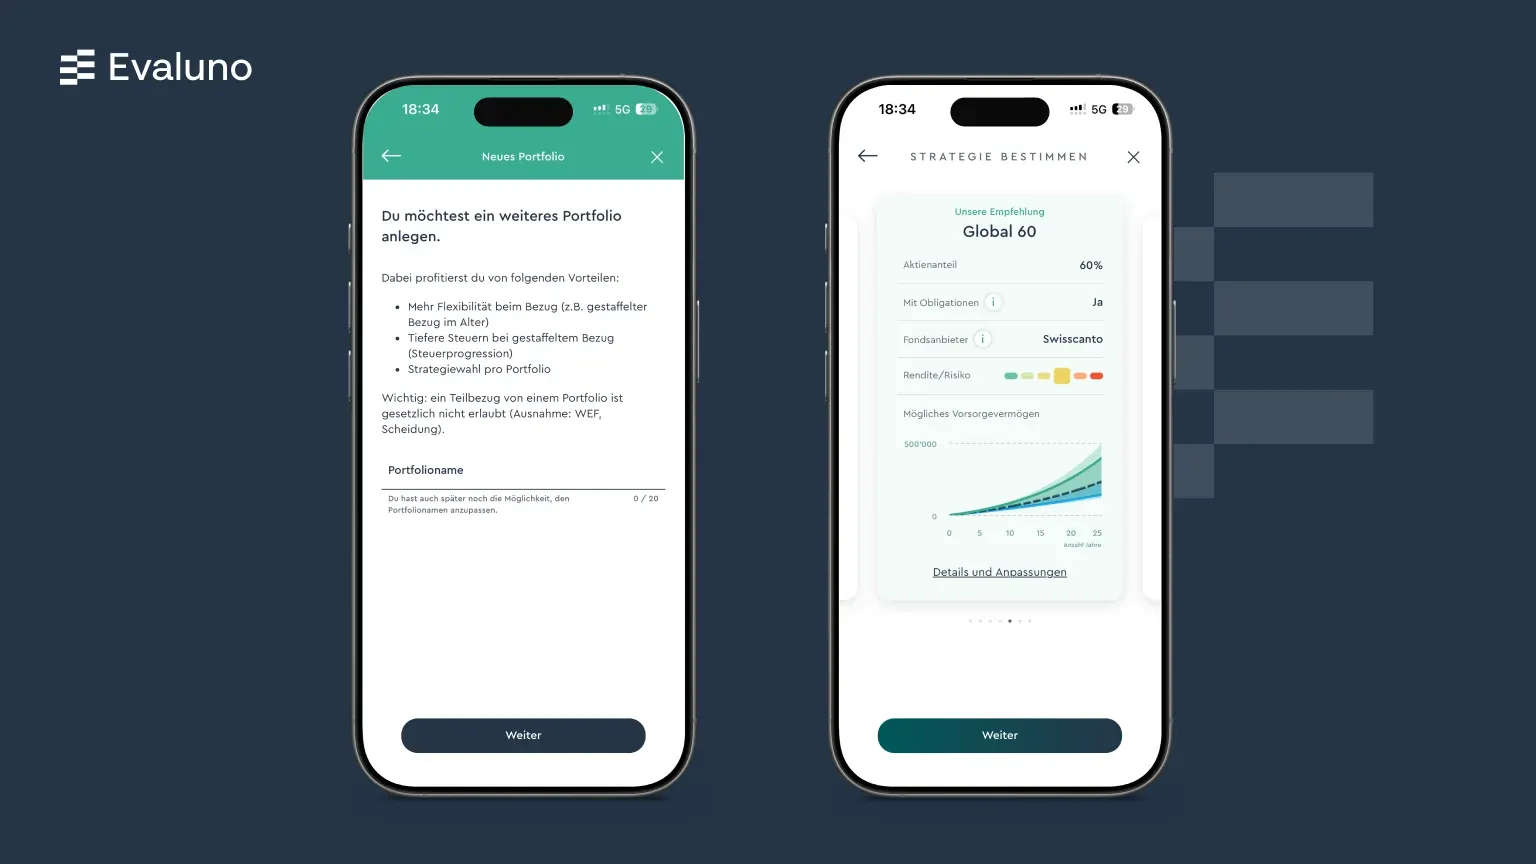
Opening another pillar 3a portfolio
You can open up to five 3a portfolios in the app, each with its own strategy. Several portfolios are worthwhile because you can later spread the withdrawal over several years and save tax. By law, a partial withdrawal from a portfolio is not allowed, except for home ownership or in the event of divorce.
Pros and cons of VIAC 3a
Pros
- Advantage: Low fees, fee-free 3a account
- Advantage: 0.20 % interest on the 3a account
- Advantage: Up to 99 % equities
- Advantage: Your own strategy from around 80 funds
- Advantage: Very good returns over five years
- Advantage: Up to 5 portfolios with their own strategy
Cons
- Disadvantage: Slightly more expensive than finpension
- Disadvantage: Early withdrawal for home ownership costs CHF 300
- Disadvantage: No dedicated iPad app
Verdict: is VIAC 3a worth it?
Yes, if you want to invest your pillar 3a in securities at low cost and value good returns and plenty of flexibility. VIAC costs 0.41 to 0.44 % a year depending on the strategy, charges no fee on the 3a account and pays 0.20 % interest. With Global Sustainable 100, VIAC achieved one of the best five-year returns in the Evaluno comparison, and with your own strategy you choose the funds yourself. The drawbacks are the missing iPad app and the fee for early withdrawal. If you are looking for the lowest costs, True Wealth, findependent or finpension are slightly cheaper.
Frequently asked questions about VIAC 3a
Yes, for anyone who wants to invest their pillar 3a in securities at low cost. With a ready-made strategy, VIAC costs at most 0.44 % a year, achieved one of the best five-year returns on the market with Global Sustainable 100 and also lets you put together your own strategy. Money in the 3a account stays fee-free and earns 0.20 % interest.
VIAC 3a costs 0.41 to 0.44 % a year depending on the strategy, including product costs. The fee is only charged on invested money, and the 3a account is fee-free; without bonds, the costs fall to as little as 0.16 % with a low equity share. For an early withdrawal for home ownership, VIAC charges CHF 300.
Yes. With the code EVO25V, CHF 2'000 of your assets stay fee-free for life. You enter it when opening an account; it is valid for new customers until 31.12.2026.
Both are among the cheapest digital pillar 3a providers: finpension costs 0.39 to 0.41 % and VIAC 0.41 to 0.44 % a year. Over five years, VIAC was ahead with Global Sustainable 100 (+44.4 %) compared with finpension Global 100 (+37.0 %). Both allow up to 99 % equities and your own strategy, and VIAC also pays 0.20 % interest on the 3a account.
At 0.41 to 0.44 % a year, VIAC is slightly cheaper than frankly at 0.43 to 0.47 % and allows up to 99 % equities and your own strategy. Over five years, the best products were almost level: frankly Extreme 95 Responsible with +44.5 %, VIAC Global Sustainable 100 with +44.4 %.
VIAC is run by VIAC AG, based in Basel and founded in 2017. The contractual partner for pillar 3a is the Terzo Pension Foundation of Bank WIR, and the money in the 3a account is held at Bank WIR.
Yes. The securities are segregated assets, held in custody by UBS or Zürcher Kantonalbank, and do not form part of the bankruptcy estate in the event of bankruptcy. The assets in the 3a account are privileged up to CHF 100'000. The value of the securities can fluctuate.
That depends on the strategy. Up to 30.9.2026, Global Sustainable 100 gained 22.5 % over one year, 54.1 % over three years and 44.4 % over five years. You can find the figures for all 15 strategies in the Evaluno pillar 3a fund comparison.
That depends on your investment horizon and your risk capacity. If the withdrawal is more than ten years away, a high equity share such as Global 80 or Global 100 is often a good fit. Over five years, Global was ahead of Switzerland at every level.
Around 40 %. VIAC Global 100 invests 99 % in equities and weights Swiss shares much more heavily than the global market; the largest holdings are Novartis, Roche and Nestlé. The remaining 60 % is mainly in North America, Asia and Europe (factsheet, as of 30.9.2026).
Up to 30.9.2026, VIAC Global 100 gained 20.8 % over one year, 53.3 % over three years and 43.8 % over five years. Over five years, the strategy is therefore among the ten pillar 3a products with the best returns in the Evaluno comparison. Because of the high equity share, the value can fluctuate sharply in the meantime.
In the VIAC app, you can download it from the strategy, and it is also available on viac.ch, in each case for the implementation with UBS or Swisscanto. Among other things, it shows the breakdown by region and currency, the largest holdings, the total costs and the returns.
Yes. Instead of a ready-made strategy, you put together your portfolio from around 80 funds and ETFs, for example from UBS, Swisscanto and iShares, even with up to 5 % in bitcoin. ETFs are subject to stamp duty, and funds in foreign currencies to currency costs.
Yes. The pillar 3a account currently pays 0.20 % interest, and VIAC charges no fee on it. In the strategies, too, there is no fee on the portion held in the account.
Fully digitally in the app or in the browser: you choose your strategy, enter your personal details and photograph your ID. It takes less than ten minutes, and you can pay in from CHF 1.
In the app, under “Deposit / Transfer”, you choose the option to transfer an existing 3a, download your personal transfer order and send it signed to your current provider. The entire 3a balance is always transferred, and VIAC charges no fee for this.
Up to five portfolios, each with its own strategy. With several portfolios, you can later spread the withdrawal over several years and save tax.
Yes. Since 2026, you can catch up in the app on missed contributions from 2025 onwards, going back no more than ten years.
A withdrawal is only possible for legal reasons, for example on retirement, for owner-occupied housing, on becoming self-employed or on emigrating. For an early withdrawal for home ownership, VIAC charges CHF 300; other withdrawals are free of charge.
Silvan Forster is an author and co-founder of Evaluno.ch. He studied business administration with a specialisation in Banking & Finance and, with around ten years in the financial industry, knows financial products and their fee structures first-hand. He is a VIAC customer himself and wrote this review using his own account.
More about Silvan ForsterSource: provider websites, product documents and direct information from providers, as of .
All information without guarantee. Past performance is no indicator of future results, prices can fluctuate. Evaluno earns a commission when an account is opened through some of these links. This does not change the results or their ranking. Evaluno’s methodology
Related topics
Pillar 3a fund comparison
373 pillar 3a funds compared: costs from 0.10 % to 1.71 %, five-year performance, filterable by equity share. Compare independently.
View comparison
finpension review
finpension 3a tested with a real account: fees, returns of all 18 strategies and a comparison with VIAC and frankly. CHF 25 credit with code PQMK7S.
Read the review
frankly review
ZKB’s frankly 3a tested with a real account: fees, returns of all 15 products and a comparison with VIAC and finpension. CHF 35 with code Evaluno35.
Read the reviewLegal disclaimer
Evaluno does not provide investment, legal or tax advice and is no substitute for personal advice.