

finpension 3a at a glance
| Provider | finpension 3a Vorsorgestiftung (pension foundation), managed by finpension AG, Lucerne |
| On the market since | 2020 |
| Costs per year | 0.39 % with the ready-made strategies (fund costs 0.00 % according to the factsheets), up to 0.41 % with your own strategy, depending on the funds |
| Investment products | 18 strategies (Switzerland, Global, Sustainable) in 6 levels with 0 to 99 % equities, index funds from Swisscanto or UBS |
| Number of accounts/strategies | up to 5 portfolios, each with its own strategy |
| Access | App (iOS, Android) and web version |
| Languages | German, French and English |
| Assets under management | over CHF 6 bn |
| Other products | finpension Vested benefits, finpension Invest, 1e plan |
| Referral code | PQMK7S: CHF 25 credit on the fees |
Data as of 17.11.2026. Sources: finpension app (screenshots from November 2026), finpension.ch (product and fee pages, factsheet, accessed on 17.11.2026). No guarantee.
What is finpension 3a? The pillar 3a of finpension AG
finpension 3a is the digital pension offering of finpension AG, based in Lucerne, and has been on the market since 2020. You open and manage your pillar 3a via the app or in the web version on your computer.
Your contractual partner is the finpension 3a Vorsorgestiftung, a pension foundation. It is managed by finpension AG, which has existed since 2017. Besides pillar 3a, finpension also offers vested benefits accounts (finpension Vested benefits), the wealth management service finpension Invest and the 1e plan for executive pensions. This review covers finpension 3a only. Over 50'000 people in Switzerland use finpension for their pension savings, and assets under management exceed CHF 6 bn.
finpension review: tested with a real 3a account
Evaluno tests finpension with a real 3a account that has been funded since April 2026 in the Global 100 strategy with index funds from Swisscanto. The result: the costs are very low, the choice is wide and the app is clear.
Test result at a glance
| Criterion | Rating | Reason |
|---|---|---|
| Costs | very good | 0.39 % a year, one of the lowest fees on the market; it also applies to money in the 3a account |
| Investment offering | very good | 18 strategies with up to 99 % equities, plus your own strategy from over 130 index funds |
| Returns | good | Solid index funds, but over five years somewhat behind the best products from VIAC and frankly |
| App and usability | very good | Clear, with allocation, largest holdings and transactions; also in the browser |
| Account opening | very good | Simple and quick: fully digital, in a few minutes |
How Evaluno tests
The basis is an ordinary customer account at finpension: opened privately, funded with our own money and not provided by finpension. Fees, products and processes come from the app (screenshots from November 2026) and from finpension.ch. Evaluno compares costs and returns with over 350 pillar 3a funds and investment strategies (data as of 30 September 2026). Evaluno rates all 3a providers against the same five criteria.
finpension 3a fees: how much does finpension cost?
finpension 3a costs 0.39 % a year. The flat fee covers management, purchases and sales, strategy changes as well as exchange fees and stamp duties. For the ready-made strategies, fund costs of 0.00 to 0.02 % come on top, but usually there are none. With your own strategy, the fund costs depend on the funds you choose. The fee also applies to money you save in the 3a account without investing it.
Fee on the 3a account too: 0.39 % without interest
If you do not invest the money, you choose the «100% Cash» strategy at finpension. The interest rate is currently 0.00 %, but the fee of 0.39 % still applies. For pure saving without investing, finpension is therefore not the best choice; at frankly, for example, cash is fee-free and earns interest.
What the fee includes and what it does not
- Included: account opening, management, purchases and sales, strategy changes, exchange fees and stamp duties, transfer to another provider
- Not included: early withdrawal for home ownership CHF 250, pledge CHF 200, withdrawal when living abroad CHF 250 (CHF 750 within 12 months of the first deposit), currency costs of 0.05 % with your own strategy, often less thanks to internal netting
Worked example: what you pay per year
finpension calculates the fee as a fixed percentage of your balance, so it rises with your assets. With CHF 50'000 in a ready-made strategy, you pay CHF 195 to 205 a year depending on the fund costs. For comparison: at VIAC the same balance costs CHF 205 to 220 a year, at frankly CHF 215 to 235.
| Balance | Fee only (0.39 %) | With fund costs (up to 0.41 %) |
|---|---|---|
| CHF 10'000 | CHF 39 | CHF 39 to 41 |
| CHF 50'000 | CHF 195 | CHF 195 to 205 |
| CHF 100'000 | CHF 390 | CHF 390 to 410 |
finpension 3a strategies and funds: Switzerland, Global, Sustainable or custom?
finpension 3a offers 18 ready-made strategies in the Switzerland, Global and Sustainable lines, plus your own strategy from over 130 index funds. At finpension, you first choose an investment focus and then the equity share. Switzerland focuses more on Swiss equities, Global invests worldwide, Sustainable invests in companies that meet defined sustainability standards. The equity share comes in six levels, and the number in the name shows it rounded: Global 100 contains 99 % equities and 1 % cash.
As the fund house, you choose Swisscanto or UBS; both implement the strategies with institutional index funds instead of ETFs. As a result, no stamp duty is charged on purchases and sales, and a large share of foreign withholding taxes can be reclaimed. finpension advances the Swiss withholding tax and reinvests it immediately. If you want more control, you put together your own strategy from over 130 index funds, including gold or Bitcoin. When you open the account, the app asks about your investment horizon, loss tolerance and knowledge and then suggests a suitable strategy.
All 18 finpension strategies at a glance
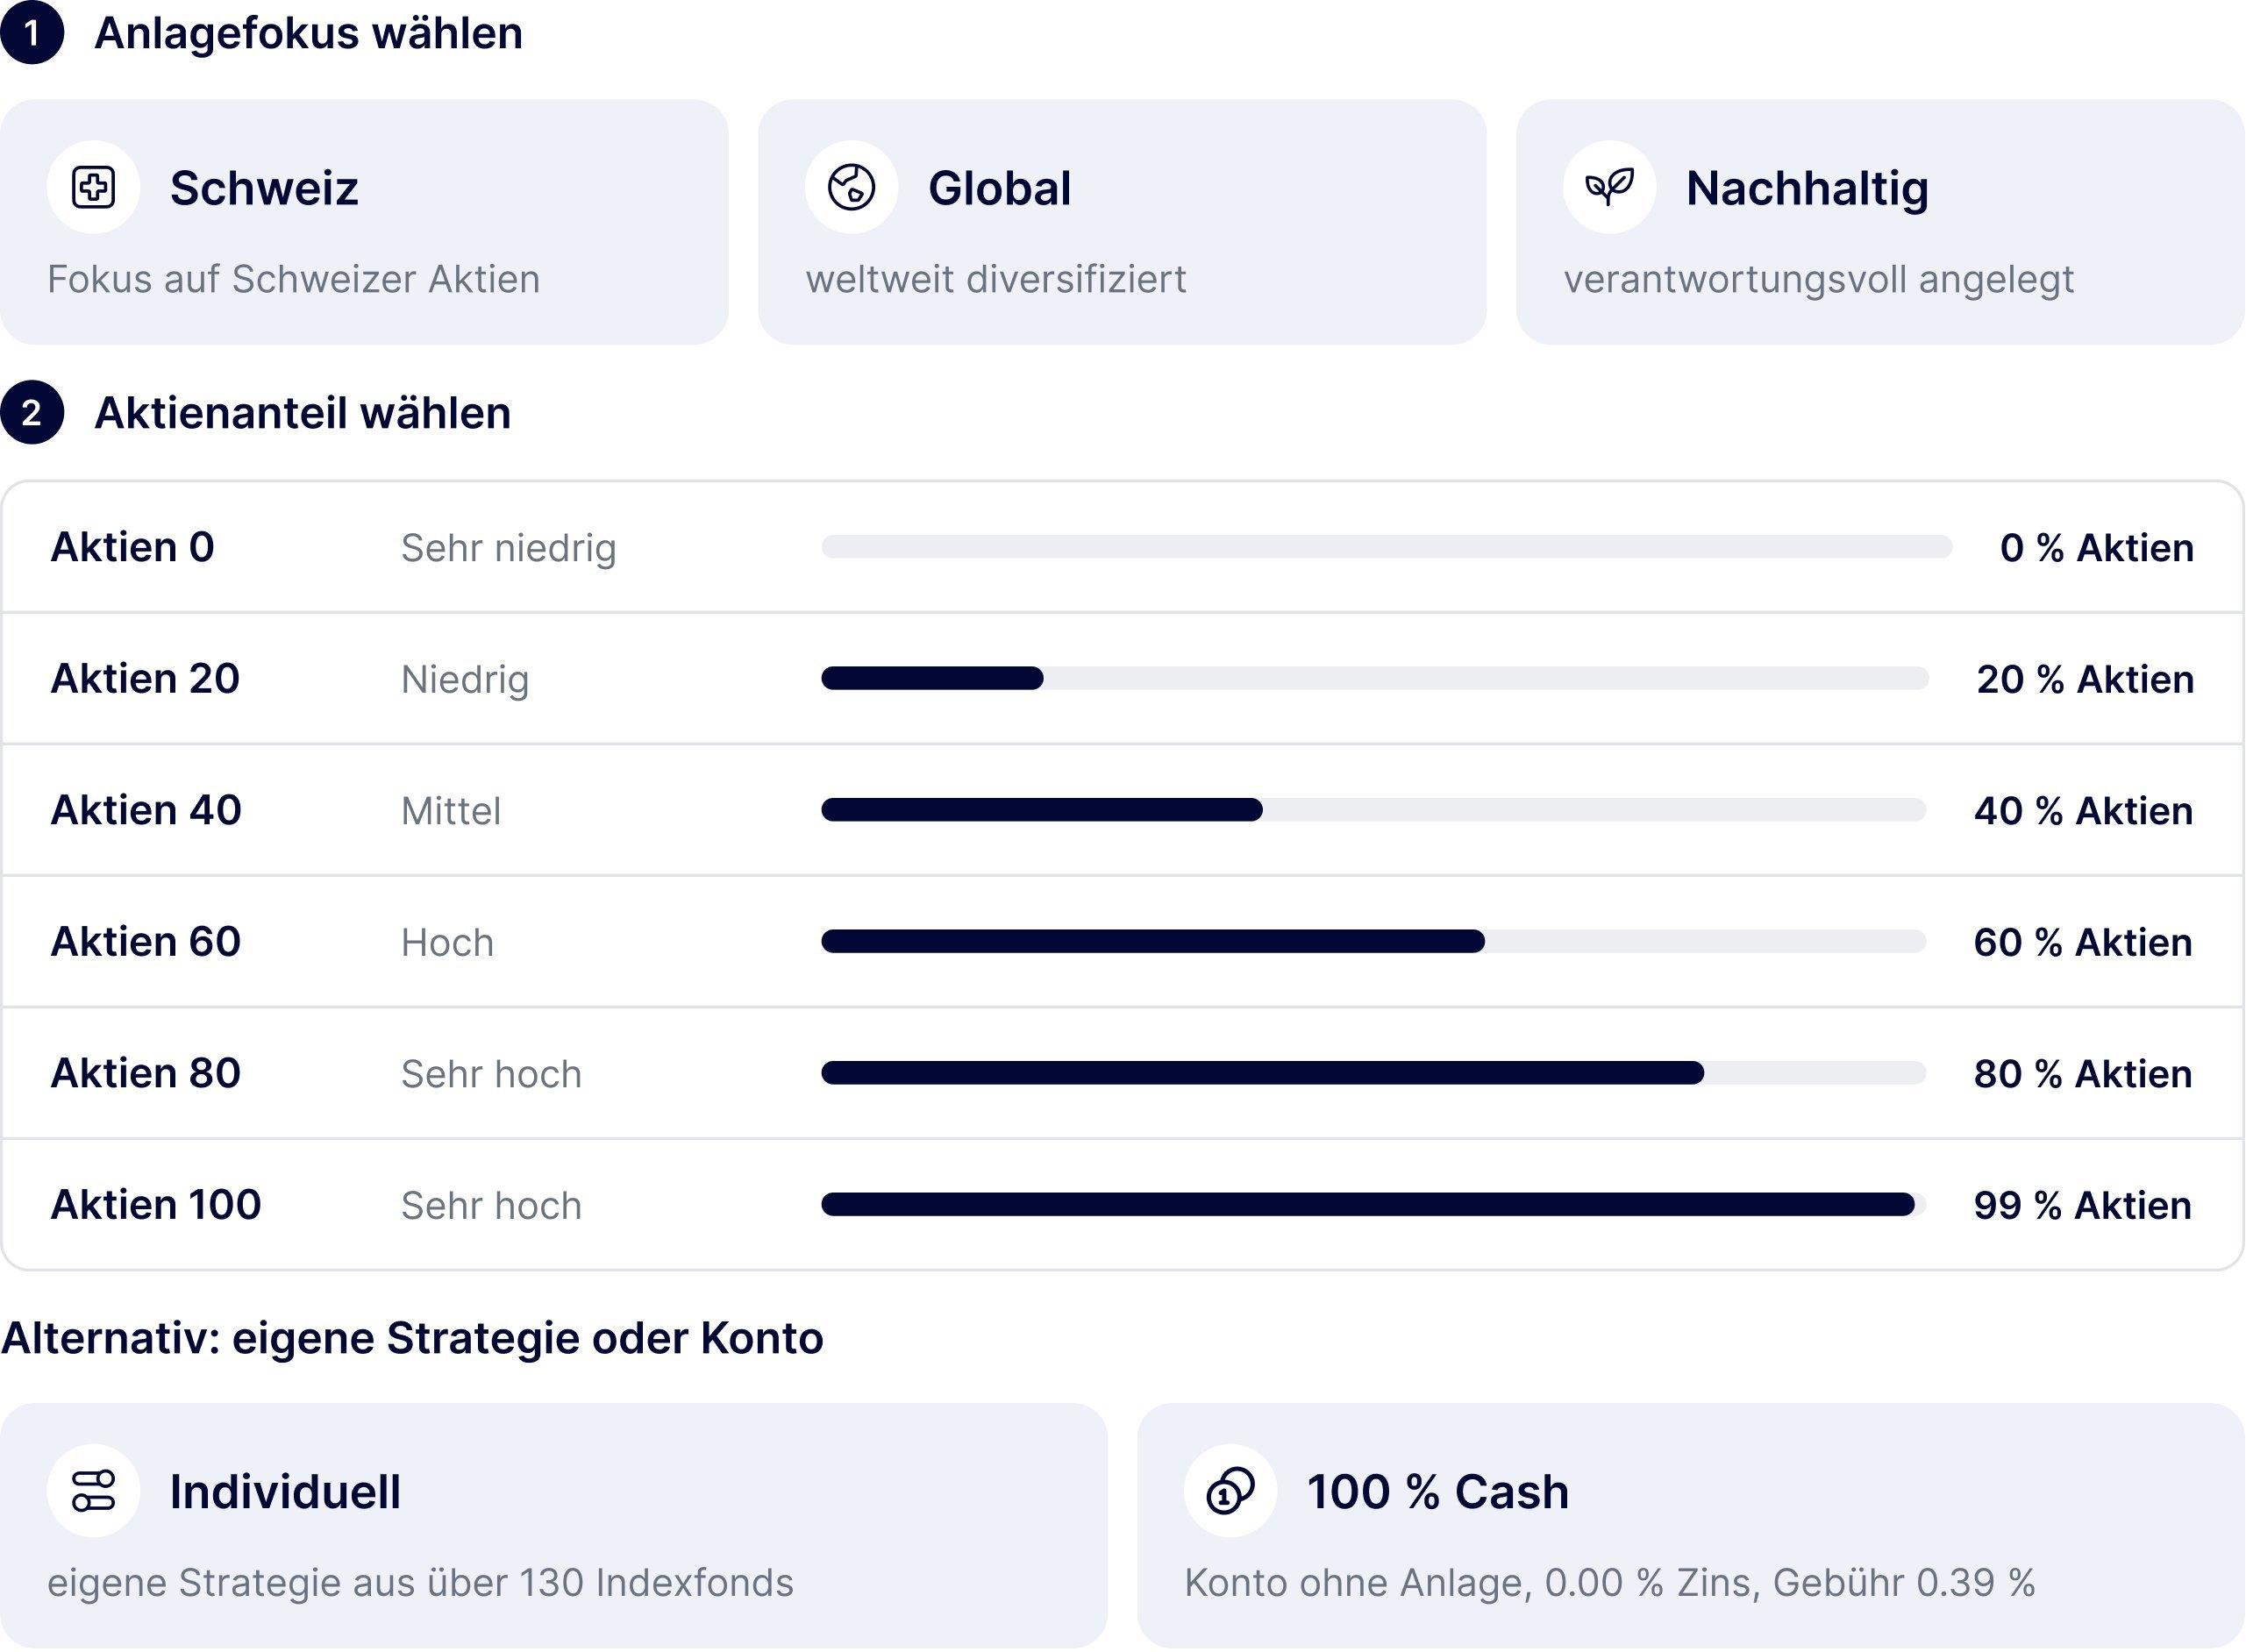
In the finpension app, you can see the split between equities, bonds, real estate and cash as well as the risk for each strategy. You can switch strategy at any time free of charge in the app. You can also hold up to five portfolios, each with its own strategy.
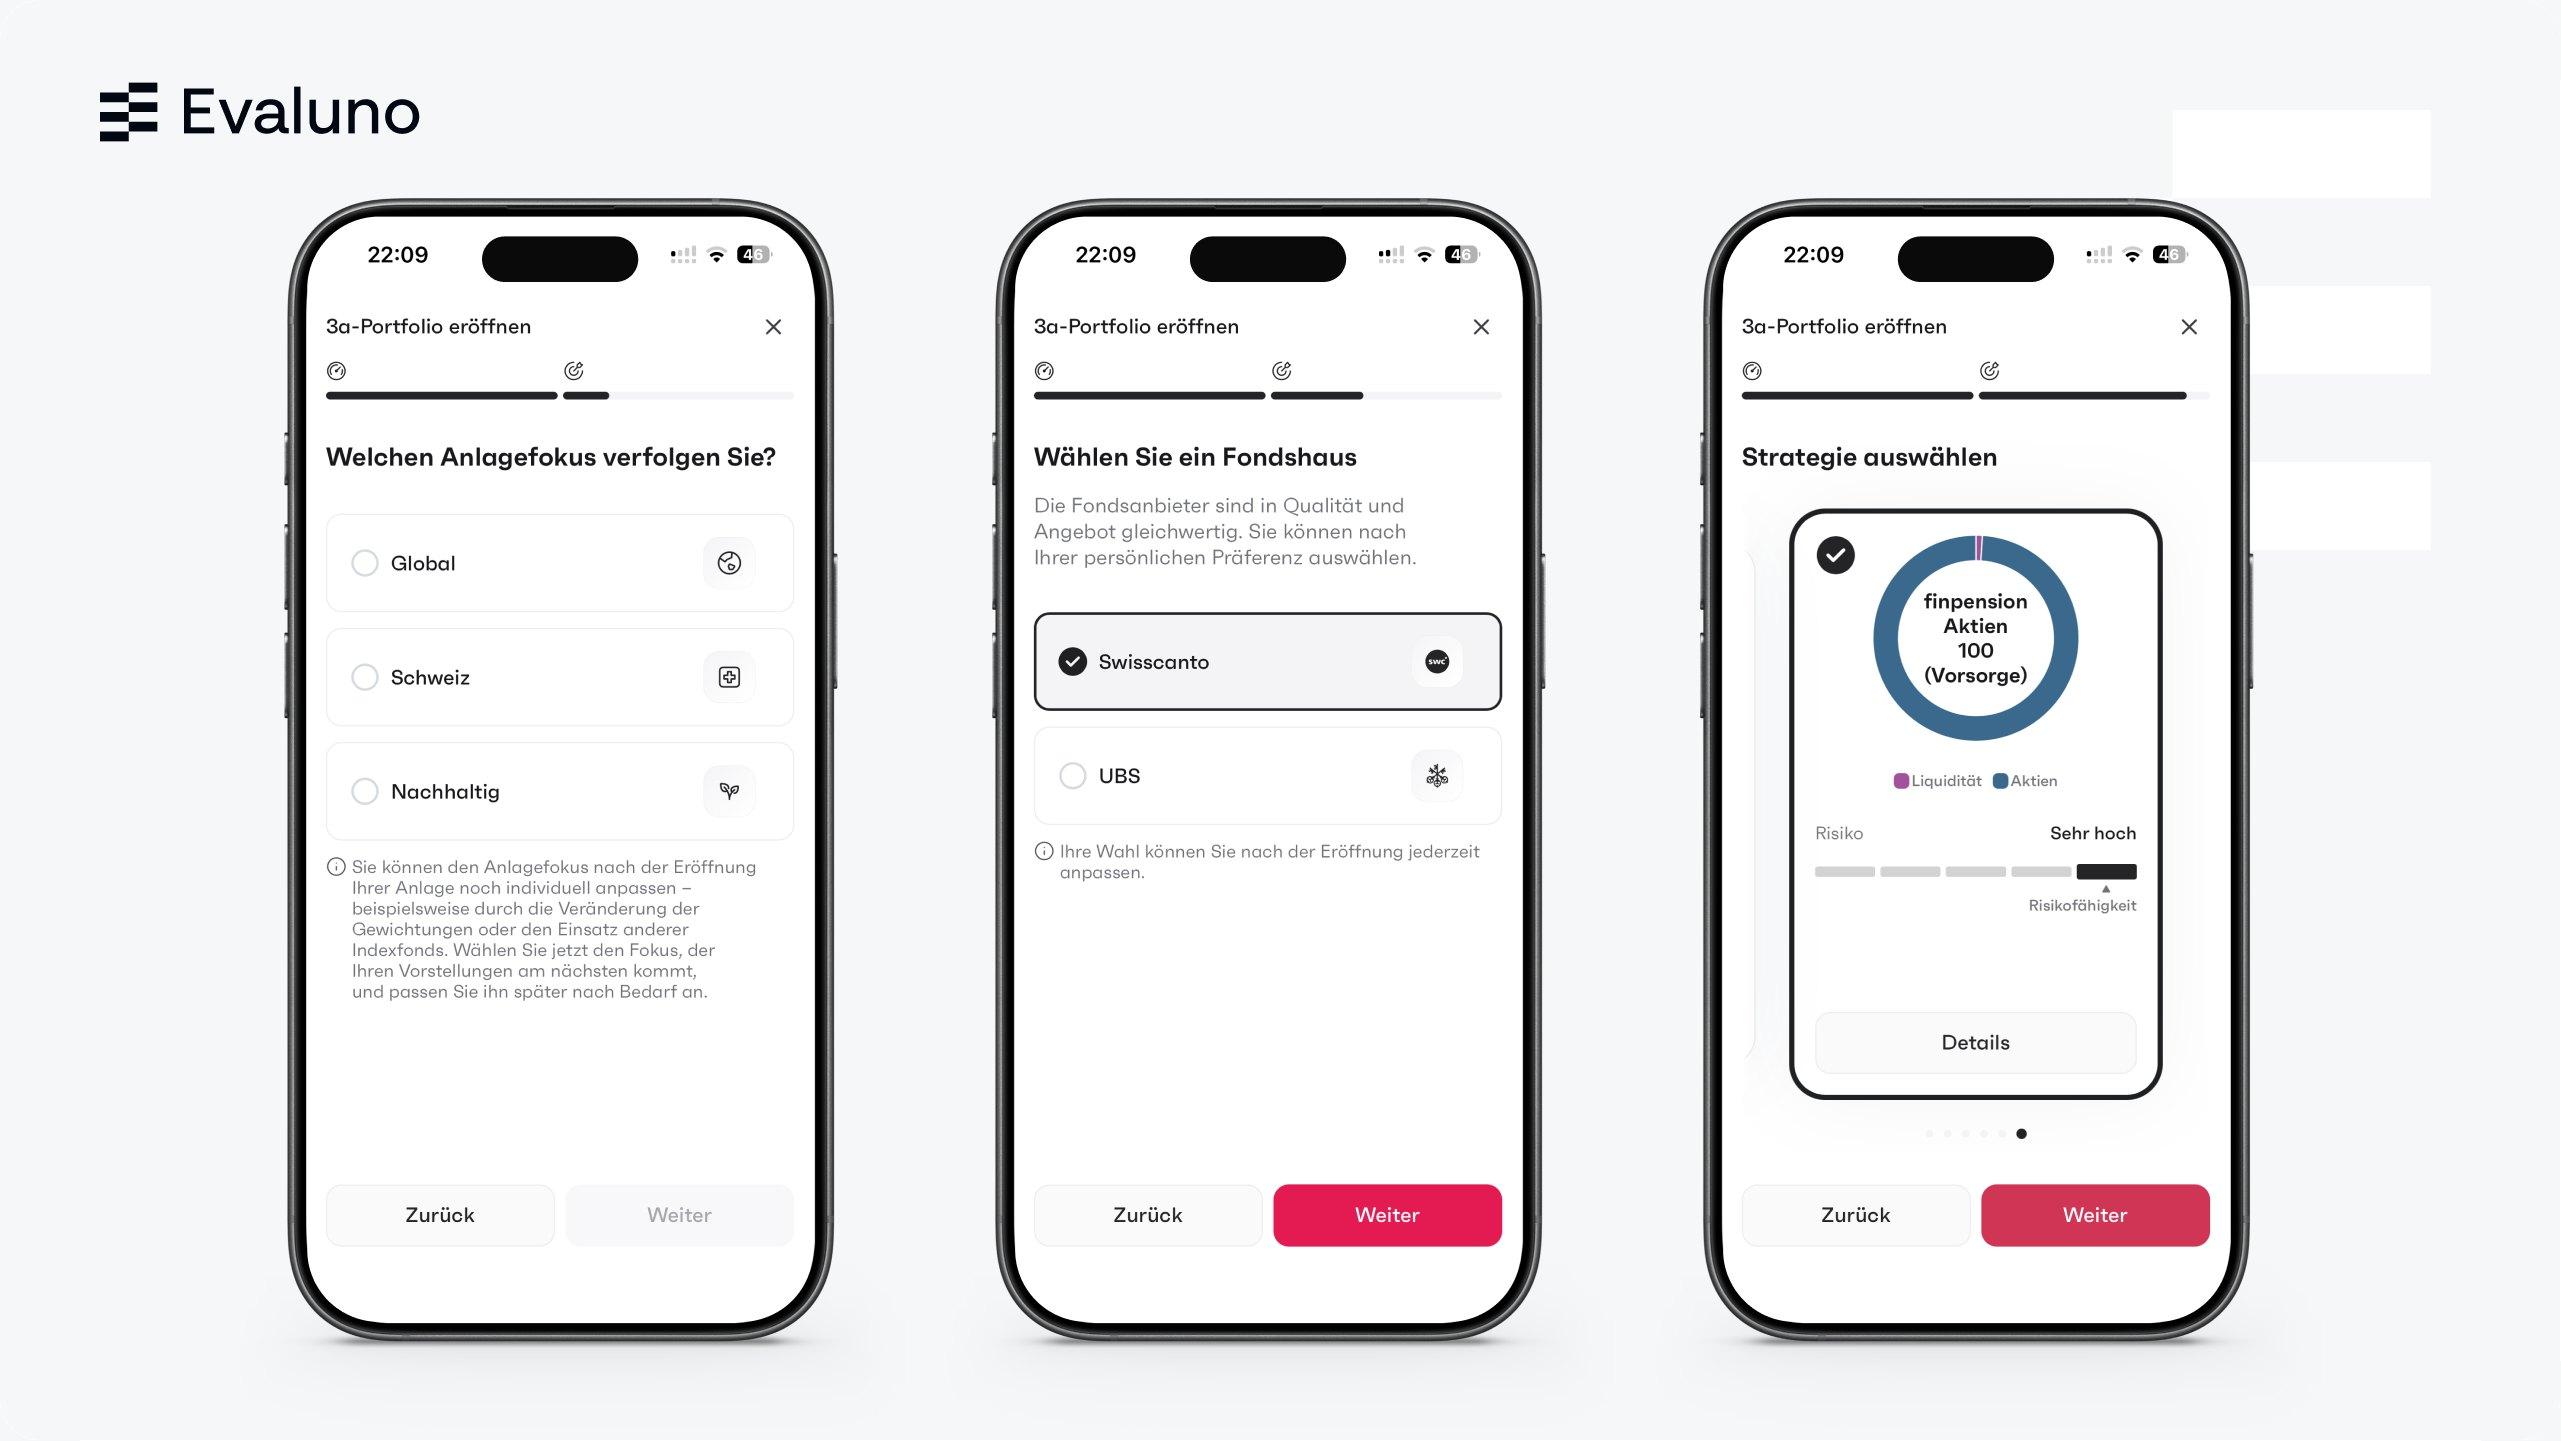
Switzerland, Global or Sustainable: what is the difference?
Switzerland concentrates the equities on the home market with its pharmaceutical and food stocks. Global invests broadly across the world’s stock exchanges but still holds many Swiss equities: in the test account’s Global 100 strategy, they make up around 40 %. Sustainable invests in companies that meet defined environmental, social and governance standards. If you want no investment risk, you choose the «100% Cash» strategy, but you pay the fee of 0.39 % and currently receive no interest.
Which finpension strategy suits you?
What matters is your investment horizon and how well you cope with fluctuations. Retirement is often decades away, so a high equity share such as Global 80 or Global 100 suits many people. If you need the money in a few years, for a home for example, a low level makes more sense. With up to five portfolios, you can combine both.
finpension 3a returns and performance: how the strategies have done
The return you achieve with finpension 3a depends mainly on the equity share. In the five years to 30.9.2026, Global 100 gained 37.0 % and Global 40 4.5 %. Over five years, Global was ahead of Sustainable and Switzerland at every level that includes equities. The levels with few equities suffered from the rise in interest rates in 2022 and are in negative territory over five years.
Performance of all 18 finpension strategies
The tables show the performance of all 18 finpension strategies over one, three and five years. This lets you see at a glance how Switzerland, Global and Sustainable differ at the same equity share.
| Level | Equities | Switzerland | Global | Sustainable |
|---|---|---|---|---|
| Equities 100 | 99 % | +17.6 % | +18.6 % | +18.1 % |
| Equities 80 | 80 % | +13.9 % | +15.0 % | +14.4 % |
| Equities 60 | 60 % | +9.6 % | +10.1 % | +9.8 % |
| Equities 40 | 40 % | +5.1 % | +5.6 % | +5.3 % |
| Equities 20 | 20 % | +1.0 % | +1.1 % | +1.0 % |
| Equities 0 | 0 % | −0.9 % | −0.9 % | −0.9 % |
| Level | Equities | Switzerland | Global | Sustainable |
|---|---|---|---|---|
| Equities 100 | 99 % | +42.0 % | +50.3 % | +48.8 % |
| Equities 80 | 80 % | +35.8 % | +42.5 % | +40.9 % |
| Equities 60 | 60 % | +27.9 % | +31.4 % | +30.8 % |
| Equities 40 | 40 % | +19.8 % | +22.3 % | +21.6 % |
| Equities 20 | 20 % | +11.6 % | +12.9 % | +11.9 % |
| Equities 0 | 0 % | +4.0 % | +4.0 % | +4.2 % |
| Level | Equities | Switzerland | Global | Sustainable |
|---|---|---|---|---|
| Equities 100 | 99 % | +28.4 % | +37.0 % | +36.6 % |
| Equities 80 | 80 % | +20.5 % | +27.2 % | +26.0 % |
| Equities 60 | 60 % | +11.7 % | +14.6 % | +14.5 % |
| Equities 40 | 40 % | +2.8 % | +4.5 % | +4.3 % |
| Equities 20 | 20 % | −5.9 % | −5.7 % | −6.2 % |
| Equities 0 | 0 % | −1.2 % | −1.2 % | −1.1 % |
Cumulative performance in CHF to 30.9.2026. Source: Evaluno pillar 3a fund comparison (data as of 30.9.2026). Past returns are no guarantee of future returns.
finpension vs VIAC and frankly: which is better?
In short: finpension is the cheapest and lets you put together your strategy freely. Over five years, however, VIAC and frankly achieved higher returns with their best products and pay interest on the 3a account.
On returns, finpension recently trailed: over five years its best product, Global 100, gained 37.0 %, while VIAC (+44.4 %) and frankly (+44.5 %) did better. In return, finpension is the cheapest at 0.39 to 0.41 % and offers over 130 index funds for your own strategy. For the 3a account, frankly has the edge: cash there is fee-free and earns 0.15 % interest, while finpension pays no interest.
If you are looking for low costs and a strategy you put together yourself, finpension is the right choice. If you also want to save in the 3a account without investing, frankly or VIAC will suit you better. Read more about frankly in our frankly 3a review, and find all digital 3a providers in the Evaluno pillar 3a fund comparison.
| Criterion | finpension |  VIAC |  frankly |
|---|---|---|---|
| Total costs per year | 0.39 to 0.41 % | 0.41 to 0.44 % | 0.43 to 0.47 % |
| Max. equity share | 99 % | 99 % | 95 % |
| Investment strategies | 18 | 15 | 15 |
| Custom strategy | Yes, over 130 index funds | Yes, funds and weightings freely selectable | No, fixed strategies only |
| Index strategies | Yes | Yes | Yes |
| Sustainable strategies | Yes | Yes | Yes |
| Best 5-year return | +37.0 % | +44.4 % | +44.5 % |
| Best product | Global 100 | Global Nachhaltig 100 | Extreme 95 Responsible |
| Interest on 3a account | 0.00 % | 0.20 % | 0.15 % |
Total costs per year including product costs; for finpension, the ready-made strategies. Return over 5 years to 30.9.2026, in each case for the provider’s best product. Sources: Evaluno pillar 3a fund comparison (strategies, returns and the costs of VIAC and frankly, data as of 30.9.2026) and the providers’ websites (finpension costs, equity share, custom strategy and interest on uninvested balance, as of November 2026). Past returns are no guarantee of future returns.
Is finpension safe?
Yes. Your 3a balance is not held by finpension AG but by the finpension 3a Vorsorgestiftung, a pension foundation. The securities belong to the foundation and do not form part of the bankruptcy estate if a bank fails; money in the 3a account is given preferential treatment up to CHF 100'000. The foundation is supervised by the Zentralschweizer BVG- und Stiftungsaufsicht (ZBSA), the Central Swiss supervisory authority for occupational pensions and foundations.
Securities fluctuate: with a high equity share, your balance can fall sharply at times. You can also protect your account with two-factor authentication via SMS code or an authenticator app; this code is always required for payouts.
The finpension app in everyday use
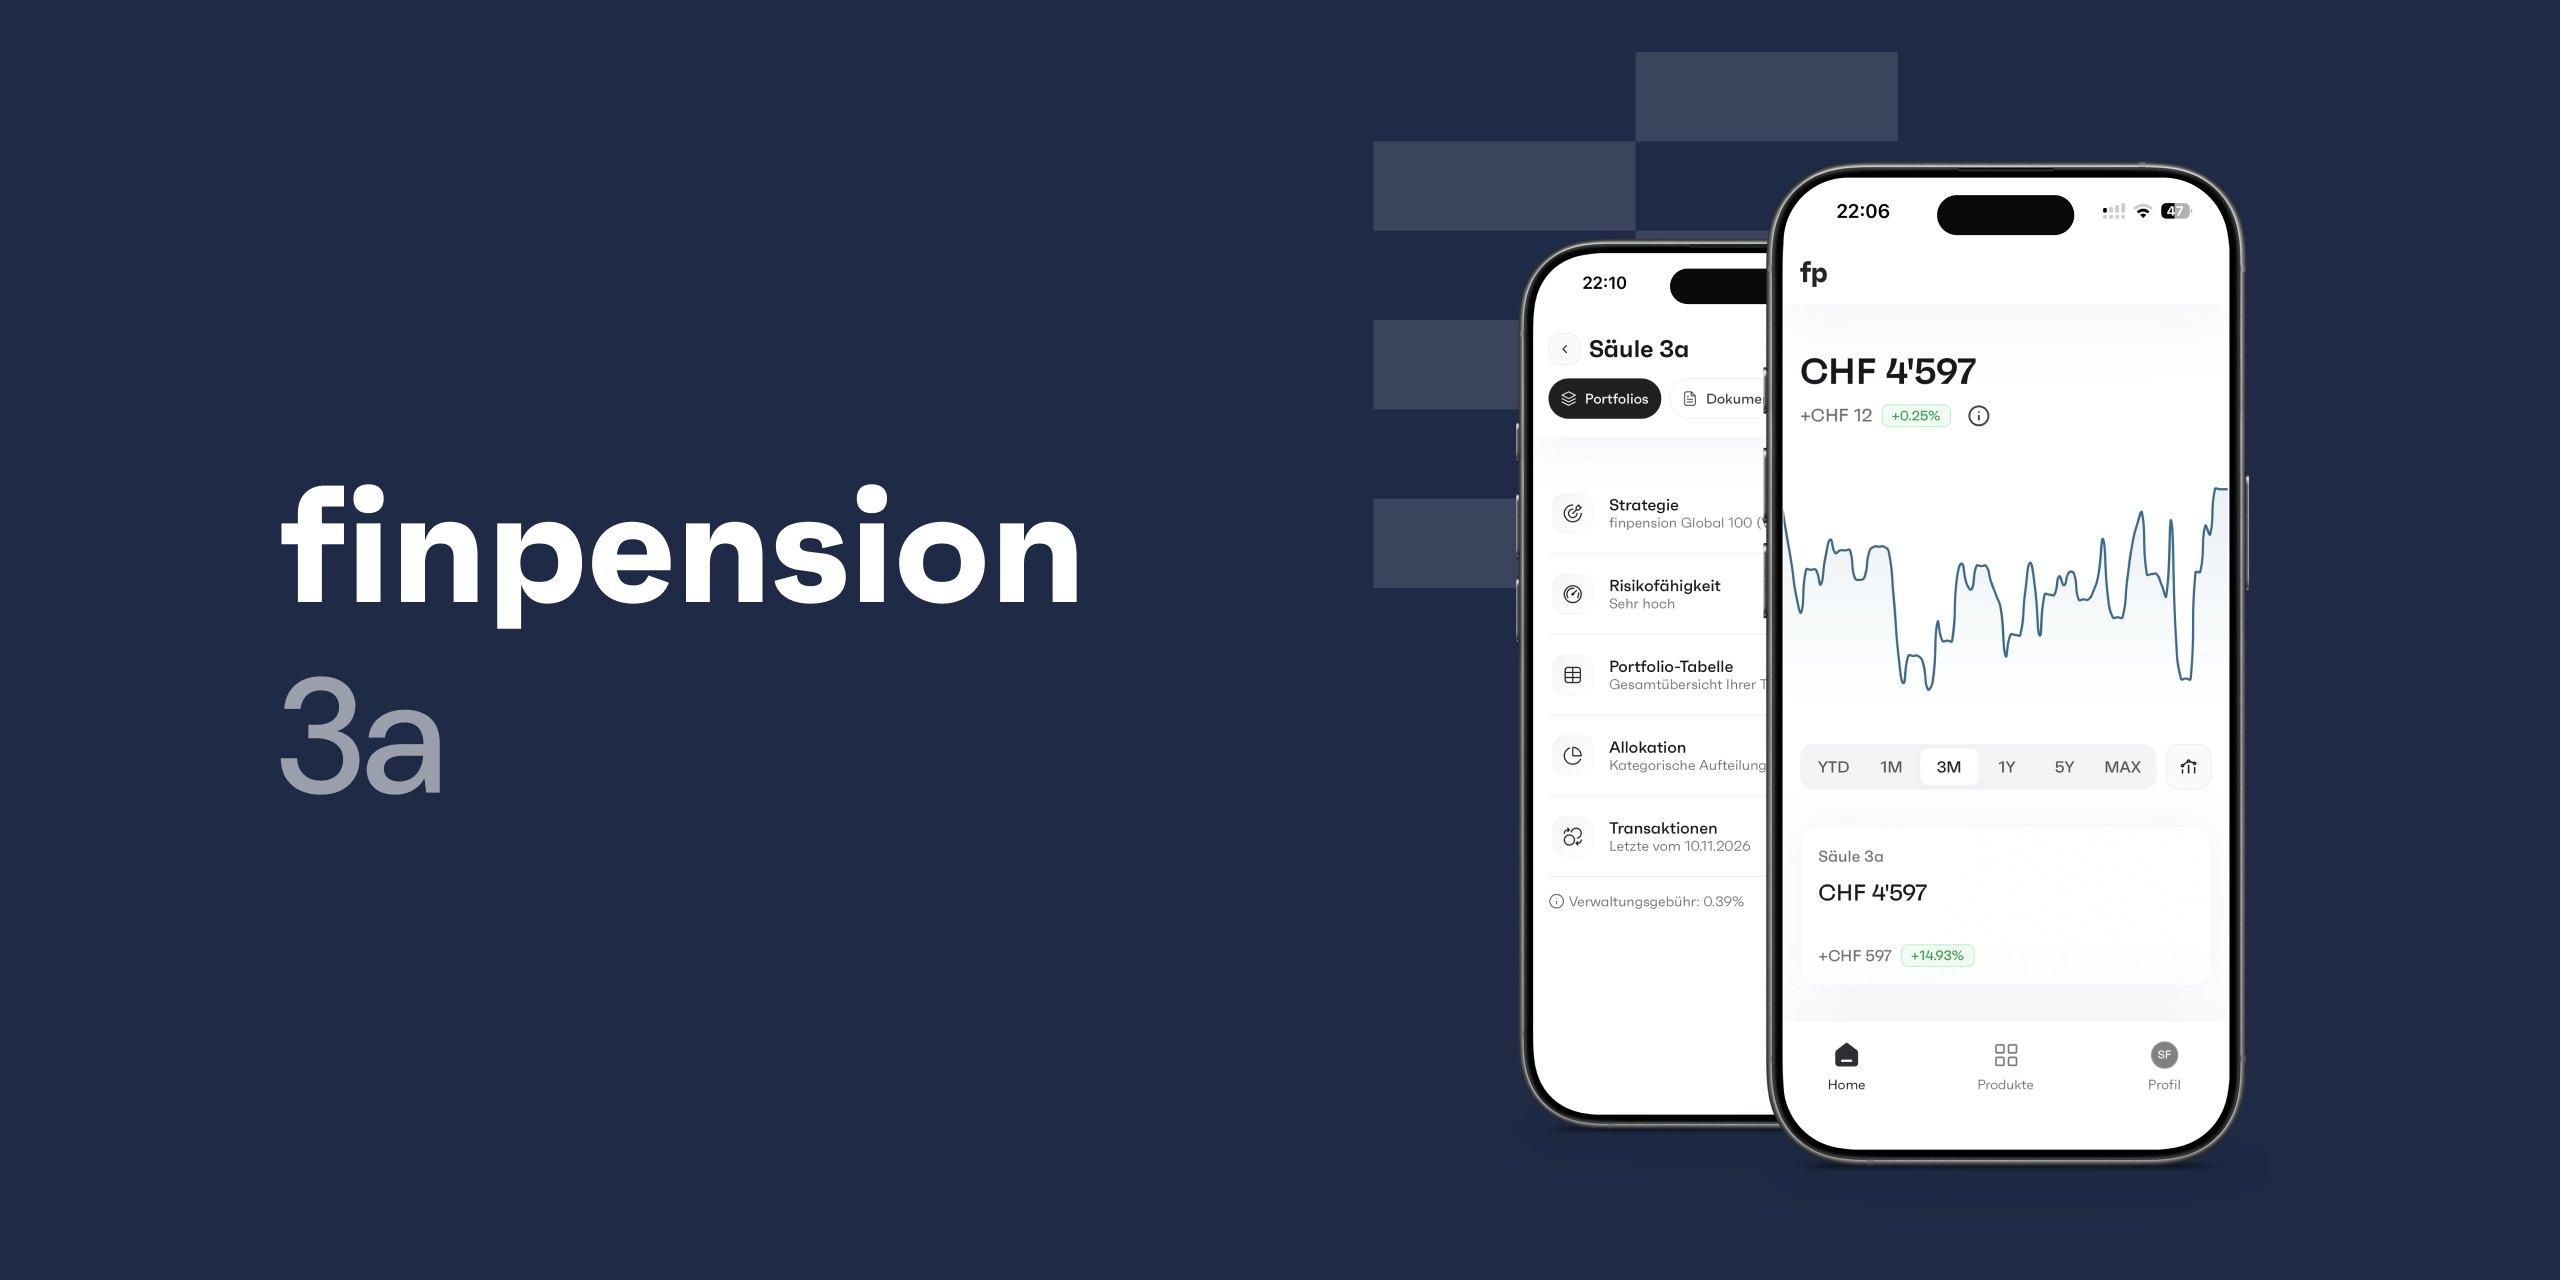
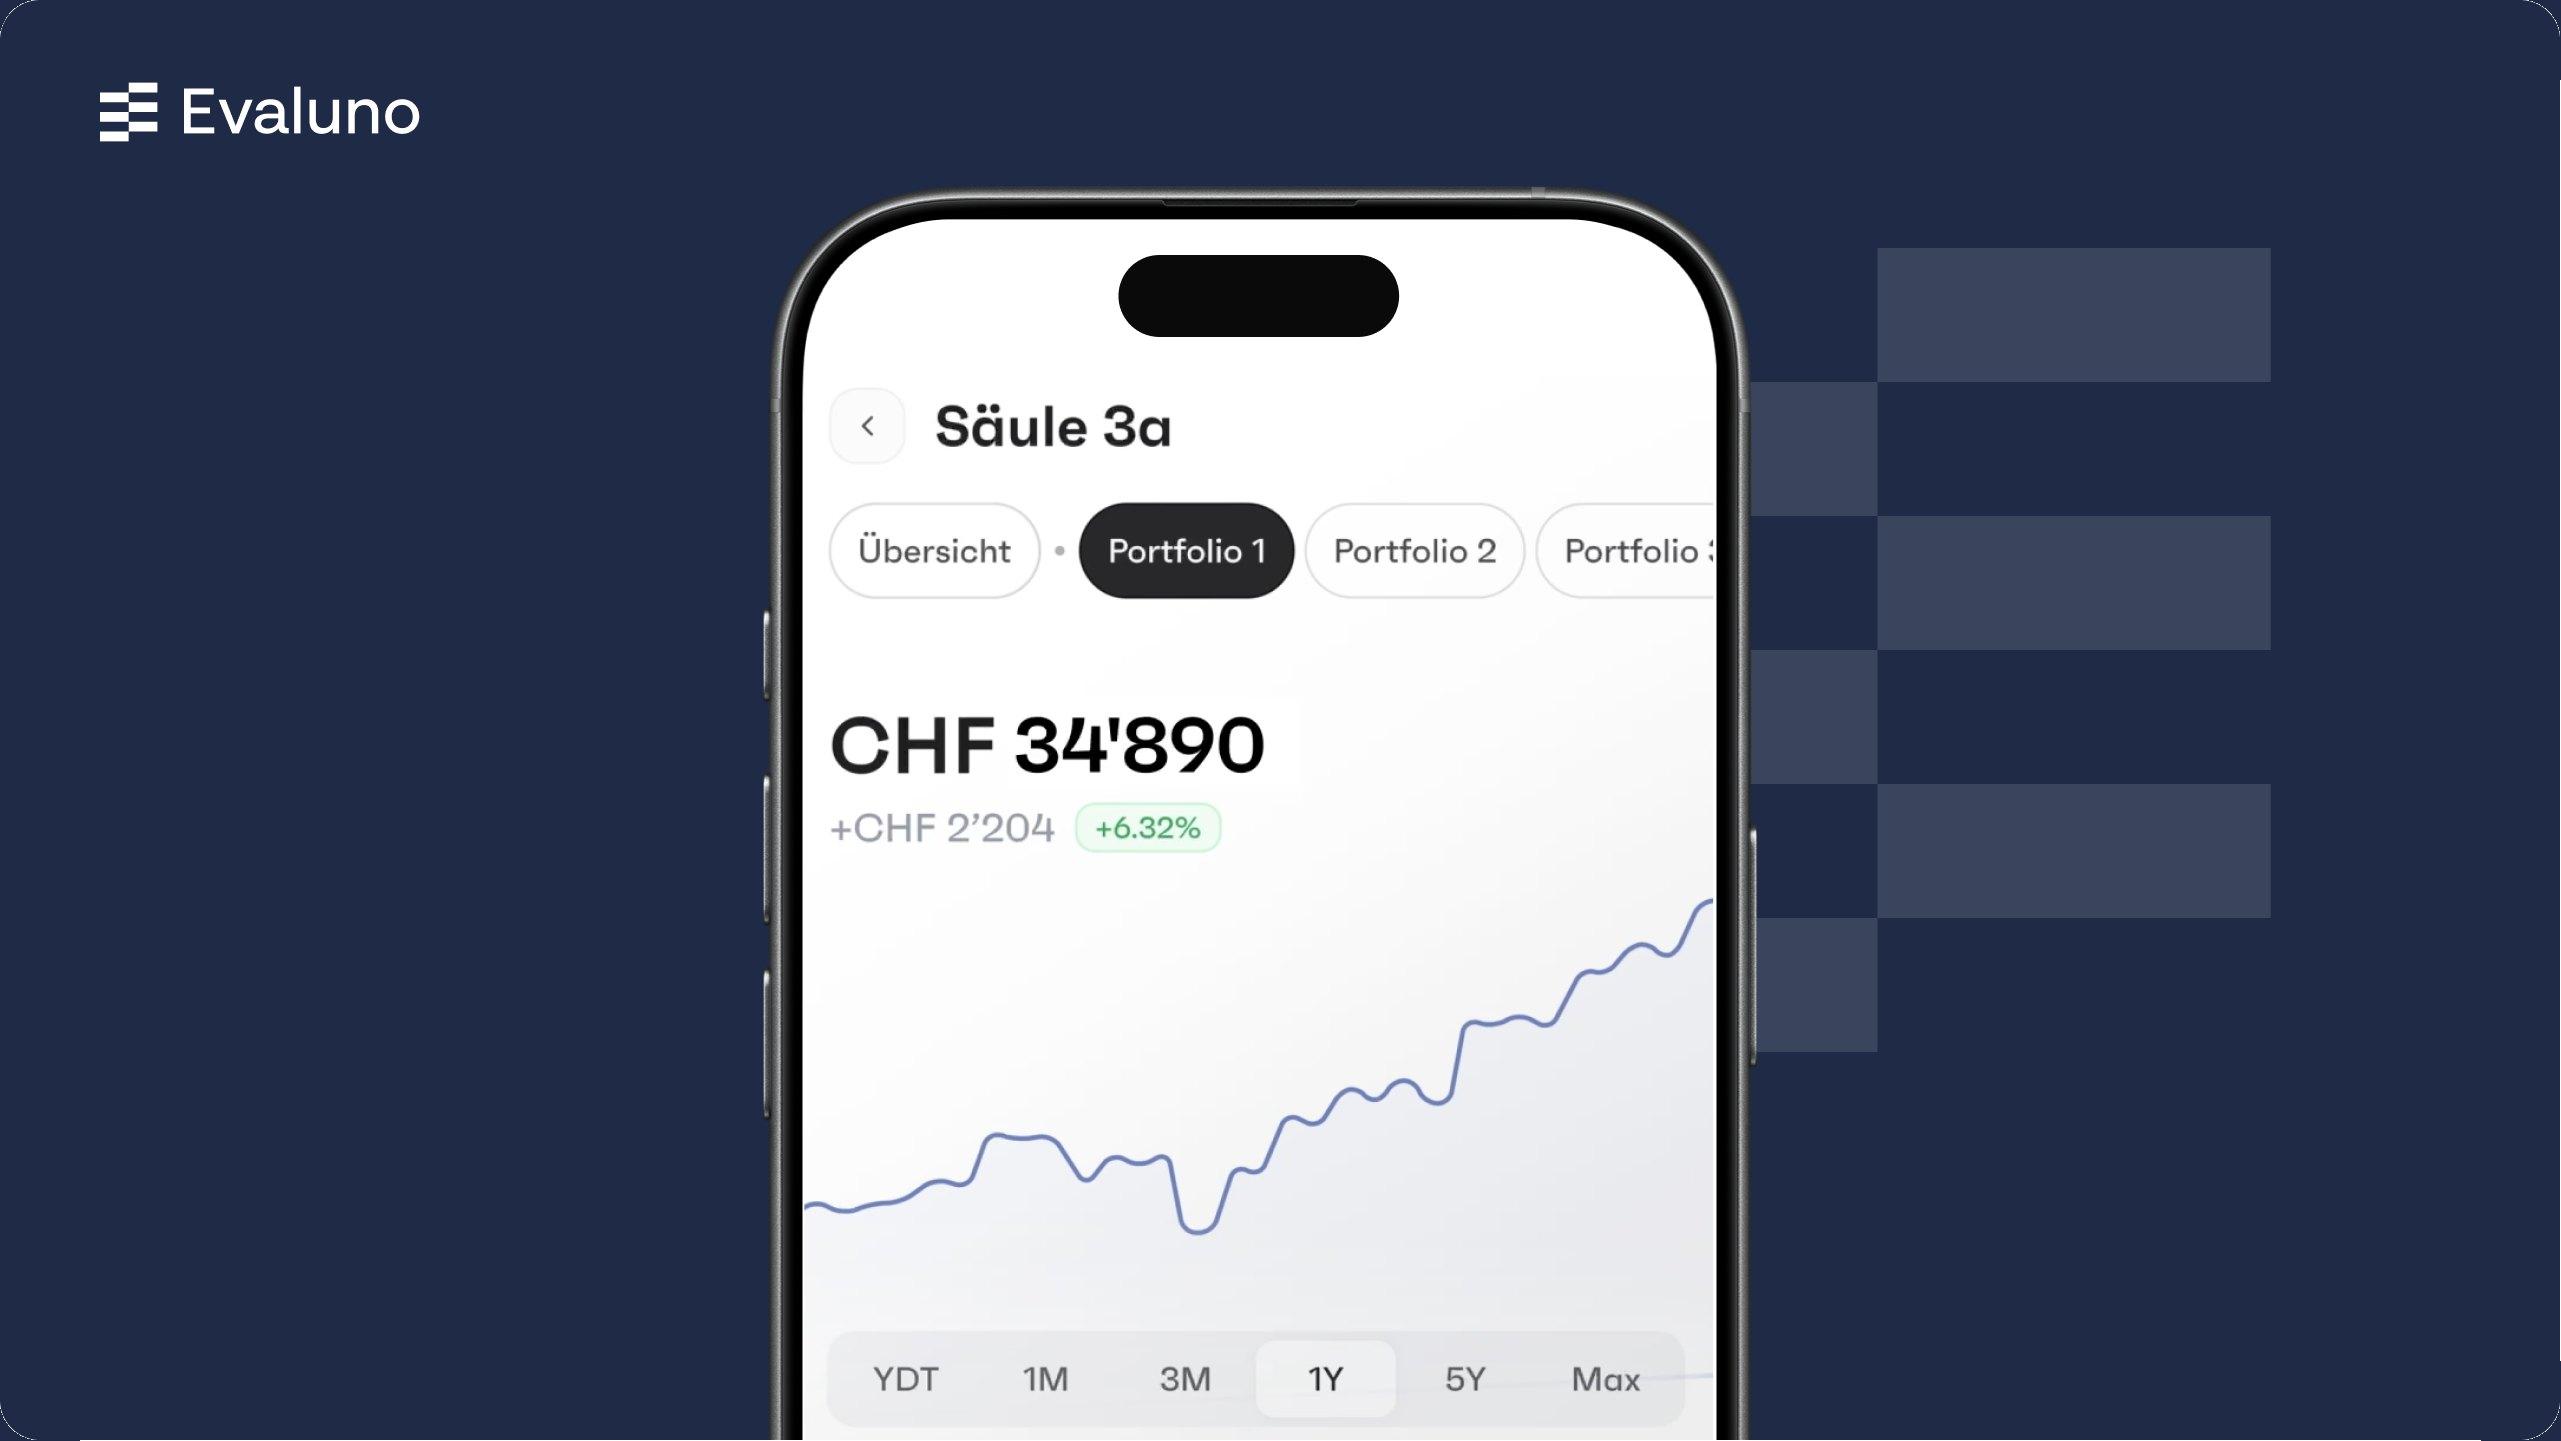
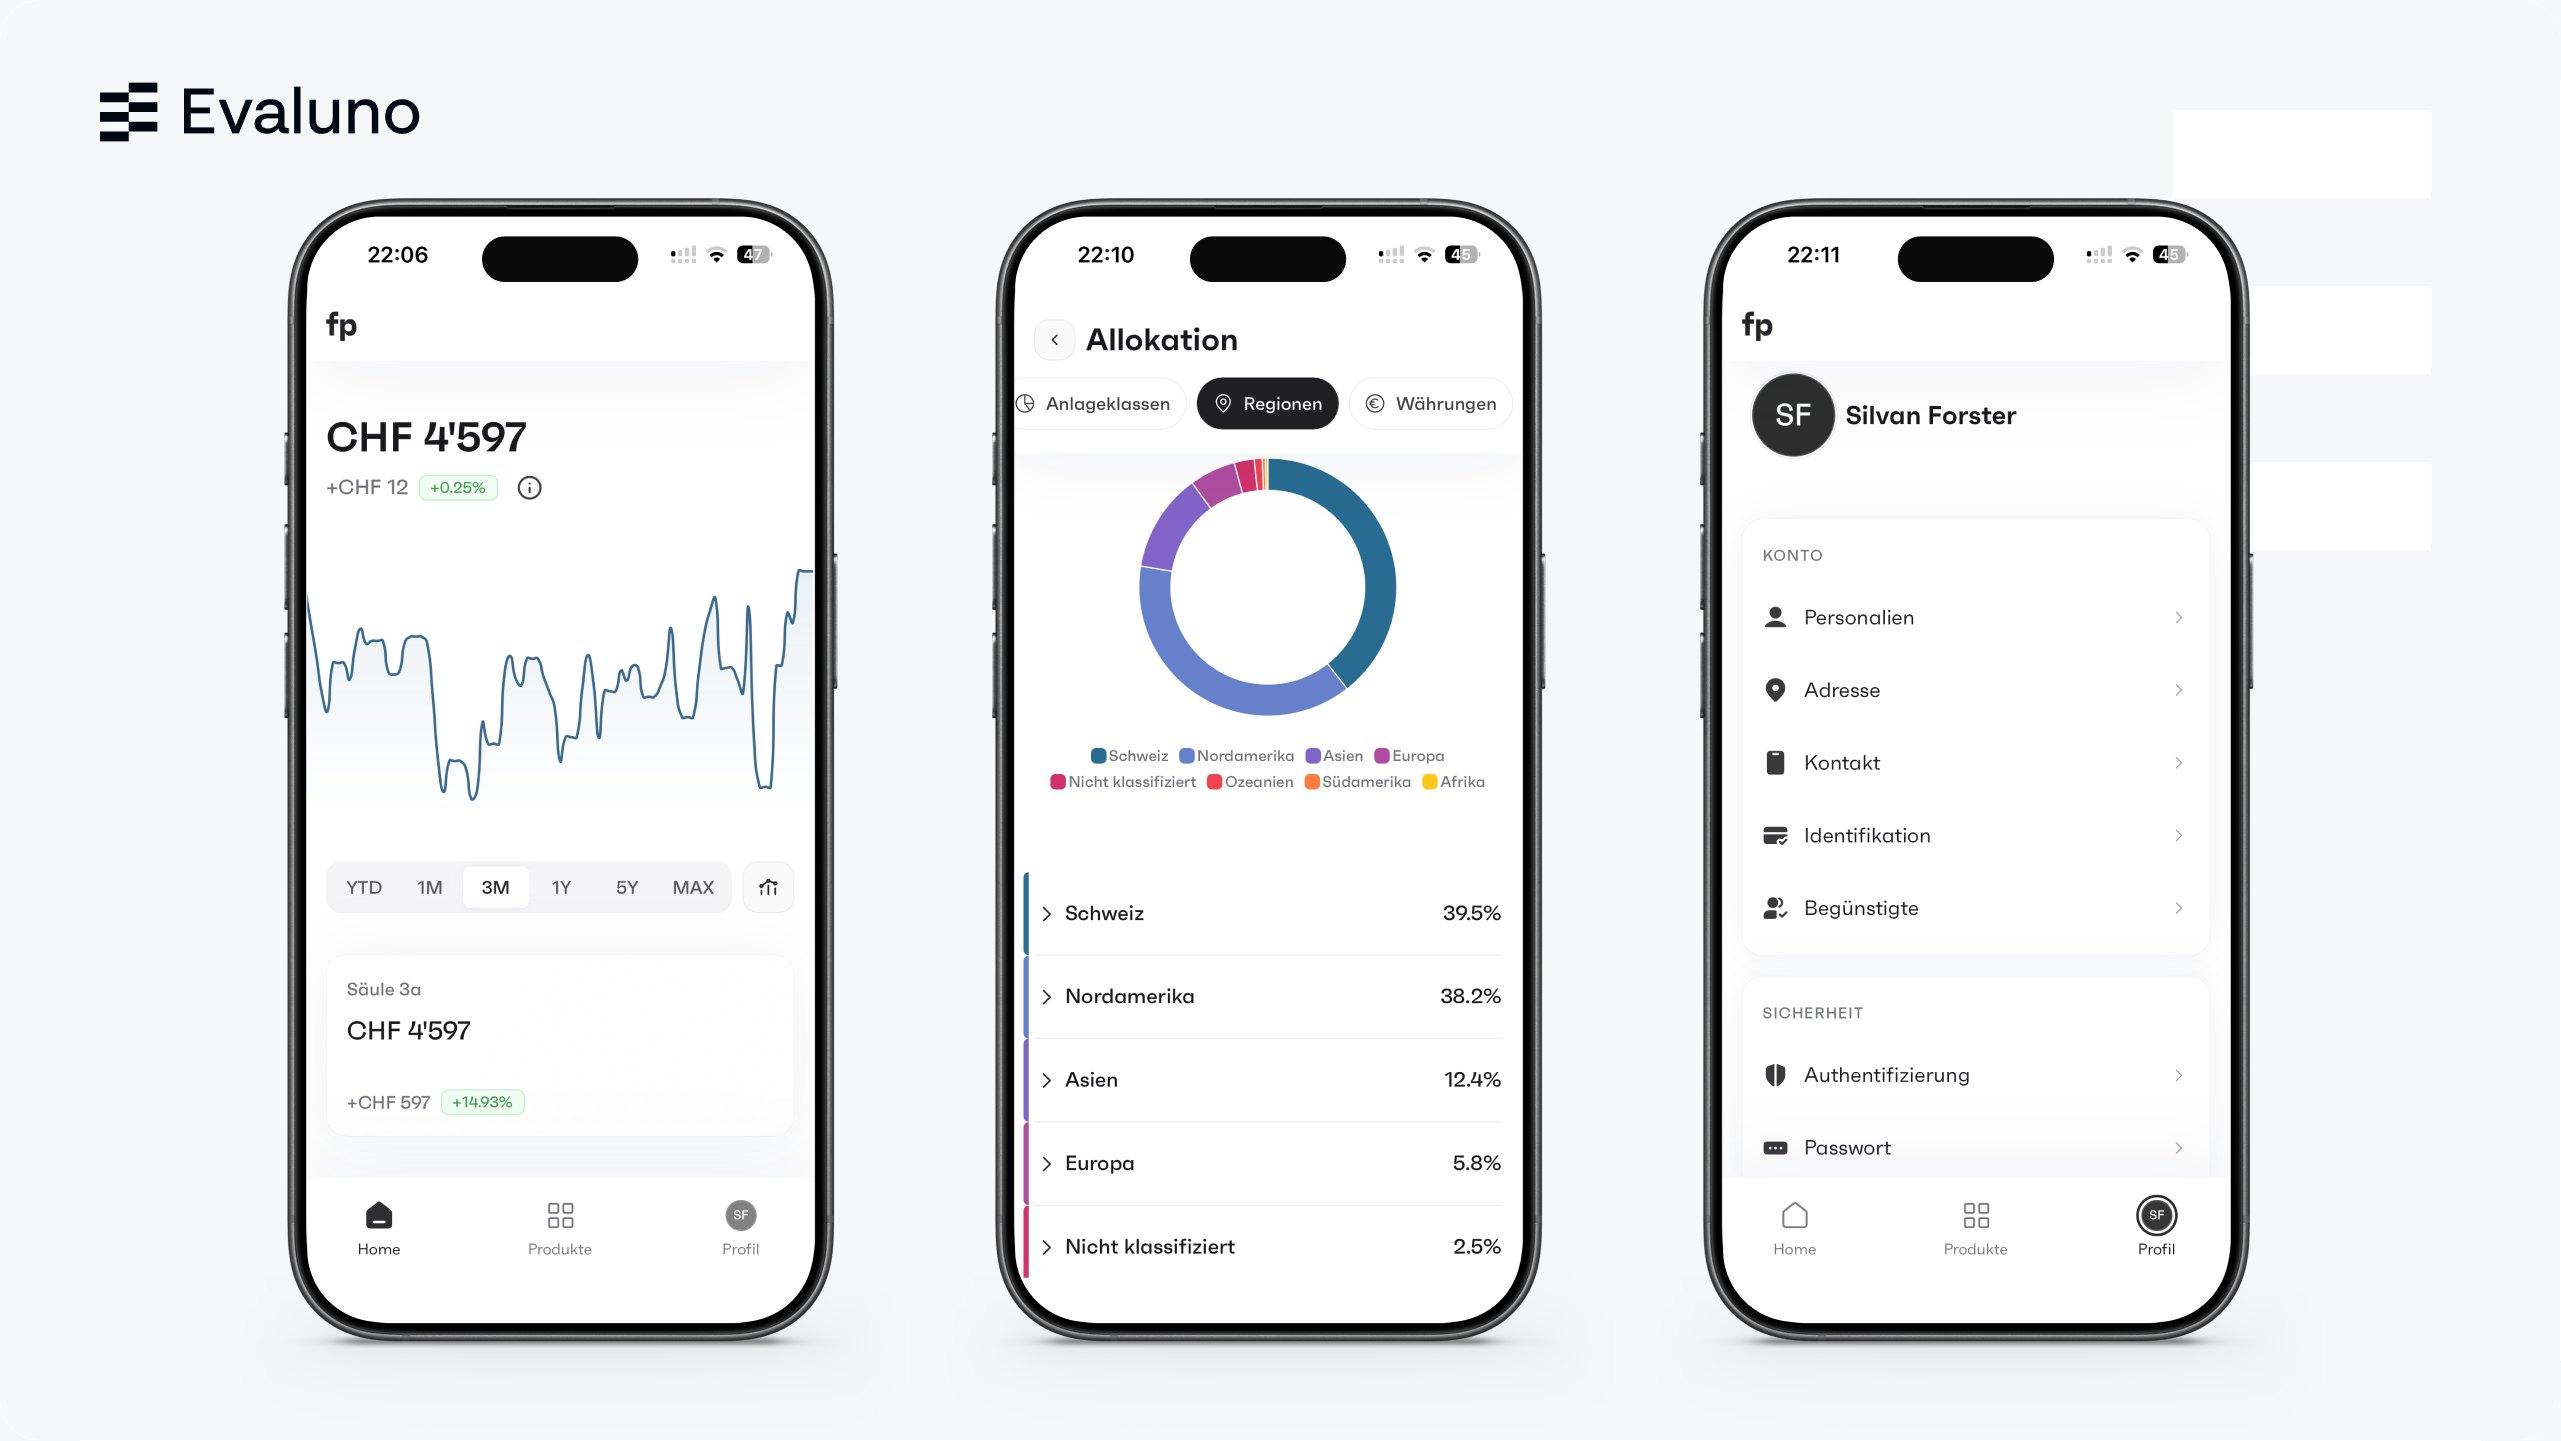
The finpension app has a simple layout and is easy to use. On the home screen, you can see your balance, the performance in francs and per cent and the history over periods from one month to the full time since you started. In the portfolio, you will find the strategy, all funds in a table, the breakdown by region, currency and sector, the ten largest holdings and all transactions. Since the redesign at the end of March 2026, the app looks more modern and offers a dark mode.
Deposits and back payments
You pay in by bank transfer from your e-banking. In the app, under «Deposit», you choose the payment for the current year, a back payment for previous years or a transfer from another provider. Missed payments from 2025 onwards can be made up for up to ten years retroactively; find out more in our guide to pillar 3a back payments. In 2026, with a pension fund, you can pay in up to CHF 7'258 and deduct it from your taxes.
Tax certificate and documents
You will find the tax certificate, statements and other documents in the app, in the documents section of each portfolio.
Support
You can reach finpension’s customer service by email, phone or chat. finpension answers general emails to info@finpension.ch within one working day; for questions about pillar 3a there is the address 3a@finpension.ch. By phone, finpension can be reached on +41 41 500 22 26, Monday to Friday from 8:00 to 12:00 and from 13:15 to 17:00. In the chat, a chatbot or staff can help, and you will also find many answers in the help centre on finpension.ch.
finpension ratings: how satisfied are customers?
Customers rate finpension mostly positively. In the App Store, the finpension app has 4.6 out of 5 stars from 187 ratings, on Google Play 4.5 out of 5 from 203 reviews. A new finpension app has been available since the end of March 2026. In the reviews since then, the low fees, the modern design and the ease of use are praised most often, which matches the Evaluno test. The login problems shortly after the switch no longer appear in recent reviews. Criticism today mainly concerns missing analyses, such as an overview of all holdings or the total of all deposits.
How users rate finpension
As of 17.11.2026
- App Store
- 187 ratings
- 4.6 out of 5 stars
- Google Play
- 203 reviews
- 4.5 out of 5 stars
Often praised
- Low fees
- Own strategy, wide choice of funds
- Modern design with dark mode
- Easy to use
Often criticised
- Missing key figures and overall overview
- Fewer features than the old app
- Payouts sometimes take a long time
Sources: App Store and Google Play (Switzerland), accessed on 17.11.2026. Star ratings across all years, praise and criticism from the reviews since the new app (end of March 2026).
finpension code: CHF 25 fee credit with a referral code
With the referral code PQMK7S, you get a credit of CHF 25 on your fees. It is also called a recommendation code, promo code or voucher code. You enter the code in the last step of registration or when opening a new product; afterwards you can still do so within 24 hours in your profile, in the section for inviting friends. You receive the credit once you pay in at least CHF 1'000 within 12 months, and a transfer counts too. The code is valid until 31.12.2026 and applies to finpension 3a, finpension Invest and finpension Vested benefits. You will find all the conditions on the Evaluno page for the finpension code. Evaluno receives a commission for accounts opened with the code.
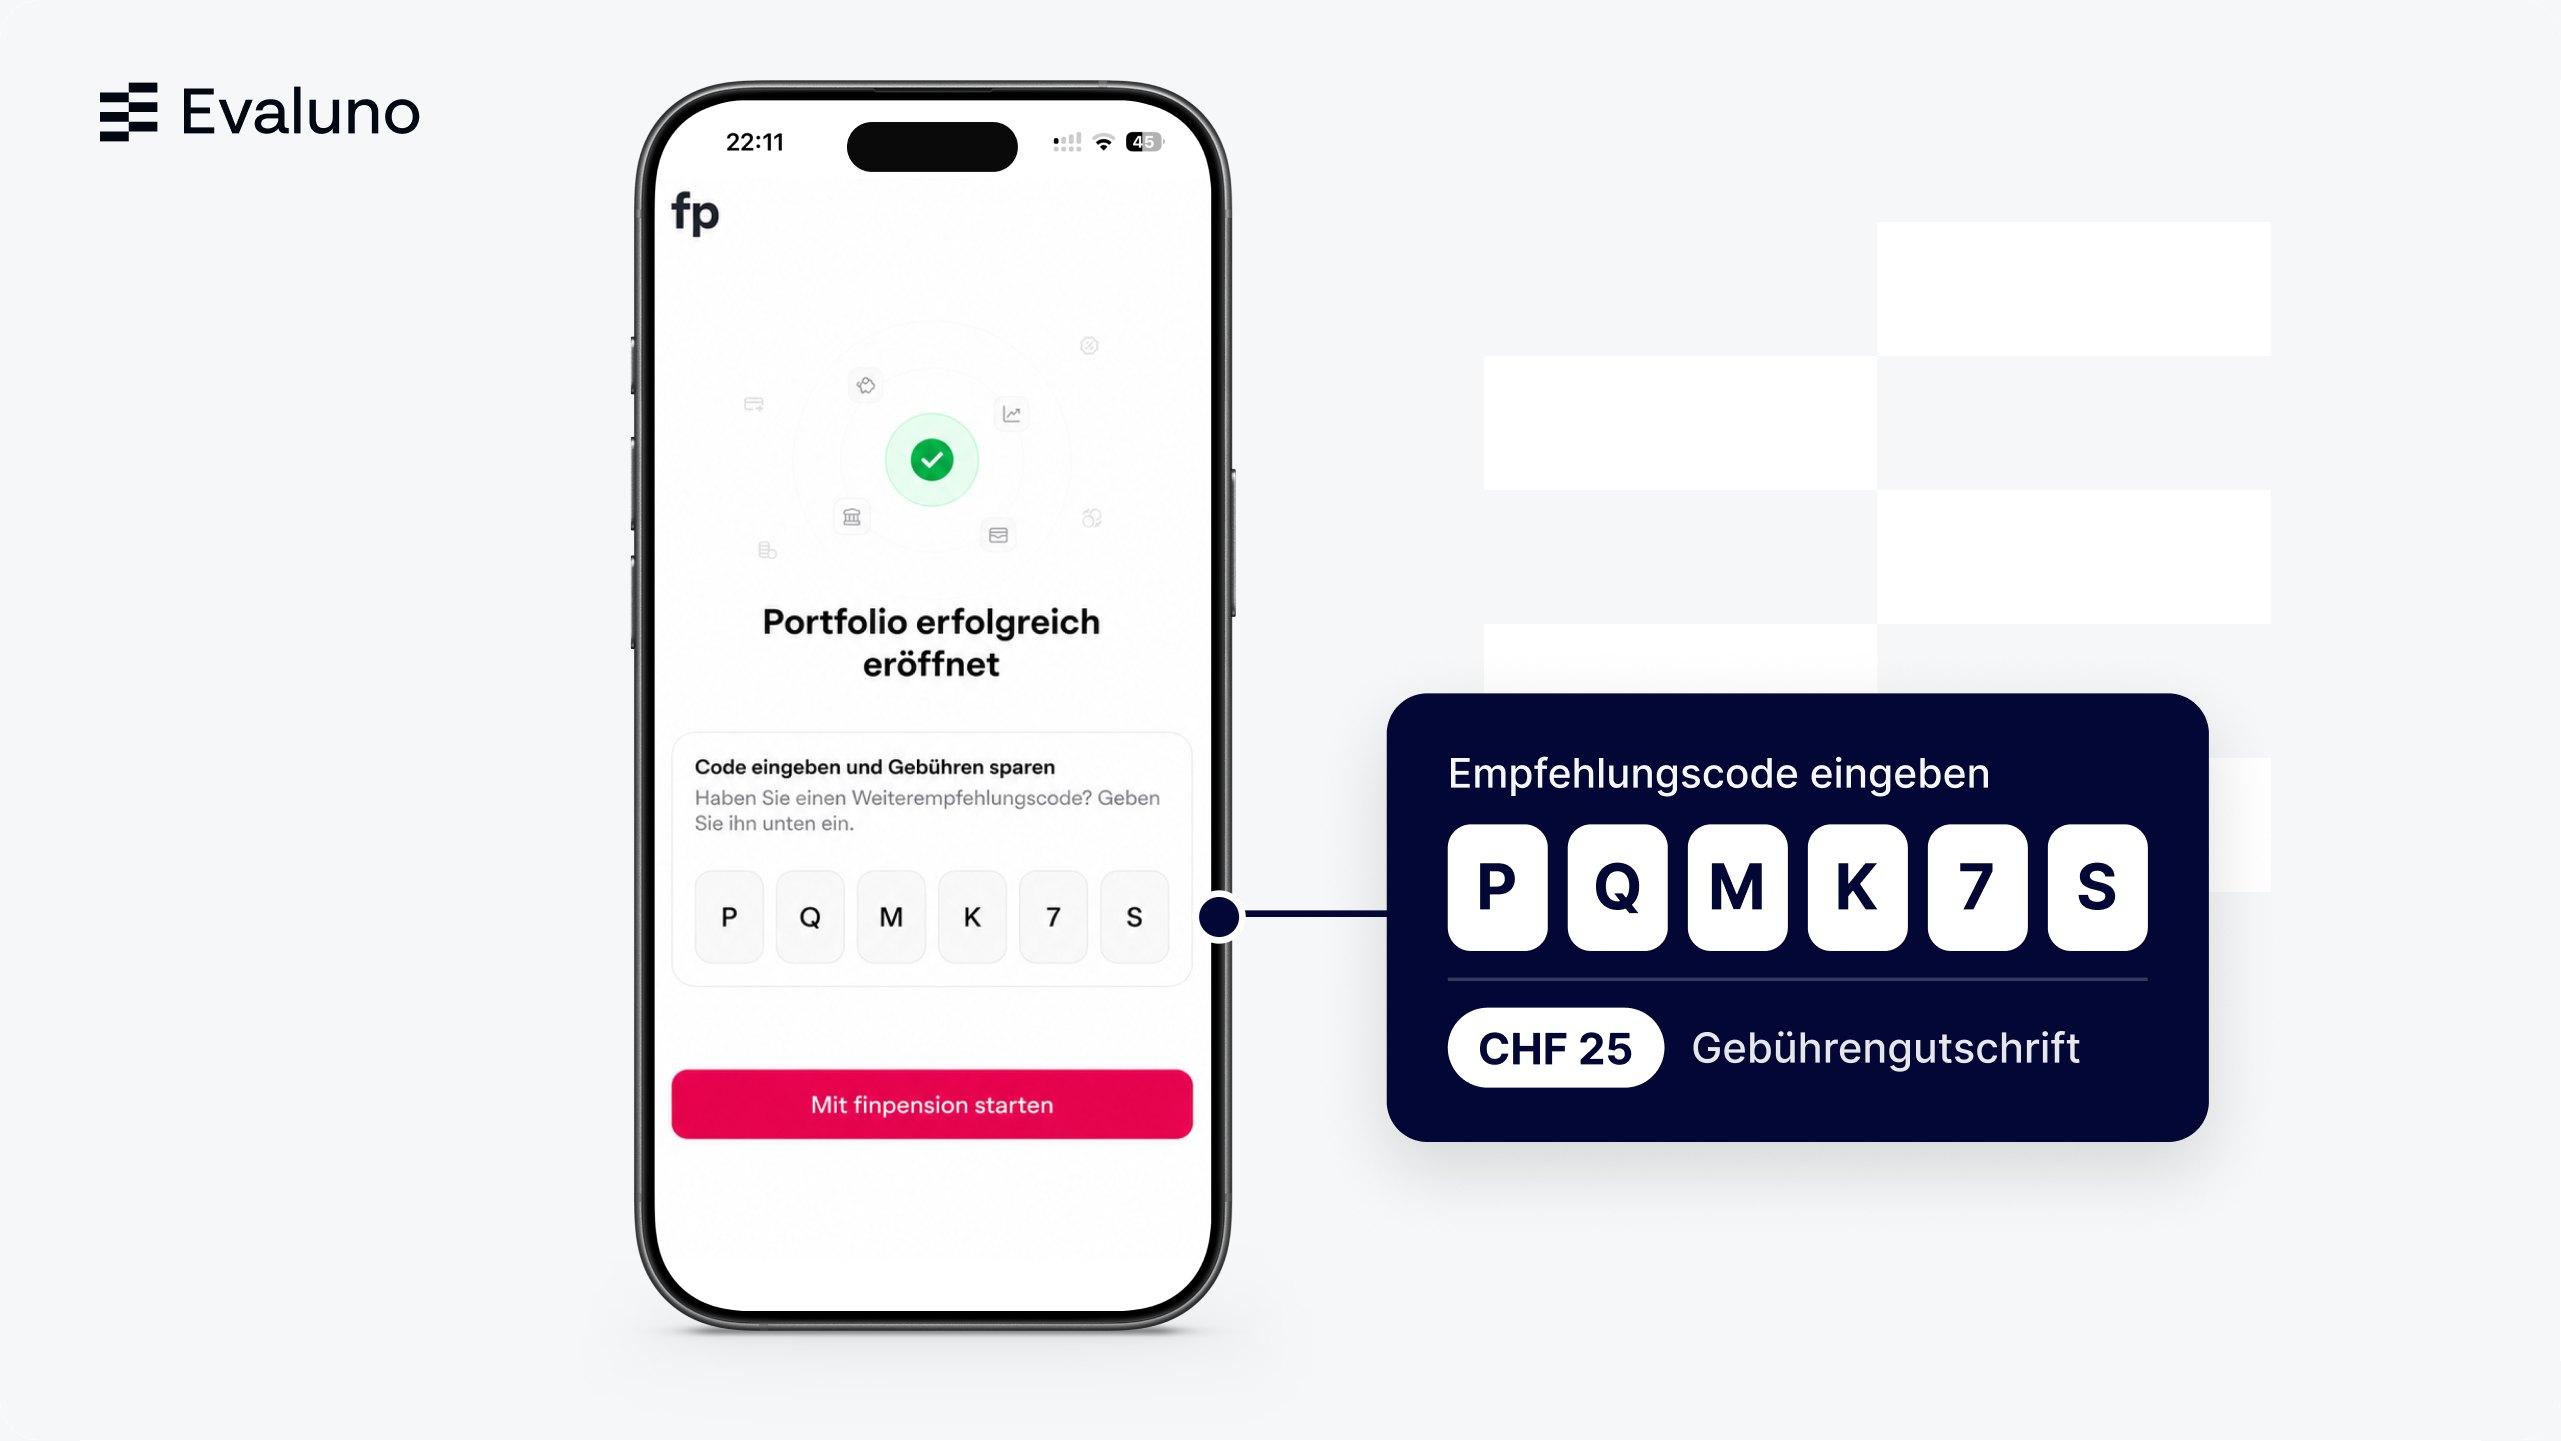
How to redeem the finpension code
- Open an account in the finpension app or in the browser
- Enter the code PQMK7S in the last step of registration, or afterwards within 24 hours in your profile, in the section for inviting friends
- Pay in at least CHF 1'000 within 12 months, also by transfer
- The credit is automatically offset against your fees
Opening a finpension 3a account: step by step
Opening an account is fully digital in the app or in the browser and takes a few minutes. You can open the account between the ages of 18 and 70, and you may only pay in if you have earned income subject to AHV. There is no minimum amount.
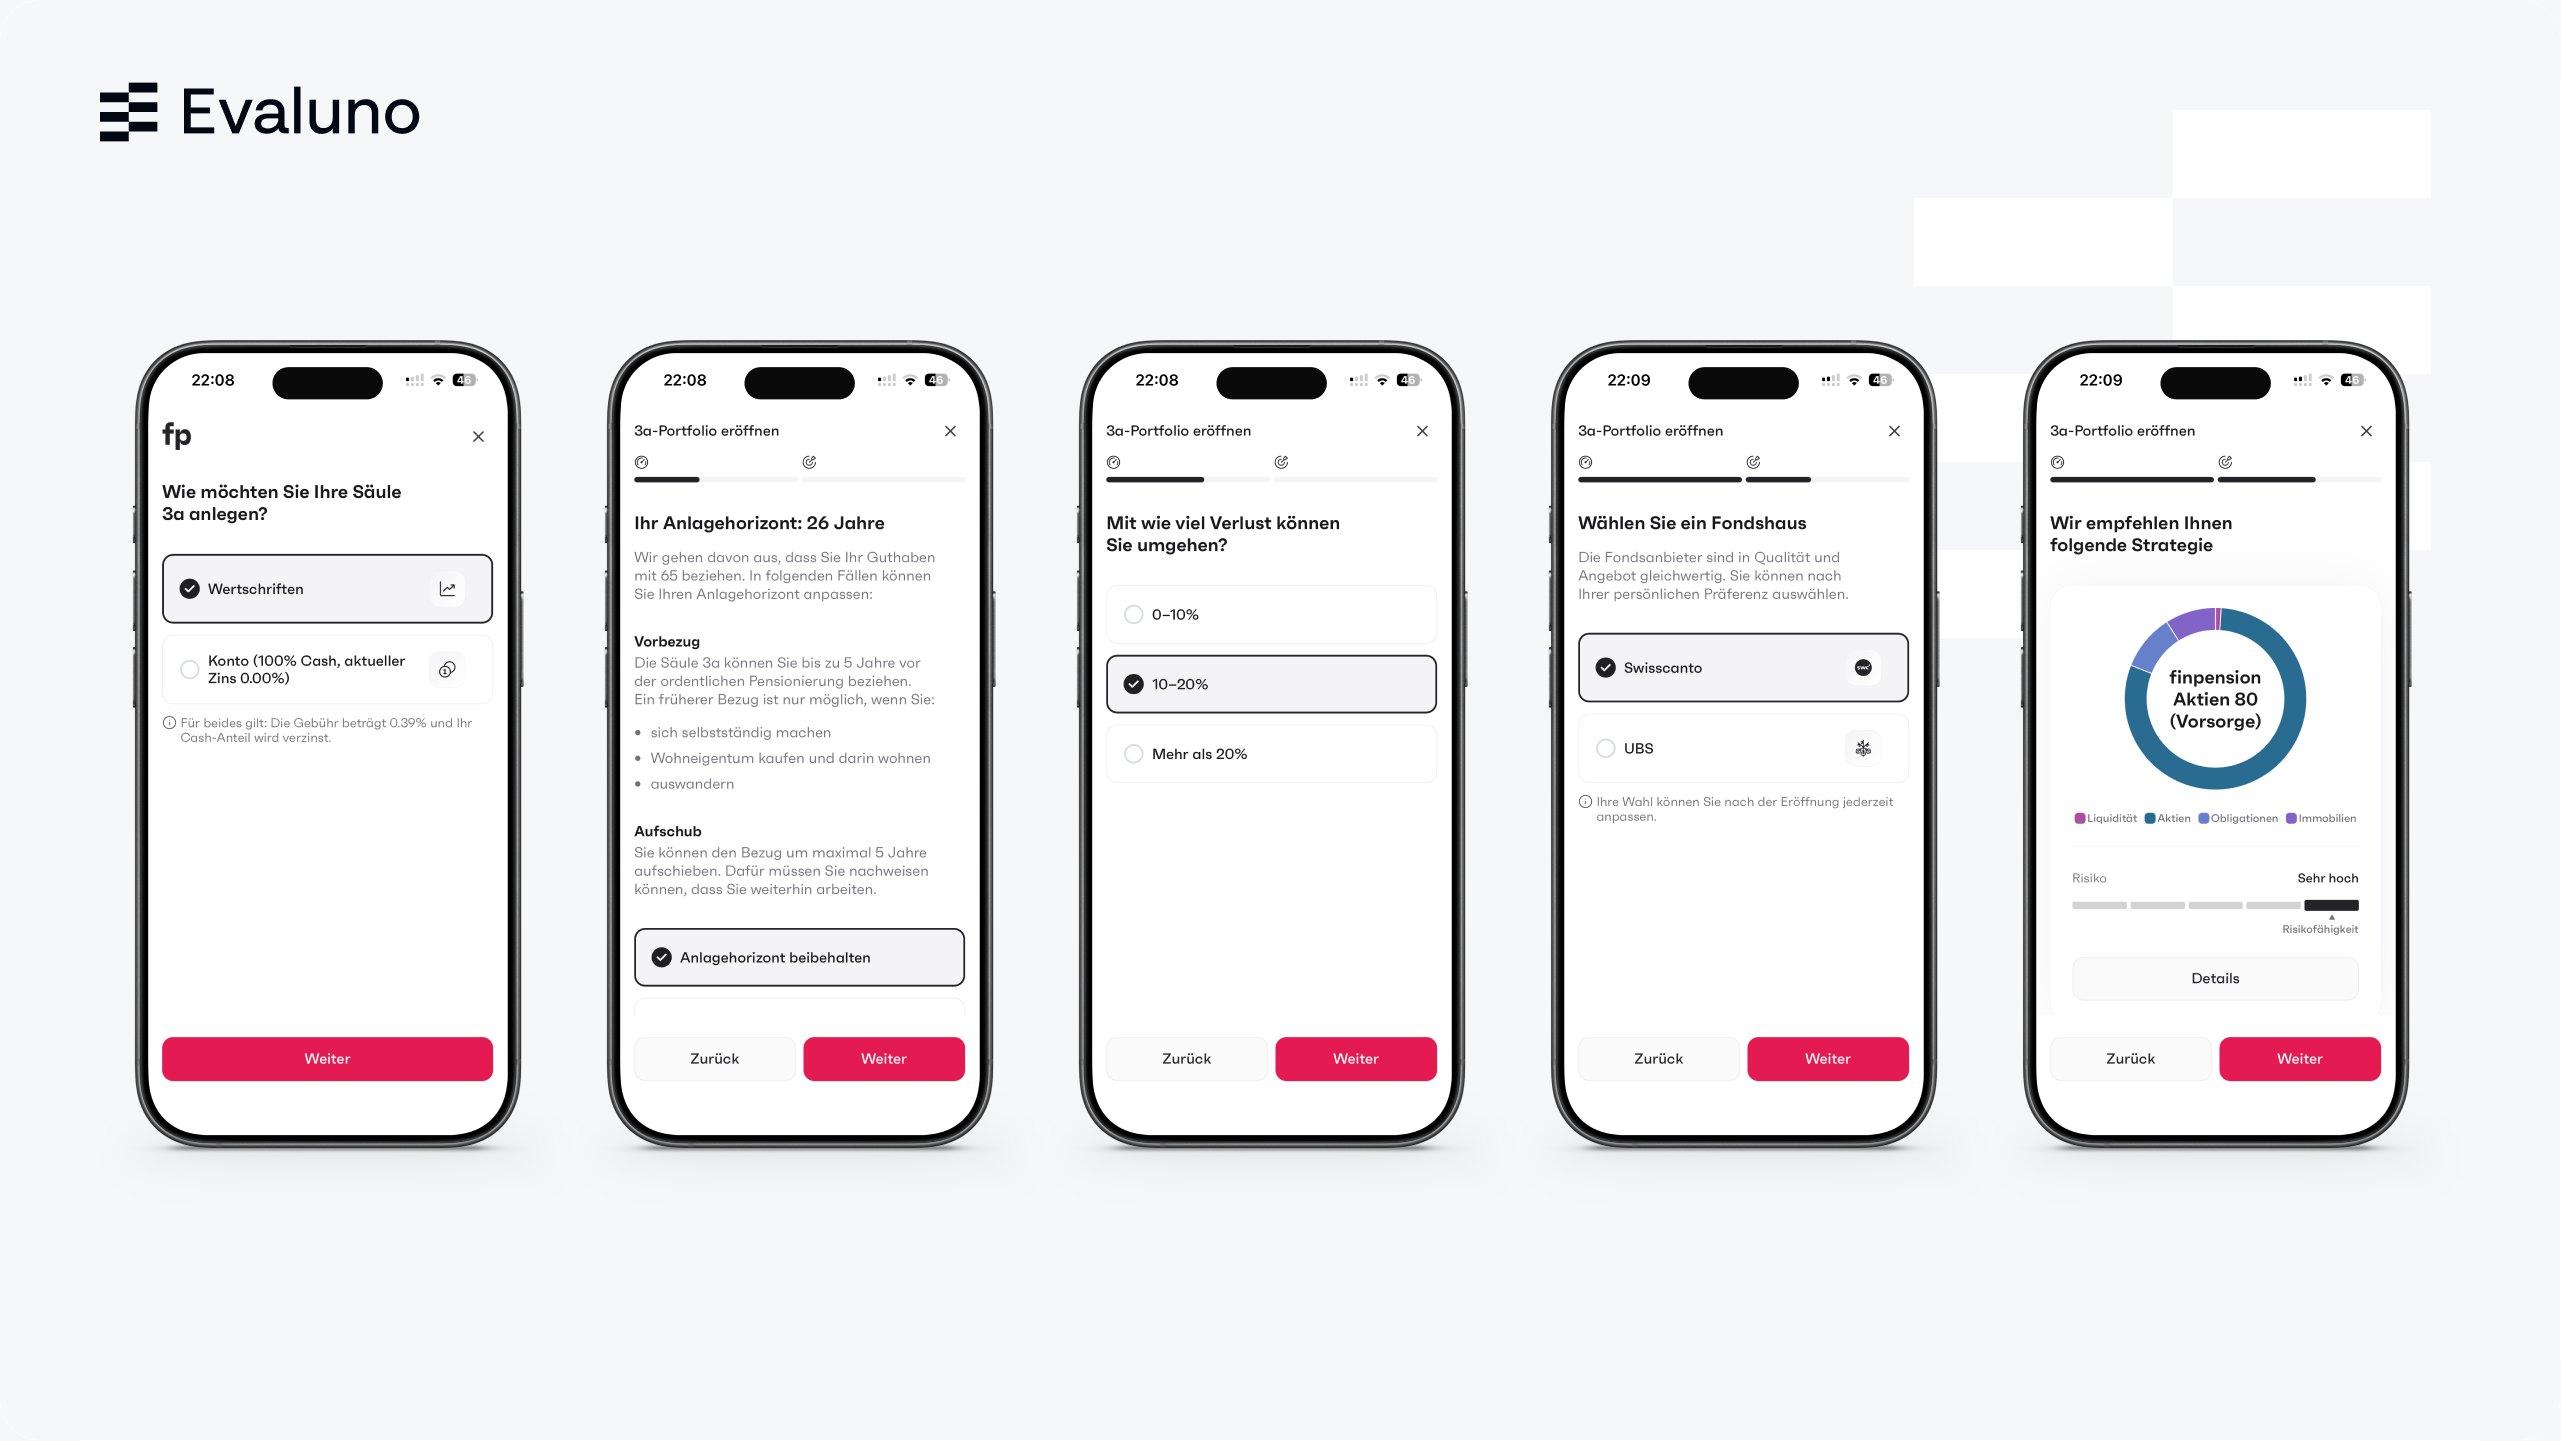
- Download the app or register on finpension.ch
- Choose the type of investment: securities or an account with 100 % cash
- Determine your risk capacity: investment horizon, loss tolerance and knowledge
- Choose the investment focus, fund house and strategy
- Enter your personal details, enter the code PQMK7S and transfer the first payment
Switching your pillar 3a to finpension
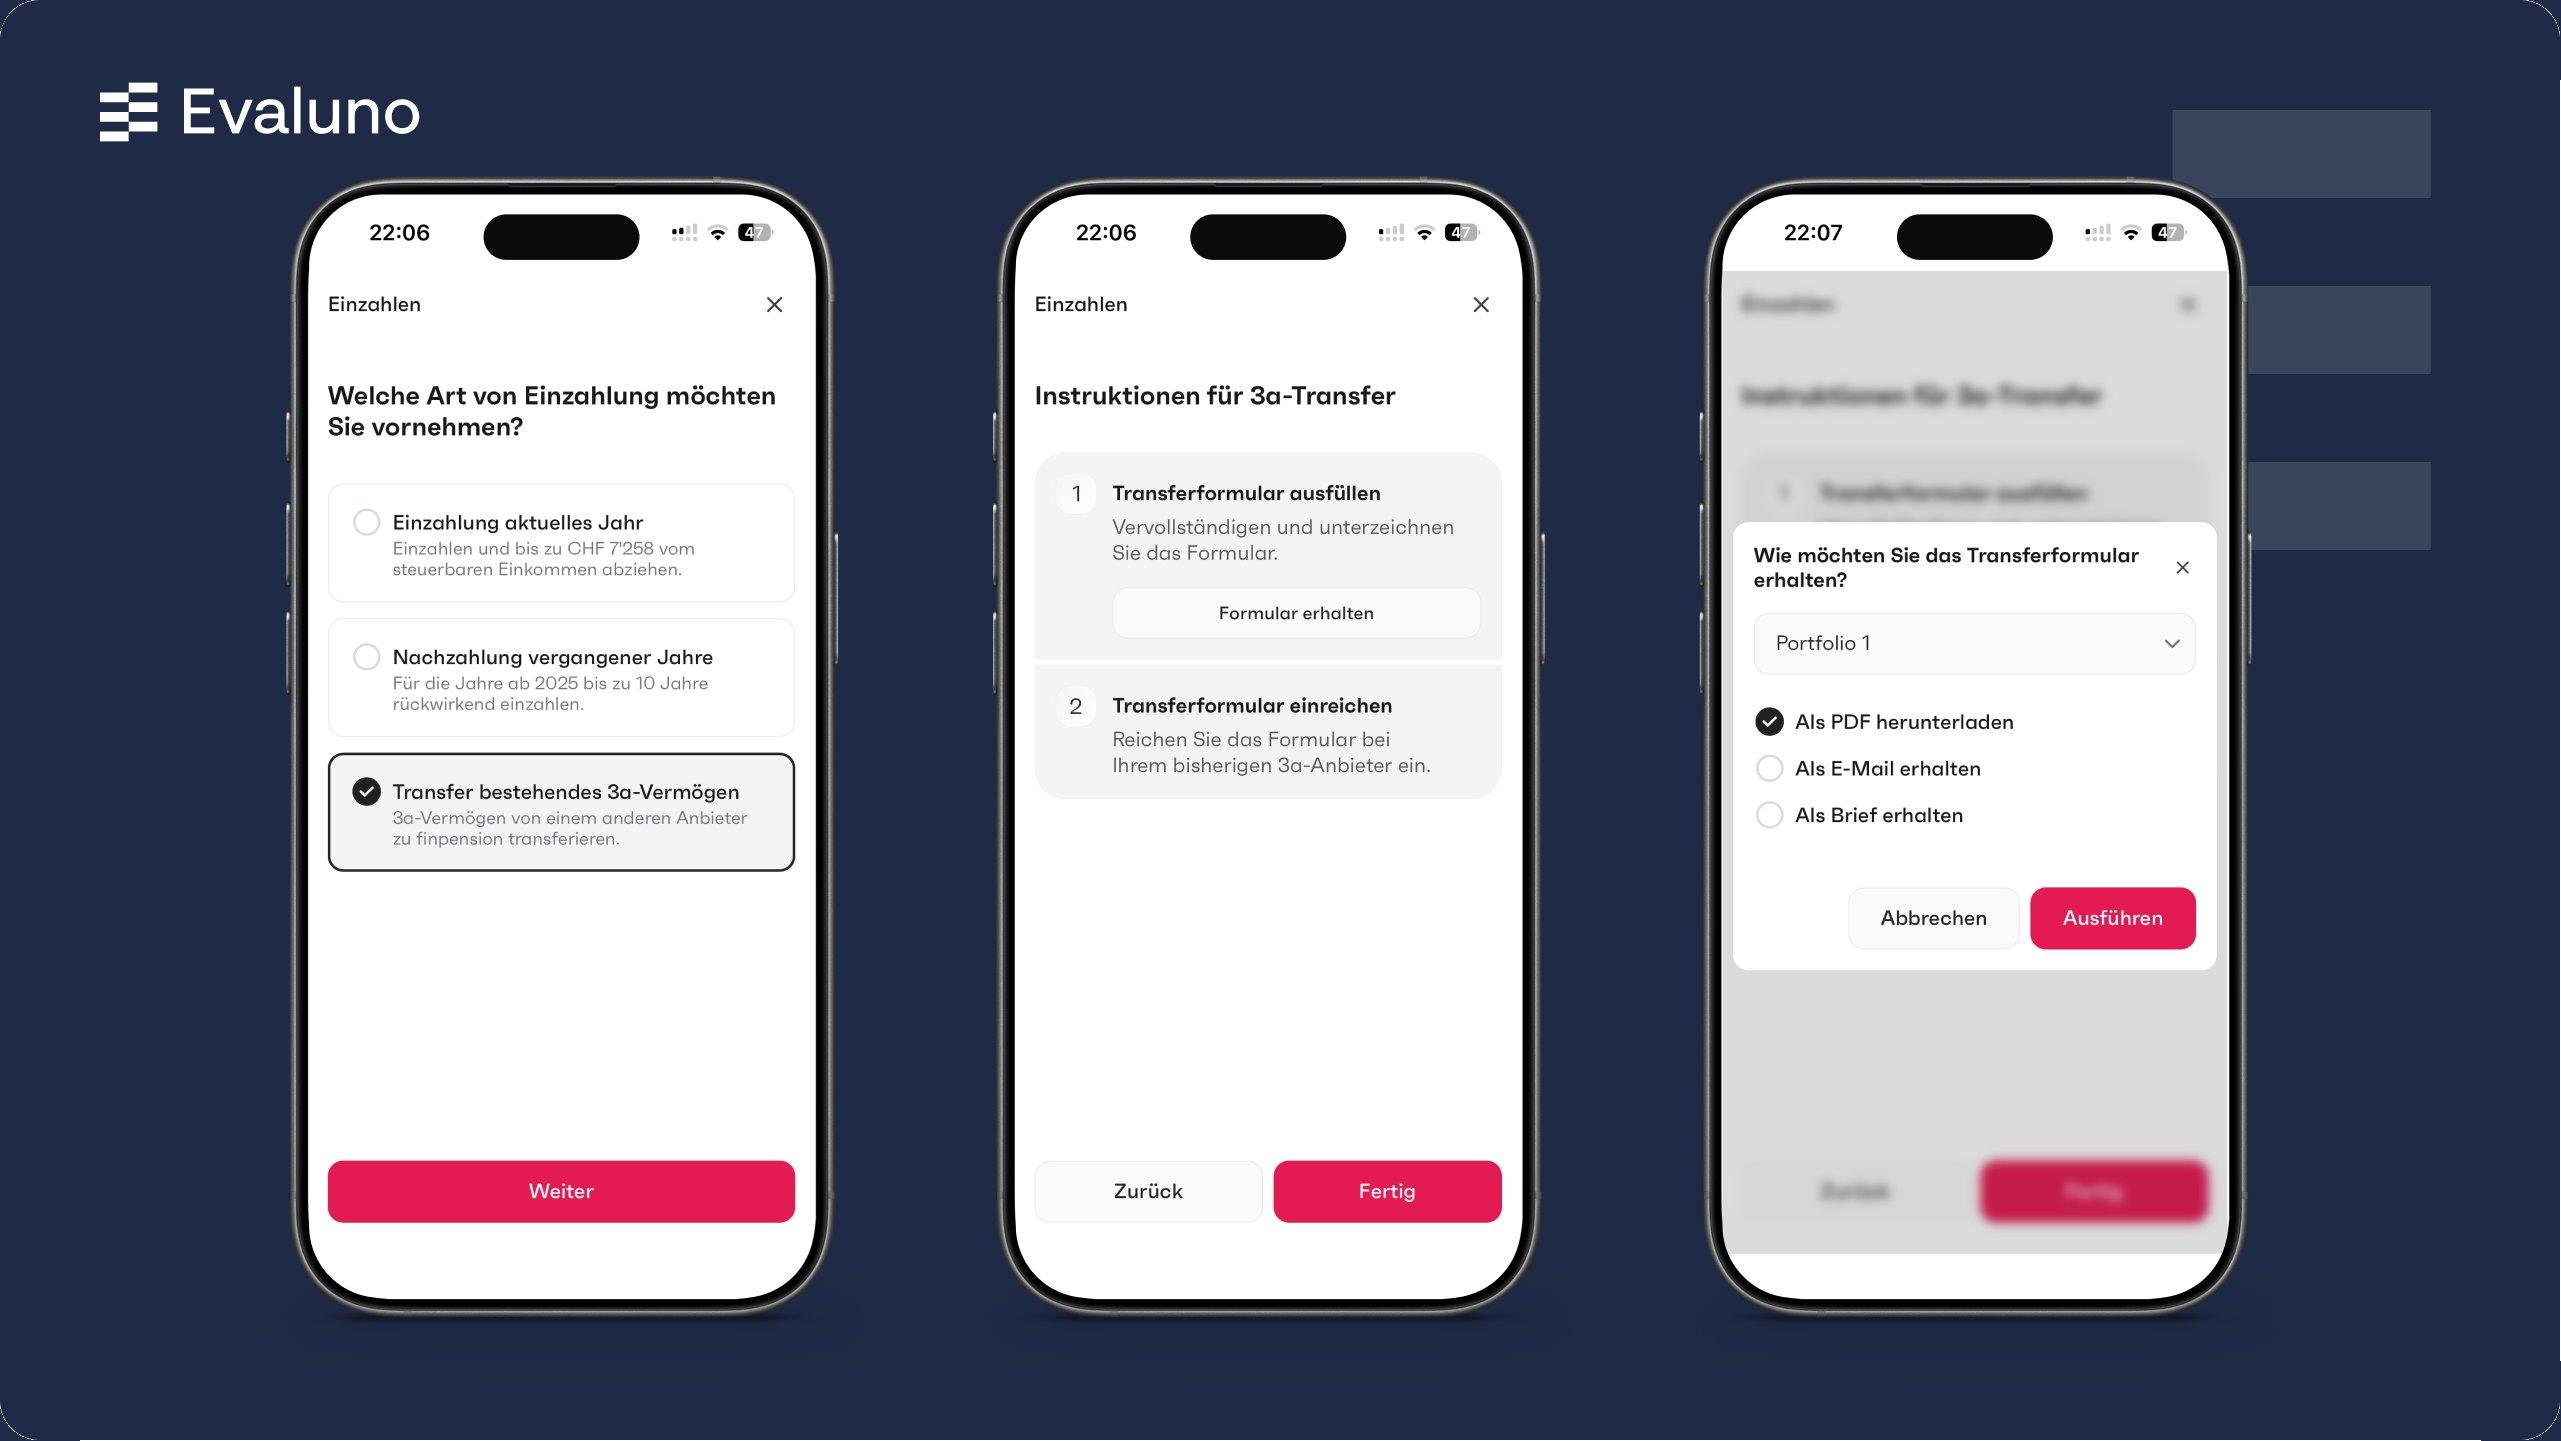
You start the switch in the app under «Deposit» with «Transfer existing 3a assets». You receive the transfer form as a PDF, by email or by post, sign it and submit it to your current provider. finpension does not charge a fee for the transfer. General tips on switching can be found in our guide to switching your 3a account.
Pros and cons of finpension 3a
Pros
- Advantage: Very low fees
- Advantage: Own strategy from over 130 index funds
- Advantage: Up to 99 % equities
- Advantage: Choice of Swisscanto or UBS as fund house
- Advantage: Simple, fully digital opening
- Advantage: Up to 5 portfolios, each with its own strategy
Cons
- Disadvantage: Fee on the 3a account too, no interest
- Disadvantage: 5-year return behind VIAC and frankly
- Disadvantage: Fees for early withdrawal and pledging
Verdict: is finpension 3a worth it?
Yes, if you want to invest your pillar 3a in securities at low cost and choose the strategy yourself. finpension charges a fee of 0.39 % a year, offers 18 strategies with up to 99 % equities and lets you put together your own strategy from over 130 index funds. The app is clear and opening an account is simple. The drawbacks are the returns over the last five years and the 3a account without interest, on which the fee still applies. If you also want to save without investing, frankly or VIAC will suit you better.
Frequently asked questions about finpension 3a
Yes, for anyone who wants to invest their pillar 3a in securities at low cost. At 0.39 % a year, finpension is one of the cheapest providers, and you can put together your strategy freely. For pure saving without investing, finpension is less suitable because the 3a account pays no interest.
finpension 3a costs 0.39 % a year. This includes management, purchases, sales, strategy changes and transfers. For the ready-made strategies, fund costs of 0.00 to 0.02 % come on top; with your own strategy they depend on the funds. For an early withdrawal and a pledge, finpension charges CHF 250 and CHF 200 respectively.
Yes. With the referral code PQMK7S, you get a CHF 25 credit on your fees. You enter it when opening an account or a new product and pay in at least CHF 1'000 within 12 months, also by transfer. The code is valid until 31.12.2026.
Both are among the cheapest digital 3a providers: finpension costs 0.39 to 0.41 %, VIAC 0.41 to 0.44 % a year. Over five years, VIAC was ahead with Global Nachhaltig 100 (+44.4 %) compared with finpension Global 100 (+37.0 %). Both allow up to 99 % equities and your own strategy, and VIAC also pays 0.20 % interest on the 3a account.
At 0.39 to 0.41 % a year, finpension is cheaper than frankly at 0.43 to 0.47 % and allows up to 99 % equities as well as your own strategy. Over five years, frankly was ahead with Extreme 95 Responsible (+44.5 %) and charges no fee on the 3a account.
finpension is run by finpension AG, based in Lucerne. The contractual partner for pillar 3a is the finpension 3a Vorsorgestiftung, which is supervised by the Central Swiss supervisory authority for occupational pensions and foundations (ZBSA).
Yes. The securities belong to the finpension 3a Vorsorgestiftung and do not form part of the bankruptcy estate if a bank fails; money in the 3a account is given preferential treatment up to CHF 100'000. The value of the securities can fluctuate.
It depends on the strategy. To 30.9.2026, Global 100 gained 18.6 % over one year, 50.3 % over three years and 37.0 % over five years. You will find the figures for all 18 strategies in the Evaluno pillar 3a fund comparison.
It depends on your investment horizon and your risk capacity. If you have more than ten years until withdrawal, a high equity share such as Global 80 or Global 100 is often suitable. Over five years, Global was ahead of Sustainable and Switzerland at every level that includes equities.
Yes. Instead of a ready-made strategy, you put together your portfolio from over 130 index funds, including gold or Bitcoin. For funds in foreign currencies, currency costs of 0.05 % may apply, often less thanks to internal netting.
No, not at the moment. The «100% Cash» strategy earns 0.00 % interest, and the fee of 0.39 % still applies. You will find interest-bearing, fee-free 3a accounts at frankly, for example.
Fully digitally in the app or in the browser: you determine your risk capacity, choose the investment focus, fund house and strategy and are done in a few minutes. There is no minimum amount.
In the app, you choose the transfer under «Deposit», receive the transfer form as a PDF, by email or by post and submit it signed to your current provider. finpension does not charge a fee for the transfer.
Up to five portfolios, each with its own strategy. With several portfolios, you can later spread the withdrawal over several years and save tax.
Yes. Missed payments from 2025 onwards can be made up for up to ten years retroactively, in the app under «Deposit» with a back payment for previous years.
A withdrawal is only possible for legal reasons, for example on retirement, for owner-occupied property, on becoming self-employed or on emigrating. For an early withdrawal for home ownership, finpension charges CHF 250, and CHF 200 for a pledge.
Silvan Forster is an author and co-founder of Evaluno.ch. He studied business administration with a specialisation in Banking & Finance and, with around ten years in the financial industry, knows financial products and their fee structures first-hand. He is a finpension customer himself and wrote this review using his own account.
More about Silvan ForsterSource: provider websites, product documents and direct information from providers, as of .
All information without guarantee. Past performance is no indicator of future results, prices can fluctuate. Evaluno earns a commission when an account is opened through some of these links. This does not change the results or their ranking. Evaluno’s methodology
Related topics
Pillar 3a fund comparison
373 pillar 3a funds compared: costs from 0.10 % to 1.71 %, five-year performance, filterable by equity share. Compare independently.
View comparison
frankly review
ZKB’s frankly 3a tested with a real account: fees, returns of all 15 products and a comparison with VIAC and finpension. CHF 35 with code Evaluno35.
Read the reviewLegal disclaimer
Evaluno does not provide investment, legal or tax advice and is no substitute for personal advice.